

|
시장보고서
상품코드
2124507
압력 제어 시추 서비스 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Managed Pressure Drilling Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
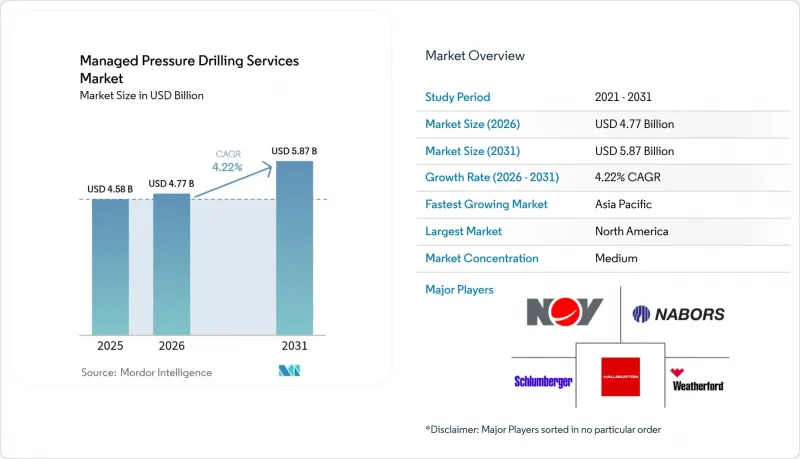
에 의하면, 압력 제어 시추 서비스 시장 규모는 2025년 45억 8,000만 달러에서 2026년에는 47억 7,000만 달러에 이르고, 2026-2031년 CAGR 4.22%로 성장을 지속하여 2031년에는 58억 7,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 기술별(정저공압 등), 서비스 유형별(장비 임대, 운영·시행 등), 압력 조건별(저압 및 고압), 유정 유형별(생산, 탐사, 개수),환경별(기존, 비기존 등), 용도별(육상 및 해상), 지역별(북미, 아시아태평양, 기타)
전 세계 압력 제어 시추 서비스 시장 동향과 인사이트
심해 분야의 설비 투자 회복이 가속화
2022년 이후 승인된 심해 예산은 연간 2,000억 달러를 넘어, 2015년부터 2020년까지 이어진 투자 부진을 뒤집으며 제어 압력 시추 서비스 시장의 발전에 대한 새로운 수요를 뒷받침하고 있습니다. 쉐브론(Chevron)의 57억 달러 규모의 ‘앵커(Anchor)’ 프로젝트는 이러한 변화를 여실히 보여주고 있으며, 극히 제한된 시간 내에 안전하게 시추를 수행하기 위해 첨단 MPD 기술을 활용한 20,000 psi 시스템을 채택하고 있습니다. 2025년에는 드릴십의 가동률이 97%에 육박할 전망이며, 첨단 압력 제어 기능을 갖춘 시추 장비가 우선적으로 선택될 것이므로, 계약업체들은 높은 일당 요금을 제시할 수 있게 될 것입니다. 승인된 각 심해 프로젝트에서는 일반적으로 탐사, 평가, 생산 단계에 걸쳐 여러 개의 MPD 대응 유정이 시추되므로 서비스 수요는 더욱 증가할 것입니다. 기술적 차별화는 수년에 걸친 계약 수주 잔고를 확보하려는 서비스 제공업체에게 여전히 매우 중요한 경쟁 우위 요소로 남아 있습니다.
MENA 지역의 HPHT 유정 개발 급증
중동 및 북아프리카(MENA) 지역의 국영 석유 회사들은 15,000 psi 및 350°F를 초과하는 저류층을 목표로 하고 있으며, 안전한 유정 건설을 위해서는 관리 압력 시추(MPD) 서비스를 통한 시장 솔루션이 필수적입니다. 할리버튼과 네이버스가 오만에서 수행한 자동 로터리 시추 및 슬라이드 시추는 AI를 활용한 MPD가 빠르게 표준 운영 기법으로 자리 잡고 있음을 여실히 보여줍니다. 사우디아라비아, 아랍에미리트(UAE), 카타르의 규제 체계에서는 현재 소정의 압력 임계치를 초과하는 유정에 대해 MPD가 의무화되어 있어 그 도입이 가속화되고 있습니다. HPHT 프로젝트가 확대되는 가운데, 검증된 HPHT 툴킷과 충분한 인력을 확보한 서비스 제공업체는 뚜렷한 우위를 점하고 있습니다.
변동성이 심한 시추선 일당 요금이 MPD 예산을 압박
2024년, 가혹한 환경에서 반잠수식 시추 장비의 일일 요금은 39만-51만 달러에 달하고, 9년 만에 최고치를 기록했으며, 이는 재량적인 시추 지출을 압박했습니다. MPD 서비스는 일반적으로 유정 총 비용의 15-25%를 차지하기 때문에 요금의 급등으로 인해 운영사는 도입을 연기하거나 규모를 축소하게 됩니다. 토탈에너지스가 고성능 드릴십의 지분 과반수를 보유하고 있는 것과 같은 소유 모델은 치솟는 비용을 억제하려는 노력을 여실히 보여주고 있습니다. 시추 장비 요금은 2026년까지 완만하게 안정될 것으로 예상되지만, 호황과 불황의 주기가 MPD 예산 수립에 있어 신중한 태도를 취하게 하는 배경이 되고 있습니다.
부문별 분석
2025년, 정상 저부 압력 방식은 관리 압력 시추 서비스 시장 규모의 46.10%를 차지하며, 대륙붕, HPHT(고압·고온), 육상 유정 등 폭넓은 적용성을 반영하고 있습니다. 그러나 심해 시추 업체들이 진흙 용액의 무게와 라이저 압력을 분리하여 시추공 내 응력을 줄이고 킥 저항성을 향상시키는 능력을 활용함에 따라, 듀얼 그라디언트 시스템은 2031년까지 연평균 성장률(CAGR) 5.95%로 확대되고 있습니다.
이러한 듀얼 그라디언트 기술의 급속한 증가는 신속한 압력 보정을 위해 지표면의 제어 루프와 동기화되는 통합형 해저 펌프의 도입과 시기를 같이하고 있습니다. AI 연동 센서를 통해 시추공 바닥 압력 분석이 미세 조정되어, 시추공의 벌루닝 현상이 감소하고 있습니다. 머드캡 시추는 완전 유실 시나리오를 위한 틈새 기법이며, 리턴 플로우 제어 기법은 셰일 플레이의 측구에서 활용되고 있지만, 둘 다 관리 압력 시추 서비스 시장 전체로 확산되고 있는 자동화의 물결로부터 혜택을 받고 있습니다.
2025년에는 운영사가 특수 매니폴드, 초크, 회전식 제어 장치와 관련된 설비 투자를 회피함에 따라 장비 대여가 매출의 47.70%를 차지했습니다. 운영 및 실행 패키지 부문의 제어 압력 시추 서비스 시장 규모는 인력 부족과 위험 분담 인센티브에 힘입어 연평균 성장률(CAGR) 5.55%라는 빠른 속도로 확대될 것으로 예측됩니다.
통합형 계약에서는 하드웨어 외에도 인증된 인력, 실시간 분석 및 성능 보증이 패키지로 제공되므로, 운영사는 최신 툴셋을 활용하면서 실행 위험을 전가할 수 있습니다. 설계 및 엔지니어링 서비스에 대한 수요는 안정적이며, 특히 맞춤형 유체 해석 모델이 필요한 프론티어 HPHT 유정 및 CCS 유정에서 수요가 증가하고 있습니다. 계약업체들이 각국의 작업자 자격 취득 및 원격 운영 센터 구축을 서두르는 가운데, 교육 및 지원에 대한 수요도 증가하고 있습니다.
지역별 분석
북미는 2025년에도 셰일층 재파쇄, 퍼미안 분지의 HPHT 수평정, 멕시코만의 초심해정이 맞물려 MPD 수요를 끌어올린 결과, 매출에서 38.10%의 선두를 유지했습니다. AI를 활용한 압력 자동화의 조기 도입과 확립된 교육 인프라 덕분에 서비스 비용은 경쟁력을 유지하고 있습니다. SLB의 통합 시추 계약에 힘입은 멕시코의 트리온 유전은 국영 석유 회사에서 MPD의 지역적 보급이 더욱 확대되고 있음을 보여줍니다.
아시아태평양은 관리 압력 시추 서비스 시장 부문에서 가장 빠르게 성장하고 있으며, 2031년까지 연평균 성장률(CAGR) 6.82%를 나타낼 것으로 예측됩니다. 중국의 수심 8km에 위치한 순베이(Shunbei) 유정이나 쓰촨성의 과압 셰일층에 진출하기 위해서는 H2S 유입을 방지하기 위한 정밀한 압력 엔벨로프가 필요합니다. 인도의 시추 장비 수는 2024년 111기에서 2028년까지 142기로 증가할 것으로 예측되며, 이에 따라 해상 KG 분지의 HPHT(고온고압) 유정 및 라자스탄주의 육상 평가 시추 프로젝트를 위해MPD 수요가 더욱 확대될 전망입니다. 동남아시아에서는 말레이시아와 인도네시아에서 심해 가스 개발 전망이 다시 높아지고 있는 반면, 호주에서는 넷제로 목표에 부합하는 CCS(탄소 포집 및 저장) 시범 시추공 준비가 진행되고 있습니다.
유럽에서는 북해의 HPHT 유정, 발트해의 CCS 시범 프로젝트, 그리고 독일과 프랑스의 지열 개발 거점에 힘입어 꾸준한 성장이 예상됩니다. EU의 엄격한 유정 건전성 규정에 따라 지열 유정 및 CCS 유정의 라이선스 조건에 MPD가 포함되면서, 기술 도입 수요가 더욱 강해지고 있습니다. 노르웨이의 모든 유전에서의 MPD 도입 기준은 모범 사례를 유럽 전역으로 더욱 확산시키는 계기가 되고 있습니다.
중동 및 아프리카에서는 사우디아라비아와 카타르의 HPHT 탄산염암 개발에 더해, 나미비아와 앙골라에서 진행 중인 새로운 심해 개발 프로젝트가 호재로 작용하고 있습니다. 국영 석유 회사의 의무화 조치와 HPHT 목표가 견조한 수요를 뒷받침하고 있지만, 현지 인력 확보는 여전히 병목 현상으로 남아 있습니다. 브라질의 프레솔트층과 아르헨티나의 비전통 가스전 ‘바카 무에르타’가 남미의 성장을 주도하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.14According to Mordor Intelligence, the managed pressure drilling services market size is expected to grow from USD 4.58 billion in 2025 to USD 4.77 billion in 2026 and is forecast to reach USD 5.87 billion by 2031 at 4.22% CAGR over 2026-2031.
This report is Segmented by Technology (Constant Bottom-Hole Pressure, and More), Service Type (Equipment Rental, Operations & Execution, and More), Pressure Regime (Low-Pressure and High-Pressure), Well Type (Production, Exploration, and Work-Over), Environment (Conventional, Unconventional, and More), Application (Onshore and Offshore), and Geography (North America, Asia-Pacific, and More)
Global Managed Pressure Drilling Services Market Trends and Insights
Accelerating Deep-water CAPEX Rebound
Sanctioned deepwater budgets have exceeded USD 200 billion annually since 2022, reversing the 2015-2020 investment drought and fuelling fresh demand for managed pressure drilling services market deployments. Chevron's USD 5.7 billion Anchor project illustrates the shift, employing 20,000 psi systems that rely on sophisticated MPD to drill safely in ultra-narrow windows. Drillship utilisation nearing 97% in 2025 prioritises rigs fitted with advanced pressure control, allowing contractors to command premium dayrates. Each sanctioned deepwater campaign typically entails multiple MPD-enabled wells across exploration, appraisal, and production phases, compounding service demand. Technology differentiation remains a pivotal competitive lever for service providers positioning for multi-year contract backlogs.
Surge in HPHT Well Development in MENA
National oil companies across the Middle East and North Africa target reservoirs exceeding 15,000 psi and 350 °F, where managed pressure drilling services market solutions become indispensable for safe wellbore construction. Automated rotary and slide drilling executed in Oman by Halliburton and Nabors underscores how AI-enhanced MPD is fast becoming standard operating practice . Regulatory frameworks in Saudi Arabia, the UAE, and Qatar now require MPD on wells surpassing defined pressure thresholds, accelerating adoption. As HPHT projects proliferate, service providers with proven HPHT toolkits and crew availability enjoy a clear advantage.
Volatile Rig-day Rates Squeezing MPD Budgets
Harsh-environment semisubs commanded USD 390,000-510,000 per day in 2024, a nine-year high that narrowed discretionary drilling spend. MPD services typically add 15-25% to total well costs, so sudden rate spikes lead operators to defer or downgrade deployments. Ownership models such as TotalEnergies' majority stake in a high-spec drillship highlight efforts to tame escalating costs. While rig rates are expected to ease modestly by 2026, the boom-bust cycle underpins cautious MPD budgeting.
Other drivers and restraints analyzed in the detailed report include:
- Post-2025 Shale Refrac Wave in North America
- AI-driven Downhole Pressure Automation
- Limited Global Pool of Certified MPD Crews
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Constant bottom-hole pressure methods contributed 46.10% to the managed pressure drilling services market size in 2025, reflecting their broad applicability across shelf, HPHT, and onshore wells. However, dual-gradient systems are climbing at a 5.95% CAGR to 2031 as deepwater operators exploit their ability to decouple mudweight from riser pressure, lowering downhole stress and improving kick tolerance.
The dual-gradient surge coincides with integrated seabed pump deployments synchronizing with surface control loops for rapid pressure corrections. AI-linked sensors fine-tune bottomhole pressure analytics, cutting wellbore ballooning events. Mud-cap drilling remains niche for total-loss scenarios, and return-flow control methods serve laterals in shale plays, yet both benefit from the broader automation wave permeating the managed pressure drilling services market.
Equipment rental held 47.70% revenue in 2025 as operators avoided capital commitments tied to specialised manifolds, chokes, and rotating control devices. The managed pressure drilling services market size for operations and execution packages is forecast to rise faster at a 5.55% CAGR, propelled by crew scarcity and risk-sharing incentives.
Integrated contracts bundle hardware with certified personnel, real-time analytics, and performance guarantees, letting operators transfer execution risk while accessing the latest toolsets. Design and engineering services maintain a stable demand, particularly for frontier HPHT and CCS wells requiring bespoke hydraulics modelling. Training and support demand is swelling as contractors race to certify national crews and enable remote operations centres.
Complete Report Scope:
- By Technology
- Constant Bottom-Hole Pressure
- Mud-Cap Drilling
- Dual-Gradient Drilling
- Return-Flow Control Drilling
- Other Emerging Techniques
- By Service Type
- Design and Engineering
- Equipment Rental
- Operations and Execution
- Training and Support
- By Pressure Regime
- Low-Pressure/Narrow Window
- High-Pressure/High-Temperature (HPHT)
- By Well Type
- Wildcat/Exploration
- Development Production
- Work-over and Re-entry
- By Drilling Environment
- Conventional Hydrocarbon
- Unconventional (Shale, Tight, CBM)
- Geothermal
- CCS and Hydrogen Storage
- By Application
- Onshore
- Offshore
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
North America preserved a 38.10% revenue lead in 2025 as shale refracs, Permian HPHT horizontals, and Gulf of Mexico ultra-deepwater wells collectively boosted MPD demand. Early adoption of AI-enabled pressure automation and an established training infrastructure keeps service costs competitive. Mexico's Trion field, backed by SLB's integrated drilling contract, signals deeper regional penetration of MPD for national oil companies.
Asia-Pacific is the fastest-growing managed pressure drilling services market segment, set for a 6.82% CAGR to 2031. China's push into 8-km deep Shunbei wells and Sichuan over-pressured shales requires precise pressure envelopes to avoid H2S influx. India's rig count is projected to rise from 111 in 2024 to 142 by 2028, creating incremental MPD demand for offshore KG basin HPHT wells and onshore Rajasthan appraisal campaigns. Southeast Asia revives deepwater gas prospects in Malaysia and Indonesia, while Australia preps CCS pilot wells aligned with net-zero targets.
Europe shows steady growth fuelled by North Sea HPHT wells, Baltic CCS pilots, and geothermal hotspots in Germany and France. The EU's stringent well-integrity rules embed MPD in licensing conditions for geothermal and CCS wells, reinforcing technology pull. Norway's full-field MPD adoption standard further diffuses best practice across the continent.
The Middle East and Africa benefit from HPHT carbonate developments in Saudi Arabia and Qatar, plus emerging deepwater campaigns in Namibia and Angola. National oil company mandates and HPHT targets underpin robust demand, though crew localisation remains a bottleneck. Brazil's pre-salt and Argentina's unconventional Vaca Muerta drive anchor South America's growth.
- Halliburton Company
- Schlumberger Ltd
- Weatherford International plc
- NOV Inc.
- Nabors Industries Ltd
- Global MPD Services
- Ensign Energy Services Inc.
- Air Drilling Associates Inc.
- Blade Energy Partners Ltd
- Exceed (XCD) Holdings Ltd
- Pruitt MPD
- Beyond Energy Services & Technology
- Scientific Drilling International
- Secure Drilling (Petrofac)
- Wild Well Control
- Archer Ltd
- Helmerich & Payne (MPD unit)
- Welltec A/S
- Cougar Drilling Solutions
- GOSCO Drilling Solutions
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating deep-water CAPEX rebound
- 4.2.2 Surge in HPHT well development in MENA
- 4.2.3 Post-2025 shale refrac wave in North America
- 4.2.4 AI-driven downhole pressure automation
- 4.2.5 CCS & hydrogen-ready well design standards
- 4.2.6 Mandatory MPD adoption for geothermal wells in EU
- 4.3 Market Restraints
- 4.3.1 Volatile rig-day rates squeezing MPD budgets
- 4.3.2 Limited global pool of certified MPD crews
- 4.3.3 Persistent data-ownership disputes in JV wells
- 4.3.4 Stricter drilling-fluid discharge limits in offshore Arctic
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Technology
- 5.1.1 Constant Bottom-Hole Pressure
- 5.1.2 Mud-Cap Drilling
- 5.1.3 Dual-Gradient Drilling
- 5.1.4 Return-Flow Control Drilling
- 5.1.5 Other Emerging Techniques
- 5.2 By Service Type
- 5.2.1 Design and Engineering
- 5.2.2 Equipment Rental
- 5.2.3 Operations and Execution
- 5.2.4 Training and Support
- 5.3 By Pressure Regime
- 5.3.1 Low-Pressure/Narrow Window
- 5.3.2 High-Pressure/High-Temperature (HPHT)
- 5.4 By Well Type
- 5.4.1 Wildcat/Exploration
- 5.4.2 Development Production
- 5.4.3 Work-over and Re-entry
- 5.5 By Drilling Environment
- 5.5.1 Conventional Hydrocarbon
- 5.5.2 Unconventional (Shale, Tight, CBM)
- 5.5.3 Geothermal
- 5.5.4 CCS and Hydrogen Storage
- 5.6 By Application
- 5.6.1 Onshore
- 5.6.2 Offshore
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Russia
- 5.7.2.7 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 India
- 5.7.3.3 Japan
- 5.7.3.4 South Korea
- 5.7.3.5 ASEAN Countries
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 South America
- 5.7.4.1 Brazil
- 5.7.4.2 Argentina
- 5.7.4.3 Rest of South America
- 5.7.5 Middle East and Africa
- 5.7.5.1 Saudi Arabia
- 5.7.5.2 United Arab Emirates
- 5.7.5.3 South Africa
- 5.7.5.4 Egypt
- 5.7.5.5 Rest of Middle East and Africa
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Halliburton Company
- 6.4.2 Schlumberger Ltd
- 6.4.3 Weatherford International plc
- 6.4.4 NOV Inc.
- 6.4.5 Nabors Industries Ltd
- 6.4.6 Global MPD Services
- 6.4.7 Ensign Energy Services Inc.
- 6.4.8 Air Drilling Associates Inc.
- 6.4.9 Blade Energy Partners Ltd
- 6.4.10 Exceed (XCD) Holdings Ltd
- 6.4.11 Pruitt MPD
- 6.4.12 Beyond Energy Services & Technology
- 6.4.13 Scientific Drilling International
- 6.4.14 Secure Drilling (Petrofac)
- 6.4.15 Wild Well Control
- 6.4.16 Archer Ltd
- 6.4.17 Helmerich & Payne (MPD unit)
- 6.4.18 Welltec A/S
- 6.4.19 Cougar Drilling Solutions
- 6.4.20 GOSCO Drilling Solutions
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


