

|
시장보고서
상품코드
2124531
인도의 CCTV : 시장 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)India CCTV - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 인도의 CCTV 시장 규모는 2025년에 48억 달러로 평가되었습니다. 2026년 57억 5,000만 달러에서 2031년까지 142억 5,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 19.88%를 나타낼 전망입니다.
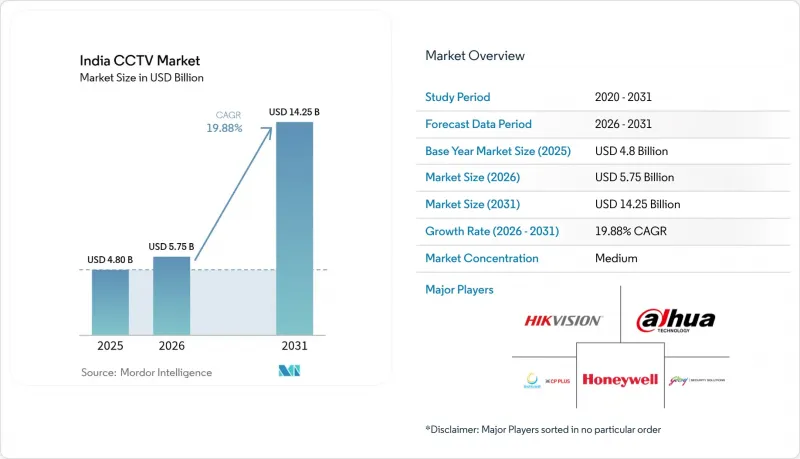
본 보고서는 유형별(아날로그 카메라, IP 카메라, PTZ 카메라, AI 지원 스마트 카메라), 최종 사용자 산업별(정부 기관, 산업 및 제조업, 은행, 금융서비스 및 보험(BFSI), 운송 및 물류, 주택·스마트 홈,소매 및 호스피탈리티, 의료·교육), 연결 방식별(유선·무선), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
인도의 CCTV 시장 동향 및 인사이트
정부의 스마트 시티 감시 추진
‘스마트 시티 미션’을 통해 감시는 사후 대응형 경찰 활동에서 예측형 도시 관리로 진화했습니다. 2025년 3월까지 총액 1조 4,400억 루피(160억 6,000만 달러)에 해당하는 프로젝트의 90%가 확정되었으며, 현재 7만 6,000대의 카메라가 지휘통제센터와 연동되어 그 데이터는 교통, 폐기물,비상사태 대응 등 각 모듈로 집약되고 있습니다. 조달 기준의 표준화를 통해 상호 운용성 기준을 충족할 수 있는 공급업체가 우대받고 있습니다. 마디아프라데시 주의 ‘통합 제어·지휘 센터’와 같은 클라우드 호스팅형 플랫폼은 유틸리티 전반에 걸친 자원 최적화를 입증하고 있습니다. 이 기반은 교통 체증과 범죄 활동을 미연에 방지하는 예측 분석도 뒷받침하고 있으며, 인도 전체 CCTV 시장의 안정적인 수요를 견인하고 있습니다.
공공 장소에서의 감시 의무화
주 법률에 따라 CCTV에 대한 지출은 규정 준수상의 필수 항목이 되어가고 있습니다. 카르나타카주의 ‘공공 안전 집행법’은월방문객 수가 500명 이상인 시설에 대해 카메라를 경찰 네트워크에 연결할 것을 의무화하고 있으며, 이는 방갈로르의 약 1만개 매장에 영향을 미치고 있습니다. 이와 유사한 법규는 경찰서의 감시 범위에 관한 대법원의 지침을 따르는 것이며, 규정 준수 미흡이 드러나면 즉각적인 조달을 촉진하고 있습니다. 사양서에서는 프레임 속도, 암호화, 저장 기간이 표준화되어 있어 제품의 품질을 높이는 동시에 기준을 충족하지 않는 수입품을 배제하고 있습니다.
여러 거점으로의 확장에 따른 높은 총 소유 비용
대규모 네트워크에서는 하드웨어 비용을 훨씬 초과하는 비용이 발생합니다. 여기에는 유지보수, 대역폭, 클라우드 스토리지가 포함되며, 3년 이내에 초기 투자액을 초과할 가능성이 있습니다. 분산된 거점에서는 대개 위성 회선이나 전용 광섬유 회선이 필요하며, 거점당 연간 5만-10만 루피의 비용이 듭니다. 고해상도 영상은 매달 수 테라바이트의 데이터를 생성하기 때문에 기업은 엣지 스토리지나 상위 클라우드 요금제 도입을 피할 수 없습니다. 2급 및 3급 도시의 숙련된 인력 부족은 설치 비용을 상승시키고 가동 시작을 지연시키고 있습니다. 이러한 상황으로 인해 중소기업의 도입이 주춤해지면서, 수익성이 낮은 부문에서 인도의 CCTV 시장의 성장 속도가 둔화될 가능성이 있습니다.
부문별 분석
2025년, 인도의 CCTV 시장에서 아날로그 장비는 51.65%의 점유율을 유지했습니다. 이는 비용을 중시하는 공공 부문의 입찰과 기존 동축 케이블 배선에 힘입은 결과입니다. IP 모델은 원격 감시 및 PoE의 편의성 덕분에 40.55%의 점유율을 기록했습니다. PTZ 카메라는 공항이나 석유 터미널 등 광범위한 감시 수요를 충족시키며 5.85%를 차지했습니다. AI가 탑재된 스마트 카메라는 틈새 시장이지만, 연평균 성장률(CAGR) 20.55%로 확대될 것으로 예측되며, 지능형 엔드포인트 분야의 인도의 CCTV 시장 규모를 직접적으로 끌어올릴 것으로 전망됩니다.
낮은 도입 비용과 교체 용이성 덕분에 아날로그 방식은 여전히 입지를 유지하고 있지만, 2025년 4월 시행된 STQC 규정에 따라 구매자들은 사이버 보안 대책이 적용되고 업그레이드가 가능한 기기로 전환하도록 권장받고 있습니다. Aditya Infotech 및 Prama Hikvision과 같은 국내 기업들은 현재 전자정보기술부의 요건을 준수하기 위해 기기 내 분석 기능과 보안 부팅 기능을 결합하여 제공합니다. 이에 따라 AI 지원 모델이 아날로그 방식 시장 점유율을 잠식하며, 인도 CCTV 시장의 향후 점유율 추이를 재편하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장률 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the India CCTV market size was valued at USD 4.8 billion in 2025 and estimated to grow from USD 5.75 billion in 2026 to reach USD 14.25 billion by 2031, at a CAGR of 19.88% during the forecast period (2026-2031).
This report is Segmented by Type (Analog Cameras, IP Cameras, PTZ Cameras, AI-Enabled Smart Cameras), End-User Verticals (Government, Industrial and Manufacturing, BFSI, Transportation and Logistics, Residential and Smart Homes, Retail and Hospitality, Healthcare and Education), Connectivity (Wired and Wireless), and Region. The Market Forecasts are Provided in Terms of Value (USD).
India CCTV Market Trends and Insights
Government Smart-City Surveillance Push
The Smart Cities Mission elevated surveillance from reactive policing to predictive city management. With 90% of projects worth INR 1.44 trillion (USD 16.06 billion) finalized by March 2025, 76,000 cameras now integrate with command-and-control centers that funnel data to traffic, waste, and emergency modules. Standardized procurement favors suppliers able to meet interoperability benchmarks. Cloud-hosted platforms, such as Madhya Pradesh's Integrated Control and Command Centre, illustrate resource optimization across utilities. The same backbone supports predictive analytics that pre-empt congestion and criminal activity, reinforcing steady demand across the India CCTV market.
Mandatory Surveillance Regulations for Public Spaces
State legislation is turning CCTV expenditure into a compliance item. Karnataka's Public Safety Enforcement Act requires establishments with 500-plus monthly footfall to connect cameras to police networks, impacting roughly 10,000 Bengaluru outlets. Similar statutes follow Supreme Court directives for police-station coverage, exposing non-compliance gaps that spur immediate procurement. specifications standardize frame rates, encryption, and retention periods, elevating product quality while weeding out sub-standard imports.
High Total Cost of Ownership for Multi-Site Rollouts
Large networks incur costs far beyond hardware, covering maintenance, bandwidth, and cloud storage that can outstrip initial capital outlay within three years. Dispersed sites often need satellite or private fiber links costing INR 50,000-100,000 yearly per location. High-definition video can generate several terabytes monthly, pushing enterprises toward edge storage or higher-tier cloud plans. Skilled labor shortages in tier-2 and tier-3 cities inflate installation fees and delay commissioning. These dynamics slow adoption among SMEs and may cap the expansion speed of the India CCTV market in less bankable segments.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Infrastructure Expansion of Airports and Metro Systems
- AI-Driven Compliance and Safety Analytics Adoption
- Rising Privacy and Data-Protection Obligations (DPDP Act)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Analog units retained a 51.65% share of the India CCTV market in 2025, supported by cost-sensitive public-sector tenders and legacy coaxial cabling. IP models reached 40.55% share thanks to remote monitoring and PoE convenience. PTZ cameras contributed 5.85%, addressing large-area coverage in airports and oil terminals. AI-enabled smart cameras, although niche, are forecast to expand at a 20.55% CAGR, directly lifting the India CCTV market size for intelligent endpoints.
Low acquisition cost and ease of swap-out keep analog in play, yet STQC rules that took effect in April 2025 push buyers toward cyber-secure, upgradeable devices. Domestic firms such as Aditya Infotech and Prama Hikvision now bundle on-device analytics and secure boot to comply with the Ministry of Electronics mandates. AI-ready models thereby erode analog headroom, reshaping future India CCTV market share trajectories.
Complete Report Scope:
- By Type
- Analog Cameras
- IP Cameras (Non-PTZ)
- PTZ Cameras
- AI-enabled Smart Cameras
- By End-user Verticals
- Government
- Industrial and Manufacturing
- BFSI
- Transportation and Logistics
- Residential and Smart Homes
- Retail and Hospitality
- Healthcare and Education
- Other End-user Verticals
- By Connectivity
- Wired
- Wireless (Wi-Fi/4G/5G)
- By Region
- North India
- South India
- East India
- West India
- Central India
List of Companies Covered in this Report:
- HIKVISION Digital Technology Co. Ltd (Hikvision India)
- Dahua Technology India Pvt. Ltd
- Aditya Infotech Ltd (CP Plus)
- Honeywell Commercial Security
- Godrej Security Solutions
- Axis Video Systems India Pvt. Ltd
- Bosch Security Systems India
- D-Link India Limited
- Videocon Industries Limited
- Zicom Electronic Security Systems
- Electronic Eye Systems
- Vantage Security Ltd
- Vintron Informatics Ltd
- Digitals India Security Products Pvt. Ltd
- Total Surveillance Solutions Pvt. Ltd
- HFCL Ltd
- Prizor Viztech Limited
- Dixon Technologies (India) Limited
- Sparsh Securitech Pvt. Ltd
- Qubo (Hero Electronix Private Limited)
- Uniview Technology India
- Samsung Hanwha Techwin India
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government smart-city surveillance push
- 4.2.2 Mandatory surveillance regulations for public spaces
- 4.2.3 Rapid infrastructure expansion of airports and metros
- 4.2.4 AI-driven compliance and safety analytics adoption
- 4.2.5 Shift toward indigenous manufacturing post STQC/BIS norms
- 4.2.6 Solar-powered edge CCTV deployments in rural schemes
- 4.3 Market Restraints
- 4.3.1 High total cost of ownership for multi-site rollouts
- 4.3.2 Rising privacy and data-protection obligations (DPDP Act)
- 4.3.3 Cyber-security certification burden slowing launches
- 4.3.4 Semiconductor and import restrictions disrupting supply
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.6.1 AI video analytics and VSaaS
- 4.6.2 Edge-based low-power cameras
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Domestic Production vs Imports
- 4.9 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Analog Cameras
- 5.1.2 IP Cameras (Non-PTZ)
- 5.1.3 PTZ Cameras
- 5.1.4 AI-enabled Smart Cameras
- 5.2 By End-user Verticals
- 5.2.1 Government
- 5.2.2 Industrial and Manufacturing
- 5.2.3 BFSI
- 5.2.4 Transportation and Logistics
- 5.2.5 Residential and Smart Homes
- 5.2.6 Retail and Hospitality
- 5.2.7 Healthcare and Education
- 5.2.8 Other End-user Verticals
- 5.3 By Connectivity
- 5.3.1 Wired
- 5.3.2 Wireless (Wi-Fi/4G/5G)
- 5.4 By Region
- 5.4.1 North India
- 5.4.2 South India
- 5.4.3 East India
- 5.4.4 West India
- 5.4.5 Central India
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 HIKVISION Digital Technology Co. Ltd (Hikvision India)
- 6.4.2 Dahua Technology India Pvt. Ltd
- 6.4.3 Aditya Infotech Ltd (CP Plus)
- 6.4.4 Honeywell Commercial Security
- 6.4.5 Godrej Security Solutions
- 6.4.6 Axis Video Systems India Pvt. Ltd
- 6.4.7 Bosch Security Systems India
- 6.4.8 D-Link India Limited
- 6.4.9 Videocon Industries Limited
- 6.4.10 Zicom Electronic Security Systems
- 6.4.11 Electronic Eye Systems
- 6.4.12 Vantage Security Ltd
- 6.4.13 Vintron Informatics Ltd
- 6.4.14 Digitals India Security Products Pvt. Ltd
- 6.4.15 Total Surveillance Solutions Pvt. Ltd
- 6.4.16 HFCL Ltd
- 6.4.17 Prizor Viztech Limited
- 6.4.18 Dixon Technologies (India) Limited
- 6.4.19 Sparsh Securitech Pvt. Ltd
- 6.4.20 Qubo (Hero Electronix Private Limited)
- 6.4.21 Uniview Technology India
- 6.4.22 Samsung Hanwha Techwin India
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


