|
시장보고서
상품코드
2124536
표면실장기술(SMT) : 시장 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)Surface Mount Technology - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
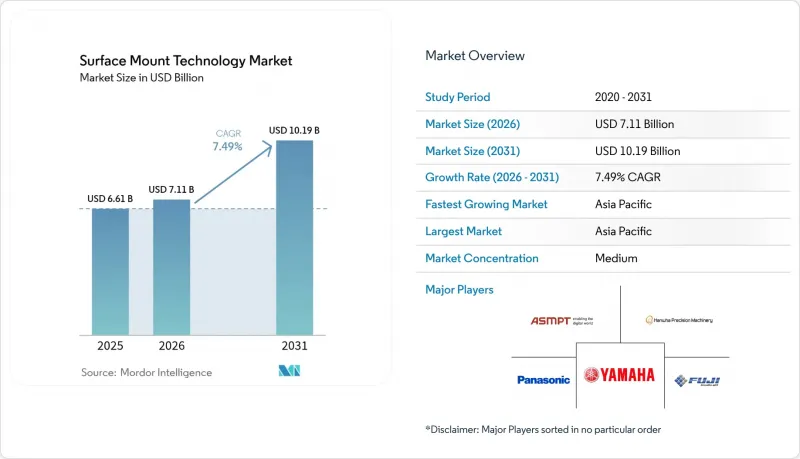
에 의하면, 표면실장기술(SMT) 시장 규모는 2025년에 66억 1,000만 달러로 평가되었습니다. 2026년 71억 1,000만 달러에서 2031년까지 101억 9,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 7.49%를 나타낼 전망입니다.
본 보고서는 부품별(수동 부품(저항기, 커패시터) 등), 장비 유형별(실장 장비(고속 픽 앤 플레이스 기계) 등), 조립 라인 유형별(다품종 소량 생산 등),최종 사용자 산업별(소비자용 전자기기 등), 지역별(북미, 남미 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 표면실장기술(SMT) 시장 동향 및 인사이트
IoT·웨어러블 기기가 초고밀도 PCB 채택을 촉진
현재, 디바이스 제조업체들은 스마트 워치 한 대에 1만 개 이상의 다층 세라믹 커패시터를 탑재하고 있으며, 그 수는 5년 전과 비교해 3배로 증가했습니다. 50µm 미만의 전도성 트레이스나 75µm 미만의 마이크로 비아를 형성하기 위해서는 01005 패키지를 ±25µm의 정밀도로 안정적으로 처리할 수 있는 실장 장비가 필요합니다. FCC 방사 한계 및 IEC 안전 요건 준수에 따라 전자기 간섭(EMI) 차폐 대책이 더욱 강화되고 있으며, 정밀 솔더 페이스트 검사 및 자동 광학 검사(AOI) 시스템에 대한 수요가 증가하고 있습니다.
자동차용 ADAS 전자기기의 채택이 신뢰성 요건을 재정의
전기자동차의 레퍼런스 설계에서는 차량당 1만 개 이상의 MLCC와 200개 이상의 전자 제어 장치가 사용되고 있으며, 수명 주기 인증 기간이 3년을 초과함에도 불구하고 SMT 생산량은 증가하고 있습니다. ISO 26262의 기능 안전 요구 사항 및 -40°C-150°C의 작동 온도 범위로 인해, 공급업체는 자동차용 PPAP 및 AEC-Q200 스트레스 테스트에 기반한 공정 인증을 의무적으로 받아야 합니다. 납땜 접합부의 장기 신뢰성을 검증할 수 있는 장비 제조업체는 유럽과 일본에서 수년에 걸친 공급 계약을 확보하고 있습니다.
막대한 초기 설비 투자가 중소기업의 발목을 잡고 있습니다.
차세대 배치 플랫폼은 인라인 SPI, AOI, X선 검사 장비와 세트로 도입할 경우, 라인당 300만 달러 이상의 비용이 듭니다. 예지保全 분석을 통해 총 소유 비용은 절감되지만, 많은 중소 EMS 공급업체들은 3년 이내에 투자 회수를 정당화하는 데 어려움을 겪고 있습니다. 장비 임대나 성과 연동형 서비스 계약이 등장하고 있지만, Tier 1 OEM을 제외하면 여전히 일반적이지 않습니다.
부문별 분석
2025년, AI 서버 및 전기자동차의 MCU, ASIC, 전력 관리에 대한 수요가 가속화됨에 따라 능동 소자는 표면실장기술(SMT) 시장 점유율의 65.74%를 차지했습니다. 이 부문은 이기종 SoC 설계 및 고전압 트랜지스터의 채택 확대에 힘입어 2031년까지 연평균 성장률(CAGR) 8.62%를 나타낼 것으로 예측됩니다. 수동 부품은 5G 휴대전화 및 자동차용 트랙션 인버터에서의 사용량 증가로 여전히 혜택을 보고 있지만, 세라믹 및 탄탈륨 소재공급 부족으로 인해 공급망의 회복력을 시험하는 상황이 지속되고 있습니다.
고객의 기대는 부품 비용 절감에서 기판 수준의 집적 밀도와 장기적인 신뢰성으로 변화하고 있습니다. 각 OEM 업체들은 10ppm 미만의 고장률과 15년의 실제 가동 수명을 요구하고 있으며, 이는 기판 공급업체, 부품 제조업체 및 실장 장비 공급업체 간의 더욱 긴밀한 협력을 촉진하고 있습니다. 능동·수동 부품의 공동 설계 라이브러리나 조립을 고려한 설계(DFA)에 대한 종합적인 검토를 제공하는 공급업체는 신제품의 양산 시작을 가속화하며, 첨단 웨어러블 기기 및 산업용 IoT 게이트웨이 분야에서 ‘우선 공급업체’로서의 입지를 확고히 하고 있습니다.
2025년에도 실장 장비는 표면실장기술(SMT) 시장 규모의 42.62%를 차지했지만, 검사 장비는 연평균 성장률(CAGR) 8.83%로 가장 빠르게 성장하고 있습니다. 고속 픽 앤 플레이스 기계는 헤드 압력을 자동으로 조정하는 머신러닝 비전 시스템의 지원으로 현재 100 k cph의 처리 속도와 ±10µm의 정밀도를 달성하고 있습니다. 납땜 장치의 경우, 무연 합금이 더 엄격한 열 구배를 요구하기 때문에 공정 범위의 축소에 직면해 있지만, 스크린 인쇄 플랫폼에서는 첫 번째 통과 수율을 향상시키기 위해 폐쇄 루프 SPI 피드백이 채택되고 있습니다.
투자 동력은 딥러닝을 활용하여 오감지율을 90% 줄이고 검사 속도를 4배 높이는 AOI 및 X선 검사 시스템에 집중되고 있습니다. ViTrox와 Koh Young은 IPC-CFX 연결 기능을 통합하여 수율 저하 추세를 몇 분 이내에 감지하는 실시간 분석을 실현하고 있습니다. 분석 서비스 구독이 포함된 설비 금융 패키지는 고액의 초기 비용 부담을 줄여주어, 동유럽 및 동남아시아의 2차 EMS 기업들이 생산 라인을 업그레이드하도록 촉진하고 있습니다.
지역별 분석
아시아태평양은 2025년에 표면실장기술(SMT) 시장 점유율의 48.05%를 차지하며 주도적인 위치를 차지했으며, 2031년까지 연평균 성장률(CAGR) 8.12%를 나타낼 것으로 예측됩니다. 중국, 대만, 한국은 합쳐서 2027년까지 신규 300mm 팹에 840억 달러 이상을 투자할 예정이며, 업스트림 기판 및 부품의 생산 능력을 확보할 전망입니다. TSMC와 JASM의 200억 달러 규모 확장을 핵심으로 하는 일본의 구마모토 클러스터는 월간 10만 장 이상의 12인치 웨이퍼 생산 능력을 확대함과 동시에 3,400명의 하이테크 분야 일자리를 창출할 것입니다.
북미는 뒤처져 있지만 ‘CHIPS 법’에 따라 가속화되고 있으며, 이미 발표된 프로젝트를 통해 해당 지역의 생산 능력에 대한 투자액은 2024년 120억 달러에서 2027년까지 247억 달러로 두 배 증가할 전망입니다. 애리조나주와 뉴욕주에서 진행 중인 첨단 패키징 시범 프로젝트는 AI 가속기를 위해 10마이크로미터 미만의 배치를 목표로 하고 있으며, 태평양 횡단 해상 운송 경로에 대한 의존도를 낮추는 것을 목적으로 하고 있습니다. 사이버보안을 고려한 생산 공정에 대한 규제적 중시 덕분에, 각 공장은 CMMC 및 IPC-1791의 ‘트러스트드 빌더(Trusted Builder)’ 인증 획득을 추진하고 있습니다.
유럽에서는 자동차용 파워 반도체 및 와이드 밴드갭 디바이스에 주력하고 있으며, 인피니언과 ST마이크로일렉트로닉스가 800V 전기차 인버터를 지원하기 위한 설비 투자를 주도하고 있습니다. 이 지역의 RoHS 적용 범위 확대와 향후 도입될 에코디자인 규정은 수리 가능한 PCB를 뒷받침하고 있으며, 셀렉티브 솔더링 및 리워크 플랫폼에 대한 수요를 촉진하고 있습니다. 유럽의 ‘기술 협약(Pact for Skills)’에 기반한 인력 기술 향상 프로그램은 IPC의 공인 인터커넥트 디자이너 커리큘럼과 연계되어 있으며, 2029년까지 14만 6,000명의 인력 부족을 해소하는 것을 목표로 하고 있습니다.
중동 및 아프리카에서는 사우디아라비아와 아랍에미리트(UAE)가 EMS(전자기기 수탁 제조)에 대한 우대 조치와 공공요금 인하를 결합한 테크파크에 정부계 펀드의 자금을 투입하고 있어 꾸준한 진전이 나타나고 있습니다. 남아프리카공화국 하우텡 주의 허브에는 모듈식 SMT 라인을 활용하여 소량·다품목 수리 주문을 처리하는 통신 기기 리퍼비셔들이 모여 있습니다. 그러나 인프라 부족과 전문 인력 부족으로 인해 사하라 이남 대부분 시장에서는 최첨단 설비 도입이 제한되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장률 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTHAccording to Mordor Intelligence, the surface mount technology market size was valued at USD 6.61 billion in 2025 and estimated to grow from USD 7.11 billion in 2026 to reach USD 10.19 billion by 2031, at a CAGR of 7.49% during the forecast period (2026-2031).
This report is Segmented by Component (Passive Components [Resistors, Capacitors], and More), Equipment Type (Placement Equipment [High-Speed Pick-And-Place Machines], and More), Assembly Line Type (High-Mix/Low-Volume, and More), End-User Industry (Consumer Electronics, and More), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Surface Mount Technology Market Trends and Insights
IoT and Wearables Fuel Ultra-Dense PCB Adoption
Device makers now pack more than 10,000 multilayer ceramic capacitors into a single smartwatch, tripling the count seen five years ago. To print conductive traces below 50 µm and microvias under 75 µm, assemblies rely on placement tools that consistently handle 01005 packages at +-25 µm accuracy. Compliance with FCC emissions limits and IEC safety requirements is pushing additional electromagnetic-interference shielding steps, elevating demand for precision solder-paste inspection and automated optical inspection systems.
Automotive ADAS Electronics Adoption Reshapes Reliability Needs
Electric-vehicle reference designs use upward of 10,000 MLCCs and more than 200 electronic control units each, lifting SMT volumes even as lifecycle qualification stretches beyond three years. ISO 26262 functional-safety mandates and -40 °C to 150 °C operating windows compel suppliers to certify processes under automotive PPAP and AEC-Q200 stress tests. Equipment makers that can validate long-term solder-joint reliability are winning multiyear supply agreements across Europe and Japan.
High Upfront Capex Constrains Smaller Firms
Next-generation placement platforms cost upward of USD 3 million per line when bundled with in-line SPI, AOI, and x-ray testers. Although predictive-maintenance analytics lower total cost of ownership, many small and medium EMS providers struggle to justify payback within three years. Equipment rental and outcome-based service contracts are emerging but remain uncommon outside Tier-1 OEMs.
Other drivers and restraints analyzed in the detailed report include:
- 5G Infrastructure and High-Frequency Boards
- System-in-Package Integration in Smartphones
- Lead-Free Solder Thermal Constraints Lower Yield
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Active Components accounted for 65.74% of the Surface Mount Technology market share in 2025 as MCU, ASIC, and power-management demand accelerated in AI servers and electric vehicles. The segment is forecast to grow at an 8.62% CAGR to 2031 on the back of increased adoption of heterogenous SoC designs and high-voltage transistors. Passive Components still benefit from rising unit counts in 5G handsets and automotive traction inverters, but ceramic and tantalum material shortages continue to test supply-chain resiliency.
Customer expectations are evolving from component cost control to board-level integration density and long-tail reliability. OEMs request sub-10 ppm failure rates and 15-year field lifetimes, driving closer collaboration between substrate vendors, component makers, and placement-equipment suppliers. Suppliers that deliver active-passive co-design libraries and full Design-for-Assembly review accelerate new-product ramps, securing supplier-of-choice status for advanced wearables and industrial IoT gateways.
Placement Equipment still commands 42.62% of the Surface Mount Technology market size in 2025, but Inspection Equipment is rising fastest with a 8.83% CAGR. High-speed pick-and-place machines now hit 100 k cph with +-10 µm accuracy, aided by machine-learning vision systems that auto-tune head pressure. Soldering Equipment faces process-window squeezes as lead-free alloys demand tighter thermal gradients, while Screen-Printing platforms adopt closed-loop SPI feedback to boost first-pass yield.
Investment momentum favors AOI and x-ray systems that harness deep learning to cut false-call rates by 90 % and raise inspection speed four-fold. ViTrox and Koh Young incorporate IPC-CFX connectivity for real-time analytics that flag yield-eroding trends within minutes. Equipment finance packages bundling analytics subscriptions help offset sticker shock, enticing Tier-2 EMS firms in Eastern Europe and Southeast Asia to upgrade lines.
Complete Report Scope:
- By Component
- Passive Components
- Resistors
- Capacitors
- Active Components
- Transistors
- Integrated Circuits
- Passive Components
- By Equipment Type
- Placement Equipment
- High-speed Pick-and-Place Machines
- Soldering Equipment
- Reflow Ovens
- Wave Solder Systems
- Inspection Equipment
- Automated Optical Inspection (AOI)
- Solder Paste Inspection (SPI)
- X-ray Inspection
- Screen Printing Equipment
- Placement Equipment
- By Assembly Line Type
- High-Mix / Low-Volume (HMLV)
- High-Volume / High-Mix (HVHM)
- By End-user Industry
- Consumer Electronics
- Automotive
- Industrial Electronics
- Aerospace and Defense
- Healthcare
- Telecom and IT Infrastructure
- Other End-users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific dominated with 48.05% Surface Mount Technology market share in 2025 and is forecast to post an 8.12% CAGR through 2031. China, Taiwan, and South Korea together are slated to invest more than USD 84 billion in new 300 mm fabs by 2027, securing upstream substrate and component capacity. Japan's Kumamoto cluster, anchored by TSMC JASM's USD 20 billion expansion, adds over 100,000 12-inch wafers per month while creating 3,400 high-tech roles.
North America trails but is accelerating under the CHIPS Act, with announced projects doubling regional capacity investment from USD 12 billion in 2024 to USD 24.7 billion by 2027. Advanced packaging pilots in Arizona and New York target sub-10 µm placement for AI accelerators, reducing dependence on trans-Pacific shipping lanes. Regulatory emphasis on cyber-secure production flows nudges factories toward CMMC and IPC-1791 trusted builder accreditation.
Europe focuses on automotive power semiconductors and wide-band-gap devices, with Infineon and STMicroelectronics driving capital expenditure to support 800 V EV inverters. The region's RoHS expansion and incoming Ecodesign rules favor repairable PCBs, stimulating demand for selective soldering and rework platforms. Workforce upskilling programs under Europe's Pact for Skills align with IPC's certified interconnect designer curriculum, aiming to close a 146,000-worker gap by 2029.
Middle East and Africa makes incremental gains as Saudi Arabia and the UAE funnel sovereign-fund capital into tech parks that bundle EMS incentives with reduced utility tariffs. South Africa's Gauteng hub attracts telecom-equipment refurbishers that rely on modular SMT lines to process short-run, high-mix repair orders. Still, infrastructure gaps and limited specialist labor temper adoption of cutting-edge equipment in most sub-Saharan markets.
- ASMPT Limited
- Fuji Corporation
- Yamaha Motor Co., Ltd. (SMT Division)
- Panasonic Holdings Corporation (Panasonic Smart Factory Solutions)
- Hanwha Precision Machinery Co., Ltd.
- Mycronic AB
- Juki Corporation
- Nordson Corporation
- Koh Young Technology Inc.
- Saki Corporation
- Test Research, Inc. (TRI)
- Viscom SE
- Europlacer Holdings Ltd.
- Shenzhen JT Automation Equipment Co., Ltd.
- Rehm Thermal Systems GmbH
- Heller Industries, Inc.
- MIRTEC Co., Ltd.
- Shenzhen NEODEN Technology Co., Ltd.
- Shenzhen JAGUAR Automation Equipment Co., Ltd.
- Hanwa Precision Machinery Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of IoT and wearables driving high-density PCB demand
- 4.2.2 Automotive ADAS electronics adoption
- 4.2.3 Expansion of 5G infrastructure and high-frequency boards
- 4.2.4 System-in-Package (SiP) integration in smartphones
- 4.2.5 MicroLED display manufacturing requirements
- 4.2.6 OEM outsourcing to EMS firms in emerging economies
- 4.3 Market Restraints
- 4.3.1 High upfront capex for high-speed placement lines
- 4.3.2 Lead-free solder thermal constraints lowering yield
- 4.3.3 Semiconductor supply-chain volatility causing under-utilisation
- 4.3.4 Skilled labour shortage for AI-driven inspection systems
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Macroeconomic Trends Impact Analysis
5 Market Size and Growth Forecasts (Value)
- 5.1 By Component
- 5.1.1 Passive Components
- 5.1.1.1 Resistors
- 5.1.1.2 Capacitors
- 5.1.2 Active Components
- 5.1.2.1 Transistors
- 5.1.2.2 Integrated Circuits
- 5.1.1 Passive Components
- 5.2 By Equipment Type
- 5.2.1 Placement Equipment
- 5.2.1.1 High-speed Pick-and-Place Machines
- 5.2.2 Soldering Equipment
- 5.2.2.1 Reflow Ovens
- 5.2.2.2 Wave Solder Systems
- 5.2.3 Inspection Equipment
- 5.2.3.1 Automated Optical Inspection (AOI)
- 5.2.3.2 Solder Paste Inspection (SPI)
- 5.2.3.3 X-ray Inspection
- 5.2.4 Screen Printing Equipment
- 5.2.1 Placement Equipment
- 5.3 By Assembly Line Type
- 5.3.1 High-Mix / Low-Volume (HMLV)
- 5.3.2 High-Volume / High-Mix (HVHM)
- 5.4 By End-user Industry
- 5.4.1 Consumer Electronics
- 5.4.2 Automotive
- 5.4.3 Industrial Electronics
- 5.4.4 Aerospace and Defense
- 5.4.5 Healthcare
- 5.4.6 Telecom and IT Infrastructure
- 5.4.7 Other End-users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 South Korea
- 5.5.3.4 India
- 5.5.3.5 Rest of Asia-Pacific
- 5.5.4 Middle East
- 5.5.4.1 Saudi Arabia
- 5.5.4.2 United Arab Emirates
- 5.5.4.3 Rest of Middle East
- 5.5.5 Africa
- 5.5.5.1 South Africa
- 5.5.5.2 Rest of Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ASMPT Limited
- 6.4.2 Fuji Corporation
- 6.4.3 Yamaha Motor Co., Ltd. (SMT Division)
- 6.4.4 Panasonic Holdings Corporation (Panasonic Smart Factory Solutions)
- 6.4.5 Hanwha Precision Machinery Co., Ltd.
- 6.4.6 Mycronic AB
- 6.4.7 Juki Corporation
- 6.4.8 Nordson Corporation
- 6.4.9 Koh Young Technology Inc.
- 6.4.10 Saki Corporation
- 6.4.11 Test Research, Inc. (TRI)
- 6.4.12 Viscom SE
- 6.4.13 Europlacer Holdings Ltd.
- 6.4.14 Shenzhen JT Automation Equipment Co., Ltd.
- 6.4.15 Rehm Thermal Systems GmbH
- 6.4.16 Heller Industries, Inc.
- 6.4.17 MIRTEC Co., Ltd.
- 6.4.18 Shenzhen NEODEN Technology Co., Ltd.
- 6.4.19 Shenzhen JAGUAR Automation Equipment Co., Ltd.
- 6.4.20 Hanwa Precision Machinery Co., Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment