

|
시장보고서
상품코드
2124580
커넥티드 약물전달 기기 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Connected Drug Delivery Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
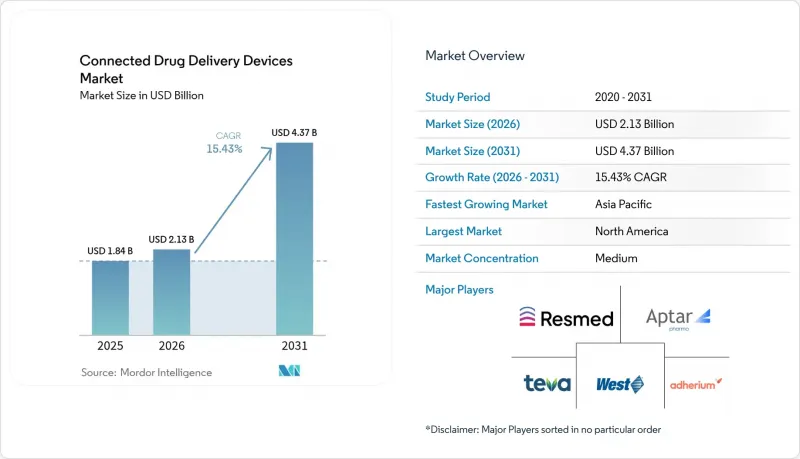
에 의하면, 커넥티드 약물전달 기기 시장 규모는 2025년에 18억 4,000만 달러로 평가되었습니다. 2026년에 21억 3,000만 달러에 달하고, 2031년까지 43억 7,000만 달러에 이를 것으로 예측되며, 2026년부터 2031년에 걸쳐 CAGR 15.43%로 성장할 전망입니다.
본 보고서는 제품 유형(연결형 센서 등), 기기 유형(흡입기 등), 기술(블루투스, NFC 등), 투여 경로(흡입, 주사),치료 용도(천식·COPD 등), 최종 사용자(재택 간호 환경 등), 지역(북미, 유럽 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 커넥티드 약물전달 기기 시장 동향 및 인사이트
블루투스 통합 비용의 감소
대만 반도체 제조 회사(TSMC)가 생산을 5나노미터 공정으로 전환하여 트랜지스터 밀도를 2배로 높이고 전력 소비를 줄인 결과, 블루투스 저에너지(BLE) 칩셋의 단가는 2025년에 1개당 0.42달러까지 하락했습니다. 그 후, 독일과 영국의 병원에서는 복약 순응도 데이터가 포괄 지불 제도에서 벌금을 피하는 데 도움이 된다는 점을 고려하여 커넥티드 주사기를 첫 번째 선택으로 채택했습니다. Nordic Semiconductor는 2025년에 1억 8,000만 개의 의료용 SoC를 출하하여 2024년 대비 64% 증가했습니다. 이에 따라 중소규모의 기기 제조업체들은 개발 주기를 9개월로 단축할 수 있는 턴키 모듈을 활용할 수 있게 되었습니다. 가격의 급락으로 인해 비용이 더 이상 장벽이 되지 않게 되었으며, 제네릭 제조업체들은 부품 원가(BOM) 상한선인 2달러를 초과하지 않고도 펜형 주사기에 무선 통신 기능을 탑재할 수 있게 되었습니다. 단위당 경제성이 수렴됨에 따라, 조달 부서는 현재 연결 기능을 프리미엄 기능이 아닌 표준 기능으로 취급하게 되었으며, 이에 따라 커넥티드 약물전달 기기의 목표 시장이 확대되고 있습니다.
가치 기반 의료 보상 모델로의 전환
메디케어·메디케이드 서비스 센터(CMS)는 2025년 1월부터 만성 질환 관리 수당을 수급자 1인당 월 63달러로 인상하고, 원격으로 약물 복용 준수 상황을 모니터링하는 것을 명확히 평가하기 시작했습니다. 유나이티드헬스케어와 앤섬은 중증 천식 환자에 대한 생물학적 제제 단계적 전환을 승인하기 전에 객관적인 흡입기 데이터 제출을 의무화하고 있으며, 이는 120만 명의 가입자에게 영향을 미치고 있습니다. 영국 국민보건서비스(NHS)는 환자가 처방된 용량의 최소 80%에 대한 펜형 주사기 데이터를 업로드하지 않을 경우, 당뇨병 치료제 환급액의 15%를 보류하고 있습니다. 이에 이어 일본도 2025년 10월, 만성폐쇄성폐질환(COPD)의 복약 순응도에 관한 단계적 보상 제도를 도입했습니다. 이러한 의무화 조치는 복약 순응도 미달에 대해 벌금을 부과함으로써 인센티브를 전환하고, 커넥티드 약물전달 기기 시장 전반에 걸친 도입을 가속화하고 있습니다.
사이버 보안 및 데이터 개인정보 보호 관련 규정 준수 부담
2025년 10월에 발효된 FDA의 시판 후 지침에 따라 제조업체는 소프트웨어 BOM(부품 목록)을 공개하고 30일 이내에 취약점을 수정해야 하며, 중견 기업에는 연간 약 120만 달러의 추가 비용이 발생합니다. 2025년 의료기기 제조업체에 부과된 GDPR(EU 개인정보보호규정)에 따른 벌금은 1,400만 유로에 달하고, 2024년 대비 40% 증가했으나, 그 대부분은 암호화되지 않은 투여량 데이터가 원인입니다. HIPAA에서는 투여 기록을 로컬에 저장하는 의료기기를 ‘대상 기관’으로 분류하고 있으며, 과거에는 전자 건강 기록(EHR) 시스템에만 적용되던 감사가 대상 범위로 확대되고 있습니다. 규정 준수 대응으로 인해 인슬렛(Inslet)사의 2025년도 연구개발(R&D) 예산의 18%가 소모되어, 신기능 개발에 할당될 자원이 줄어들었습니다. 규제 의무가 증가함에 따라 커넥티드 약물전달 기기 시장에서는 통합 움직임이 가속화되고 있으며, 소규모 사업자들은 법적 비용을 상쇄하기 위해 규모 확대를 도모하고 있습니다.
부문별 분석
2025년에는 통합형 커넥티드 기기가 매출의 58.12%를 차지했지만, 커넥티드 센서는 연평균 성장률(CAGR) 17.96%로 성장하고 있습니다. 후속 장착이 가능한 클립온형 설계 덕분에 제약 파트너는 12개월 이내에 기존 주사기를 업그레이드할 수 있지만, 통합형 플랫폼의 경우 새로운 금형 제작에 36개월이 소요됩니다. 프로펠러 헬스(Propeller Health)의 정량 흡입기용 센서는 설비 투자를 피할 수 있다는 점 덕분에, 2025년 미국에서 14개 보험 플랜의 처방약 목록에 등재되었습니다. 바이오코프(Biocorp)의 ‘말리야(Malliya)’는 복약 누락 감지 정확도 92%를 달성하여 사노피(Sanofi)를 설득해 프랑스에서 ‘란타스(Lantus)’와의 번들 판매를 실현했습니다. 통합형 유닛은 카트리지의 정기적인 교체와 소프트웨어 구독을 통해 프리미엄 비즈니스 모델을 유지하고 있습니다. 탠덤 디아베티스의 슬림한 X2 펌프는 덱스콤의 CGM을 통합하여 2025년에는 미국 자동 인슐린 투여 사용자의 68%를 확보했습니다. 따라서 커넥티드 약물전달 기기 시장은 고부가가치의 통합형 생태계와 비용 효율이 뛰어난 센서 개조로 양분되어 있습니다.
웨어러블 주사기는 생물학적 제제의 투여량이 주사기 용량을 초과함에 따라 전체 기기 중 가장 빠른 연평균 성장률(CAGR) 18.48%로 성장을 지속하고 있습니다. Enable Injections의 ‘enFuse’는 2025년에 FDA 승인을 받은 적응증을 6개 추가하여, 암 치료를 1회당 3,000달러의 정맥 주사 치료에서 400달러의 가정용 패치로 전환시켰습니다. 인슐린과 GLP-1의 투여량이 여전히 1밀리리터 미만으로 유지되고 있기 때문에 프리필드 주사기는 여전히 커넥티드 약물전달 기기 시장의 38.05% 점유율을 차지하며 시장을 독점하고 있습니다. 그러나 앰젠(Amgen)은 2025년에 ‘레파타(Repatha)’ 처방량의 40%를 3.5mL 웨어러블 기기로 전환했습니다. 벡톤 디킨슨 앤 컴퍼니(Becton, Dickinson & Company)의 재사용 가능한 ‘리베르타스(Libertas)’ 플랫폼은 지속가능성 요건을 충족하며, 이미 류마티스 관절염 환자들 사이에서 34%의 채택률을 보이고 있습니다. 폼 팩터의 다양화로 선택의 폭이 넓어지면서 시장 침투가 심화되고 있습니다.
지역별 분석
북미는 메디케어(Medicare)의 보험 적용, 높은 기기 보급률, 그리고 FDA의 벤치마크로서의 지위에 힘입어 2025년 매출의 36.78%를 차지했습니다. 포화 상태에 가까워짐에 따라 성장률은 연평균 성장률(CAGR) 13.8%로 둔화되겠지만, 이 지역은 상호 승인 협정에 따라 전 세계 승인 절차를 주도하고 있습니다. 아시아태평양은 중국이 1억 8,000만 명의 환자를 대상으로 흡입기 데이터 업로드를 보험 적용 대상으로 하고, 인도가 인슐린 펜 사용 기록을 국민 건강 ID에 통합하고 있는 점에 힘입어 연평균 성장률(CAGR) 21.41%로 성장을 주도하고 있습니다. 일본의 ‘사키가케’ 제도에서는 2025년에 9유형의 커넥티드 펜이 승인되었으며, 호주에서는 원격의료의 보험 적용을 커넥티드 기기 사용과 연계하고 있습니다.
20개 법역에 걸친 다양한 규제로 인해 규정 준수(컴플라이언스)의 복잡성이 증가하고 있으며, 현지 전문 지식을 갖춘 다국적 기업이 우위를 점하고 있습니다. 전반적으로 지역별 정책 차이는 커넥티드 약물전달 기기 시장에서 판매 및 규제 관련 자원의 전략적 배분에 영향을 미치고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the connected drug delivery devices market size is projected to be USD 1.84 billion in 2025, USD 2.13 billion in 2026, and reach USD 4.37 billion by 2031, growing at a CAGR of 15.43% from 2026 to 2031.
This report is Segmented by Product Type (Connected Sensors, and More), Device Type (Inhalers, and More), Technology (Bluetooth, NFC, and More), Route of Administration (Inhalational, Injectable), Therapeutic Application (Asthma & COPD, and More), End User (Home Care Settings, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Connected Drug Delivery Devices Market Trends and Insights
Bluetooth Integration Cost Deflation
Bluetooth Low Energy chipsets fell to USD 0.42 per unit in 2025 after Taiwan Semiconductor Manufacturing Company shifted production to 5-nanometer nodes, doubling transistor density and reducing power draw. Hospitals in Germany and the United Kingdom subsequently listed connected injectors as first-line options because adherence data helps avoid bundled-payment penalties. Nordic Semiconductor shipped 180 million medical-grade SoCs in 2025, a 64% jump over 2024, giving smaller device makers turnkey modules that cut development cycles to nine months. The price collapse removes cost as a gating factor, allowing generic manufacturers to embed radios in pen injectors without exceeding a USD 2 bill-of-materials ceiling. As unit economics converge, procurement teams now treat connectivity as standard rather than a premium, broadening the addressable market for connected drug delivery devices.
Shift to Value-Based Care Reimbursement Models
The Centers for Medicare & Medicaid Services lifted its Chronic Care Management stipend to USD 63 per beneficiary per month in January 2025, explicitly rewarding remote adherence monitoring.UnitedHealthcare and Anthem insist on objective inhaler data before approving biologic step-ups for severe asthma, affecting 1.2 million members. England's National Health Service withholds 15% of diabetes-drug reimbursement if patients fail to upload pen-injector data at least 80% of prescribed doses. Japan followed with a COPD adherence tier in October 2025. These mandates flip incentives by penalizing non-adherence, accelerating adoption throughout the Connected drug delivery devices market.
Cyber-Security & Data-Privacy Compliance Burden
FDA's post-market guidance, effective October 2025, compels manufacturers to publish software bills of materials and close vulnerabilities within 30 days, adding an estimated USD 1.2 million in annual costs for mid-size firms. GDPR fines on device makers hit EUR 14 million in 2025, up 40% over 2024, mostly for unencrypted dose data. HIPAA classifies devices that locally store dosing logs as covered entities, bringing audits that once applied only to EHR systems. Compliance drained 18% of Insulet's 2025 R&D budget, diverting resources from new features. Rising obligations are putting pressure on consolidation in the Connected drug delivery devices market, as smaller players seek scale to amortize legal overheads.
Other drivers and restraints analyzed in the detailed report include:
- Post-COVID Telehealth Normalization
- Regulatory Fast-Track Pathways for SaMD-Drug Combination Products
- Single-Use Electronics-Waste Regulations Tightening
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Connected Sensors are climbing at a 17.96% CAGR, even though integrated connected devices retained 58.12% revenue in 2025. Retrofit clip-on designs let pharmaceutical partners upgrade legacy injectors within 12 months, whereas integrated platforms need 36 months for new tooling. Propeller Health's metered-dose inhaler sensor earned formulary status with 14 U.S. plans in 2025 because it avoided capital expense. Biocorp's Mallya achieved 92% accuracy in detecting missed doses, convincing Sanofi to bundle it with Lantus in France. Integrated units preserve a premium business model through recurring cartridges and software subscriptions. Tandem Diabetes's slim X2 pump integrated Dexcom CGM and secured 68% of U.S. automated insulin delivery users in 2025. The Connected drug delivery devices market, therefore, splits between high-value integrated ecosystems and cost-efficient sensor retrofits.
Wearable Injectors register an 18.48% CAGR, fastest across devices, as biologic volumes rise beyond syringe capacity. Enable Injections' enFuse gained six new FDA-approved indications in 2025, shifting oncology care from USD 3,000 infusion sessions to USD 400 at-home patches. Prefilled Syringes still dominate the connected drug delivery devices market, with a 38.05% share, because insulin and GLP-1 doses remain below 1 milliliter. Yet Amgen moved 40% of Repatha scripts to a 3.5 mL wearable in 2025. Becton, Dickinson and Company's reusable Libertas platform targets sustainability mandates and already shows 34% adoption among rheumatoid arthritis patients. Form-factor diversification widens choice and deepens market reach.
Complete Report Scope:
- By Product Type
- Connected Sensors
- Integrated Connected Devices
- By Device Type
- Inhalers
- Pen & Auto-Injectors
- Prefilled Syringes
- Wearable Injectors
- Others
- By Technology
- Bluetooth
- NFC
- Cellular / LPWAN
- Other
- By Route of Administration
- Inhalational
- Injectable
- By Therapeutic Application
- Asthma & COPD
- Diabetes
- Cardiovascular Disorders
- Autoimmune & Inflammatory Diseases
- Oncology
- Other
- By End User
- Home Care Settings
- Hospitals
- Clinics & Specialty Centers
- Other
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America controls 36.78% of 2025 revenue, buoyed by Medicare reimbursement, high device penetration, and FDA benchmark status. Growth moderates to 13.8% CAGR as saturation approaches, yet the region shapes global approval sequences under mutual recognition pacts. Asia-Pacific leads expansion at 21.41% CAGR as China reimburses inhaler data uploads for 180 million patients and India embeds insulin-pen logs in national health IDs. Japan's Sakigake scheme cleared nine connected pens in 2025, and Australia ties telehealth reimbursement to connected-device usage.
Diverse rules across 20 regimes raise compliance complexity, rewarding multinationals with local expertise. Overall, regional policy divergence shapes the strategic allocation of sales and regulatory resources in the connected drug delivery devices market.
- Adherium
- AptarGroup Inc.
- AstraZeneca
- Beckton Dickinson
- BEIGfoot Biomedical Inc.
- Biocorp
- Boehringer Ingelheim
- Eitan Medical
- Enable Injections Inc.
- GlaxoSmithKline
- Insulet
- Johnson & Johnson
- Medtronic
- Nemera
- Novartis
- Phillips-Medisize LLC
- Portal Instruments Inc.
- Propeller Health
- Sensirion
- Resmed
- Tandem Diabetes Care
- Teva Pharmaceutical Industries
- West Pharmaceutical Services
- Ypsomed
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Bluetooth Integration Cost Deflation
- 4.2.2 Shift To Value-Based Care Reimbursement Models
- 4.2.3 Post-COVID Telehealth Normalization
- 4.2.4 Regulatory Fast-Track Pathways for Samd-Drug Combination Products
- 4.2.5 Graphene-Based Sensor Miniaturization Breakthroughs
- 4.2.6 Battery-Free NFC Power-Scavenging Designs
- 4.3 Market Restraints
- 4.3.1 Cyber-Security & Data-Privacy Compliance Burden
- 4.3.2 Single-Use Electronics-Waste Regulations Tightening
- 4.3.3 Semiconductor-Grade MEMS Supply Shortages
- 4.3.4 Interoperability Hurdles with Fragmented EHR Standards
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Product Type
- 5.1.1 Connected Sensors
- 5.1.2 Integrated Connected Devices
- 5.2 By Device Type
- 5.2.1 Inhalers
- 5.2.2 Pen & Auto-Injectors
- 5.2.3 Prefilled Syringes
- 5.2.4 Wearable Injectors
- 5.2.5 Others
- 5.3 By Technology
- 5.3.1 Bluetooth
- 5.3.2 NFC
- 5.3.3 Cellular / LPWAN
- 5.3.4 Other
- 5.4 By Route of Administration
- 5.4.1 Inhalational
- 5.4.2 Injectable
- 5.5 By Therapeutic Application
- 5.5.1 Asthma & COPD
- 5.5.2 Diabetes
- 5.5.3 Cardiovascular Disorders
- 5.5.4 Autoimmune & Inflammatory Diseases
- 5.5.5 Oncology
- 5.5.6 Other
- 5.6 By End User
- 5.6.1 Home Care Settings
- 5.6.2 Hospitals
- 5.6.3 Clinics & Specialty Centers
- 5.6.4 Other
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 Australia
- 5.7.3.5 South Korea
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 Middle East & Africa
- 5.7.4.1 GCC
- 5.7.4.2 South Africa
- 5.7.4.3 Rest of Middle East & Africa
- 5.7.5 South America
- 5.7.5.1 Brazil
- 5.7.5.2 Argentina
- 5.7.5.3 Rest of South America
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 Adherium Limited
- 6.3.2 AptarGroup Inc.
- 6.3.3 AstraZeneca plc
- 6.3.4 Becton, Dickinson and Company
- 6.3.5 BEIGfoot Biomedical Inc.
- 6.3.6 BIOCORP
- 6.3.7 Boehringer Ingelheim International GmbH
- 6.3.8 Eitan Medical Ltd.
- 6.3.9 Enable Injections Inc.
- 6.3.10 GlaxoSmithKline plc
- 6.3.11 Insulet Corporation
- 6.3.12 Johnson & Johnson Services Inc.
- 6.3.13 Medtronic plc
- 6.3.14 Nemera
- 6.3.15 Novartis AG
- 6.3.16 Phillips-Medisize LLC
- 6.3.17 Portal Instruments Inc.
- 6.3.18 Propeller Health (ResMed Inc.)
- 6.3.19 Sensirion AG
- 6.3.20 Resmed Inc
- 6.3.21 Tandem Diabetes Care Inc.
- 6.3.22 Teva Pharmaceutical Industries Ltd.
- 6.3.23 West Pharmaceutical Services Inc.
- 6.3.24 Ypsomed AG
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


