

|
시장보고서
상품코드
2124585
포장 펌프 및 디스펜서 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Packaging Pumps and Dispensers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 포장 펌프 및 디스펜서 시장 규모는 2025년에 100억 3,000만 달러로 평가되었습니다. 2026년 105억 2,000만 달러에서 2031년까지 134억 3,000만 달러에 이를 것으로 추정되고 예측 기간(2026-2031년) CAGR은 5.01%를 나타낼 전망입니다.
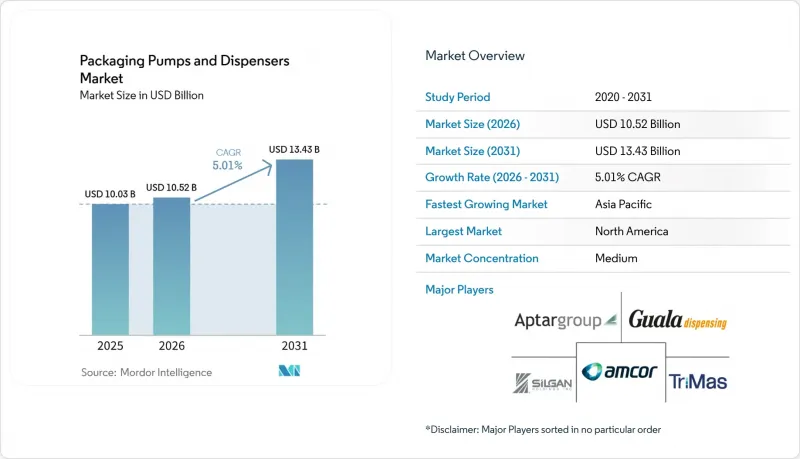
본 보고서는 제품 유형(로션·크림용 펌프, 스프레이·트리거 펌프, 폼 펌프, 에어리스 펌프 등), 소재 유형(플라스틱, 금속, 유리 등),용도(미용·퍼스널케어, 홈 케어 등), 유통 채널(슈퍼마켓 및 하이퍼마켓, 전문점 등), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 포장 펌프 및 디스펜서 시장 동향 및 인사이트
정량 디스펜싱 및 편의성이 높은 포장에 대한 수요 증가
정량 디스펜싱은 스킨케어, 의약품, 가정용 제품 분야에서 핵심적인 요건이 되고 있습니다. 이를 통해 제품의 낭비를 줄이고 보다 안정적인 사용이 가능해집니다. 이러한 요구는 특히 임상 현장 이외에서 사용되는 외용약이나 시판되는 비강용 제품에서 두드러집니다. 아프터(Aptar)사는 응급 의료, 주사 시스템 및 소비자용 헬스케어 솔루션을 바탕으로 2025년 의약품 부문 매출이 전년 대비 6% 증가한 17억 4,000만 달러에 달했다고 보고했습니다. 또한, 이 회사의 뷰티 부문에서도 헤어케어, 바디케어, 자외선 차단제를 포함한 퍼스널케어 분야에서 핵심 매출이 13% 증가했다고 보고되었습니다. 이러한 상황은 소비자가 사용하기 편리한 조작성과 의약품 등급의 디스펜싱 기술을 겸비한 공급업체에게 유리하게 작용하고 있습니다.
미용·퍼스널케어 제품의 프리미엄화
프리미엄 미용 제품에는 일관된 사용감, 외관, 성능을 갖춘 디스펜서가 요구됩니다. 에어리스 펌프, 맞춤형 향수 액추에이터, 리필 가능한 시스템은 기존 펌프보다 높은 부가가치를 지닙니다. 이러한 설계는 브랜드가 민감한 성분을 보호하고 차별화된 사용자 경험을 실현하는 데에도 도움이 됩니다. 실간(Silgan)은 위너 패키징(Wiener Packaging)의 통합 및 향수·미용 부문의 성장을 바탕으로, 2025년 디스펜싱 및 특수 캡 매출이 17% 증가한 27억 달러에 달했다고 보고했습니다. 아프터(Aptar)는 2025년에 BTY의 지분율을 80%로 높였으며, 크리스찬 디올(Christian Dior) 및 발렌티노(Valentino) 제품 출시를 위해 INUNE의 프리미엄 향수 펌프를 공급했습니다. 소규모 더모코스메틱 브랜드들도 맞춤형 액추에이터를 요구하고 있어, 이에 따라 신속한 금형 제작 및 장식 능력의 가치가 높아지고 있습니다.
변동이 심한 수지, 금속 및 부품 비용
표준 펌프 어셈블리의 재료 구성 대부분은 폴리프로필렌과 폴리에틸렌이 차지합니다. 이 가격들은 원유 및 나프타 가격 변동에 연동되기 때문에 소규모 제조업체에게는 관리가 어려울 수 있습니다. Aptar의 뷰티 부문 조정 후 EBITDA 마진은 관세, 공급업체공급 차질, 제조 효율 저하 및 제품 구성의 영향으로 2024년 13.0%에서 2025년 12.1%로 하락했습니다. 실간(Silgan)은 위너(Wiener)를 인수한 후, 유럽 내 대규모 제조 거점을 활용하여 비용 전가 체계를 지원했습니다. 대형 공급업체는 광범위한 공급망을 통해 조달 리스크를 분산시킬 수 있지만, 중소 제조업체는 설계 변경이나 규정 준수 대응에 필요한 자금이 부족한 경우가 있습니다. 또한, 정밀도를 희생할 수 없는 향수 및 의약품 분야에서는 스틸 스프링의 비용도 중요한 요소가 됩니다.
부문별 분석
2025년 기준, 로션 및 크림용 펌프는 포장 펌프 및 디스펜서 시장 점유율의 28.43%를 차지했습니다. 이러한 펌프는 샴푸, 바디 로션, 컨디셔너 및 대중용 스킨케어 제품에 널리 사용되고 있습니다. 이 펌프의 작동 특성은 적은 작동력으로 대량의 액체를 분사해야 하는 제품에 적합합니다. 프라이빗 브랜드와 가성비 브랜드에서는 계속해서 이러한 펌프를 표준 사양으로 채택하고 있습니다. 이러한 기존 도입 기반 덕분에 프리미엄 브랜드가 특수 시스템을 도입하더라도 안정적인 수요가 유지되고 있습니다.
에어리스 펌프는 2031년까지 연평균 성장률(CAGR) 5.78%를 나타낼 것으로 예측됩니다. 이들은 방부제를 사용하지 않는 스킨케어 제품, 임상용 더모코스메틱, 그리고 의약용 외용제에 사용되고 있습니다. 항산화 기능과 정확한 투여량은 이러한 용도에서 제품의 안정성에 대한 주장을 뒷받침합니다. ‘Magic One’은 싱글 엔진 컨셉을 통해 0.3ml에서 1ml까지의 토출량을 실현하며, PPWR을 준수하는 폴리올레핀 설계를 채택하고 있습니다. 스프레이 펌프와 트리거 펌프는 가정용 케어 제품에서 여전히 중요한 역할을 하고 있는 반면, 폼 펌프는 손 위생 제품 및 저자극성 세정 제품에 사용되고 있습니다. 산업용 및 외식 산업용 특수 캡은 소비자 제품 동향이 아닌 산업 생산량에 연동되어 추이를 보이고 있습니다.
2025년 시점에서 소재별로 살펴보면, 플라스틱은 포장 펌프 및 디스펜서 시장의 76.91% 점유율을 차지했습니다. 폴리프로필렌과 폴리에틸렌은 내화학성, 가공성 및 비용 효율성이 뛰어나기 때문에 폭넓은 용도로 사용되고 있습니다. 폴리프로필렌은 표준 로션용 펌프나 트리거 펌프에서 여전히 널리 사용되고 있습니다. 폴리에틸렌은 브랜드들이 재활용 가능성 인증을 요구하는 단일 소재 시스템에서의 사용이 증가하고 있습니다. 이러한 소재는 시스템 전체가 호환될 경우, 펌프가 재활용 설계 요건을 충족하는 데 도움이 됩니다.
금속 시장은 2031년까지 연평균 성장률(CAGR) 5.63%를 나타낼 것으로 전망됩니다. 고급 향수, 의약품 디스펜서, 고급 스킨케어 제품에서는 정밀도를 확보하고 제품의 외관을 향상시키기 위해 금속 부품이 사용되고 있습니다. 또한 고급스러운 촉감이나 구조적 강성이 중요시되는 경우에도 금속 부품이 채택되고 있습니다. 유리는 초고급 스킨케어 제품 및 의약품 포장에서 여전히 소규모의 점유율을 차지하고 있습니다. PVC는 EU의 PPWR 규정 하에서 규제 압력에 직면하고 있는 반면, PET는 식품 및 음료 캡에 제한적으로 사용되고 있습니다. 포장 펌프 및 디스펜서 업계에서는 플라스틱 제품 설계가 단일 소재인 폴리에틸렌이나 폴리프로필렌으로 전환되고 있으나, 메탈라이즈 가공이나 다층 구조 제품에 대해서는 2030년 이후 더 엄격한 요건이 부과될 전망입니다.
지역별 분석
2025년, 북미는 포장 펌프 및 디스펜서 시장의 29.56%를 차지했습니다. 고급 미용 제품의 보급, 확립된 소매 네트워크, 그리고 재활용 가능한 펌프의 조기 도입이 이 지역의 포장 펌프 및 디스펜서 시장 전체 수요를 뒷받침하고 있습니다. 이 지역 시장의 대부분은 미국이 차지하고 있지만, 캐나다와 멕시코도 조직화된 소매업 및 의약품 포장을 통해 수요를 끌어올리고 있습니다. 실건(Silgan)은 2026년 디스펜서 출하량 및 조정 후 EBIT가 2025년 수준을 상회할 것으로 전망하며, 디스펜서 사업 및 반려동물사료 사업의 성장을 위해 3억 1,000만 달러를 설비 투자할 계획입니다. 남미는 브라질이 중심을 이루고 있으며, 아프터(Aptar)사의 소마플라스트(Somaplast)사 인수가 경구 의약품 디스펜서 공급 능력 강화에 기여하고 있습니다.
유럽에서는 포장 펌프 및 디스펜서 시장에서 고급 화장품 및 의약품 포장 기반이 확립되어 있습니다. PPWR은 2026년 8월부터 적용되었으며, 공급업체에게는 재활용 가능성 증명이 요구됩니다. 독일, 프랑스, 영국, 이탈리아, 스페인은 포장 펌프 및 디스펜서의 주요 수요 시장입니다. 암콜(Amcor)은 독일 로네에서 ‘Magic One’ 라인의 가동을 시작했으며, 2027년 초에 첫 납품이 예상됩니다. 튀르키예, 사우디아라비아, 아랍에미리트(UAE)는 중동의 맞춤형 프리미엄 향수용 펌프 수요를 뒷받침하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 6.09%를 나타낼 것으로 예측되며, 이는 포장 펌프 및 디스펜서 시장에서 지역별 가장 높은 성장률입니다. 중국, 인도, 한국, 일본, 호주는 인구 규모에 더해 미용 및 퍼스널케어 제품 소비가 확대될 것으로 전망됩니다. 중국에서는 성분을 중시하는 미용 제품이 에어리스 방식의 보급을 촉진하고 있으며, 인도에서는 소매망 확대로 인해 지방 도시에서 펌프 제품의 첫 사용이 증가하고 있습니다. 한국 브랜드들은 향후 세계 제품 라인에도 채택될 가능성이 있는 듀얼 챔버 방식이나 에어리스 시스템을 도입하고 있으며, 아프리카의 경우 남아프리카공화국, 이집트, 나이지리아, 케냐에서 소비자들이 소포장 제품에서 펌프식 퍼스널케어 제품으로 전환함에 따라 수요가 초기 단계에 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the packaging pumps and dispensers market size was USD 10.03 billion in 2025 and is estimated to grow from USD 10.52 billion in 2026 to reach USD 13.43 billion by 2031, at a CAGR of 5.01% during the forecast period (2026-2031).
This report is Segmented by Product Type (Lotion and Cream Pumps, Spray and Trigger Pumps, Foam Pumps, Airless Pumps, and More), Material Type (Plastic, Metal, Glass, and More), Application (Beauty and Personal Care, Homecare, and More), Distribution Channel (Supermarkets and Hypermarkets, Specialty Stores, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Packaging Pumps and Dispensers Market Trends and Insights
Rising Demand for Controlled-Dose and Convenient Packaging
Controlled-dose dispensing has become a core requirement in skincare, pharmaceutical, and household applications. It reduces product waste and can provide more consistent use. The need is especially visible in topical medicines and over-the-counter nasal products used outside clinical settings. Aptar reported USD 1.74 billion in 2025 pharma sales, up 6%, supported by emergency medicine, injectable systems, and consumer healthcare solutions. Its beauty segment also reported 13% core sales growth in personal care, including hair, body, and sun care products. These conditions favor suppliers that can combine consumer-friendly operation with pharmaceutical-grade dispensing experience.
Premiumization of Beauty and Personal Care Products
Premium beauty products require dispensers with a consistent feel, appearance, and performance. Airless pumps, custom fragrance actuators, and refillable systems carry higher value than conventional pumps. These designs also help brands protect sensitive ingredients and support a differentiated user experience. Silgan reported USD 2.7 billion in 2025 dispensing and specialty closures sales, a 17% increase, following the integration of Weener Packaging and growth in the fragrance and beauty segments. Aptar increased its ownership of BTY to 80% in 2025 and supplied INUNE prestige fragrance pumps for the launches of Christian Dior and Valentino. Smaller dermocosmetics brands are also seeking customized actuators, which increases the value of rapid tooling and decoration capabilities.
Volatile Resin, Metal, and Component Costs
Polypropylene and polyethylene represent much of the material content in standard pump assemblies. Their prices follow crude oil and naphtha movements, which can be difficult for smaller manufacturers to manage. Aptar's beauty segment adjusted EBITDA margin declined to 12.1% in 2025 from 13.0% in 2024, due to tariffs, supplier disruptions, manufacturing inefficiencies, and product mix. Silgan used its larger European manufacturing base after the Weener acquisition to support cost pass-through arrangements. Larger suppliers can spread sourcing risk through broader supply networks, while smaller producers may have less capital for redesign and compliance work. Steel spring costs also matter in fragrance and pharmaceutical products, where precision cannot be reduced.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of Recyclable and Mono-Material Pump Systems
- E-Commerce Demand for Leak-Resistant and Lockable Dispensers
- Limited Recycling Infrastructure for Multi-Material Pump Assemblies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Lotion and cream pumps held 28.43% of the packaging pumps and dispensers market share in 2025. They are widely used for shampoos, body lotions, conditioners, and mass skin care products. Their operating profile suits products that need high-volume dispensing with low actuation force. Private-label and value brands continue to use these pumps as a standard format. This installed base supports stable demand even as premium brands add specialized systems.
Airless pumps are projected to grow at a CAGR of 5.78% through 2031. They are used in preservative-free skin care, clinical dermocosmetics, and pharmaceutical topicals. Oxidation protection and dose accuracy support product stability claims in these applications. Magic One provides outputs from 0.3 ml to 1 ml through a single-engine concept and uses a PPWR-aligned polyolefin design. Spray and trigger pumps remain important in home care, while foam pumps are used in hand hygiene and gentle cleansing products. Specialty closures for industrial and food-service uses follow industrial output rather than consumer-product trends.
Plastic held 76.91% of the packaging pumps and dispensers market share by material type in 2025. Polypropylene and polyethylene are used across a range of applications because they offer chemical resistance, processability, and cost-effectiveness. Polypropylene remains common in standard lotion and trigger pumps. Polyethylene is gaining use in mono-material systems where brands seek recyclability certification. These materials can help a pump meet design-for-recycling requirements when the overall system is compatible.
Metal is projected to grow at a CAGR of 5.63% through 2031. Premium fragrances, pharmaceutical dispensing, and luxury skin care use metal components to ensure precision and enhance product presentation. Metal components are also used where a premium tactile effect and structural rigidity are important. Glass retains a small position in ultra-premium skin care and pharmaceutical packaging. PVC faces regulatory pressure under EU PPWR rules, while PET has modest use in food and beverage closures. The packaging pumps and dispensers industry is moving plastic designs toward mono-material polyethylene and polypropylene, while metalized and multi-layer formats face tighter requirements from 2030.
Complete Report Scope:
- By Product Type
- Lotion and Cream Pumps
- Spray and Trigger Pumps
- Foam Pumps
- Airless Pumps
- Other Product Types
- By Material Type
- Plastic
- Polypropylene (PP)
- Polyethylene (PE)
- Polyethylene Terephthalate (PET)
- Polyvinyl Chloride (PVC)
- Other Plastics
- Metal
- Glass
- Other Material Types
- Plastic
- By Application
- Beauty and Personal Care
- Homecare
- Pharmaceuticals and Healthcare
- Food and Beverages
- Industrial and Automotive
- Other Applications
- By Distribution Channel
- Supermarkets and Hypermarkets
- Specialty Stores
- Online Stores and Marketplaces
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Kenya
- Rest of Africa
- North America
Geography Analysis
North America held 29.56% of the packaging pumps and dispensers market share in 2025. Premium beauty adoption, established retail networks, and early uptake of recyclable pumps support demand across the packaging pumps and dispensers market in the region. The United States accounts for much of the regional base, while Canada and Mexico add demand through organized retail and pharmaceutical packaging. Silgan expects 2026 dispensing volumes and adjusted EBIT to exceed 2025 levels, with USD 310 million in capital expenditure directed toward dispensing and pet food growth. South America is centered on Brazil, where Aptar's acquisition of Sommaplast supports oral pharmaceutical dispensing capabilities.
Europe has a large base of premium beauty and pharmaceutical packaging in the packaging pumps and dispensers market. The PPWR applies from August 2026 and requires suppliers to demonstrate recyclability. Germany, France, the United Kingdom, Italy, and Spain are the primary demand markets for packaging pumps and dispensers. Amcor is commissioning a Magic One line in Lohne, Germany, with first deliveries expected in early 2027. Turkey, Saudi Arabia, and the UAE support demand in the Middle East for customized premium fragrance pumps.
Asia-Pacific is projected to grow at a CAGR of 6.09% through 2031, the fastest regional rate in the packaging pumps and dispensers market. China, India, South Korea, Japan, and Australia combine population scale with expanding beauty and personal care consumption. China's ingredient-focused beauty products support airless formats, while India's retail expansion supports first-time pump use in lower-tier cities. South Korean brands use dual-chamber and airless systems that can later appear in global product lines, while Africa has early-stage demand in South Africa, Egypt, Nigeria, and Kenya as consumers move from sachets toward pump-dispensed personal care products.
- AptarGroup, Inc.
- Silgan Holdings Inc.
- Amcor plc
- TriMas Corporation
- Coster Tecnologie Speciali S.p.A.
- Guala Dispensing S.p.A.
- Frapak Packaging B.V.
- Mitani Valve Co., Ltd.
- Quadpack Industries
- Taplast S.p.A.
- Raepak Ltd.
- Afa Dispensing Group B.V.
- Zhejiang Sun-Rain Industrial Co., Ltd.
- Gerresheimer AG
- Precision Valve Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Controlled-Dose and Convenient Packaging
- 4.2.2 Premiumization of Beauty and Personal Care Products
- 4.2.3 Expansion of Liquid and Semi-Liquid Product Formats
- 4.2.4 Growth of Hygiene, Sanitizer, and Homecare Applications
- 4.2.5 Adoption of Recyclable and Mono-Material Pump Systems
- 4.2.6 E-Commerce Requirements for Leak-Resistant and Lockable Dispensers
- 4.3 Market Restraints
- 4.3.1 Volatile Resin, Metal, and Component Costs
- 4.3.2 High Tooling and Manufacturing Costs for Customized Pump Formats
- 4.3.3 Formulation Compatibility and Dose-Consistency Failures
- 4.3.4 Limited Recycling Infrastructure for Multi-Material Pump Assemblies
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Lotion and Cream Pumps
- 5.1.2 Spray and Trigger Pumps
- 5.1.3 Foam Pumps
- 5.1.4 Airless Pumps
- 5.1.5 Other Product Types
- 5.2 By Material Type
- 5.2.1 Plastic
- 5.2.1.1 Polypropylene (PP)
- 5.2.1.2 Polyethylene (PE)
- 5.2.1.3 Polyethylene Terephthalate (PET)
- 5.2.1.4 Polyvinyl Chloride (PVC)
- 5.2.1.5 Other Plastics
- 5.2.2 Metal
- 5.2.3 Glass
- 5.2.4 Other Material Types
- 5.2.1 Plastic
- 5.3 By Application
- 5.3.1 Beauty and Personal Care
- 5.3.2 Homecare
- 5.3.3 Pharmaceuticals and Healthcare
- 5.3.4 Food and Beverages
- 5.3.5 Industrial and Automotive
- 5.3.6 Other Applications
- 5.4 By Distribution Channel
- 5.4.1 Supermarkets and Hypermarkets
- 5.4.2 Specialty Stores
- 5.4.3 Online Stores and Marketplaces
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Colombia
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Egypt
- 5.5.6.3 Nigeria
- 5.5.6.4 Kenya
- 5.5.6.5 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 AptarGroup, Inc.
- 6.4.2 Silgan Holdings Inc.
- 6.4.3 Amcor plc
- 6.4.4 TriMas Corporation
- 6.4.5 Coster Tecnologie Speciali S.p.A.
- 6.4.6 Guala Dispensing S.p.A.
- 6.4.7 Frapak Packaging B.V.
- 6.4.8 Mitani Valve Co., Ltd.
- 6.4.9 Quadpack Industries
- 6.4.10 Taplast S.p.A.
- 6.4.11 Raepak Ltd.
- 6.4.12 Afa Dispensing Group B.V.
- 6.4.13 Zhejiang Sun-Rain Industrial Co., Ltd.
- 6.4.14 Gerresheimer AG
- 6.4.15 Precision Valve Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


