

|
시장보고서
상품코드
2124611
미국 및 유럽의 재사용 가능 플라스틱 회수식 운송용 포장재 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United States And Europe Reusable Plastic Returnable Transport Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
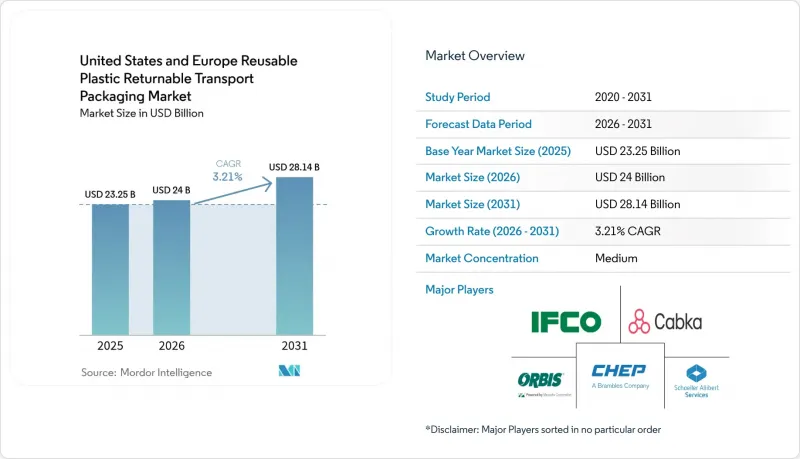
에 의하면, 2026년 미국 및 유럽의 재사용 가능 플라스틱 회수식 운송용 포장재 시장 규모는 240억 달러로 추정되고 2025년 232억 5,000만 달러에서 확대해, 2031년에는 281억 4,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 3.21%를 나타낼 것으로 전망됩니다.
본 보고서는 소재(HDPE, PP 등), 제품 유형(RPC, 팔레트,크레이트, IBC 등), 최종 사용자 산업(식품 및 음료, 자동차, 전자기기, 화학제품 등), 유통 모델(풀형, 캡티브형) 및 지역별로 분류되어 있으며, 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
미국 및 유럽의 재사용 가능 플라스틱 회수식 운송용 포장재 시장 동향 및 인사이트
순환형 포장에 관한 유리한 정부 규제
스페인의 왕령 제1055/2022호는 일회용 플라스틱에 대해 1kg당 0.45유로(1kg당 0.50달러)의 세금을 부과하고, 2030년까지 65%의 재사용을 의무화하고 있어, 이로 인해 컨테이너의 급속한 전환이 촉진되고 있습니다. 캘리포니아주 상원 법안 제54호는 2032년까지 일회용 제품 사용량을 25% 감축하도록 의무화하고 있으며, 이는 3조 6,000억 달러 규모의 캘리포니아주 경제 내 조달 활동에 영향을 미치고 있습니다. EU의 ‘포장 및 포장 폐기물 규정’은 2030년까지 운송용 포장의 재사용률을 10%로 높이는 목표를 설정하고 있어, 다국적 화주들의 투자를 촉진하고 있습니다. 미국 환경보호청(EPA)의 연방 조달 규정에서는 현재 재사용 가능한 대안이 우선시되고 있어, 공공 부문 계약업체들 수요가 확대되고 있습니다. 이러한 정책들은 종합적으로 재사용 가능 플라스틱 회수식 운송용 포장재 시장에 지속적인 호재를 가져오고 있습니다.
창고 및 물류 센터의 자동화가 RTP 보급을 가속화
자동화 창고 시스템에서는 RFID 태그가 부착된 표준화된 컨테이너가 선호되기 때문에 기업들은 재사용 가능한 컨테이너로 전환해야 하는 상황에 놓여 있습니다. 제너럴 모터스(GM)는 2024년에 15개 공장에서 컨테이너를 표준화한 결과, 자재 운반 비용을 23% 절감하는 데 성공했습니다. 컨테이너에 IoT 센서를 설치하는 것에 관한 IEEE의 지침 덕분에 자산 가시성이 98.5% 향상되어 무인 창고 운영이 가능해졌습니다. 1만개 이상의 SKU를 출하하는 멀티채널 풀필먼트 센터에서는 재사용 가능한 컨테이너를 사용함으로써 15-20%의 효율 향상이 보고되고 있습니다. 아마존의 풀필먼트 사례에서는 표준화된 토트를 사용함으로써 로봇의 처리 능력이 40% 향상되어, 자동화의 시너지 효과가 두드러지게 나타났습니다.
프로세스 변경에 대한 이해관계자의 저항
재사용 가능한 시스템으로의 전환에는 전사적인 조정이 필요하며, 공장에서는 6-18개월의 도입 기간 동안 일시적으로 8-12%의 생산성 저하를 겪는 경우가 많습니다. 많은 창고 관리 솔루션은 재사용 가능한 컨테이너 풀을 표준 기능으로 추적할 수 없기 때문에 비용이 많이 드는 업그레이드를 해야만 합니다. 중소기업은 풀 운영 사업자가 부과하는 최소 이용 수량 요건으로 인해 어려움을 겪고 있습니다. 또한 일회용 워크플로우에서는 익숙하지 않은 검사 및 반납 절차를 직원이 익혀야 하기 때문에 교육 비용도 도입의 걸림돌이 되고 있습니다. 중견 자동차 부품 공급업체는 재사용 컨테이너 도입을 위한 창고 개조 및 교육에 15만-30만 달러를 지출하고 있으며, 이는 전환 과정에서 직면하는 장벽이 얼마나 큰지를 잘 보여줍니다.
부문별 분석
HDPE는 재사용 가능 플라스틱 회수식 운송용 포장재 시장의 53.88%를 차지하고 있습니다. -40°C에서 +60°C 범위에서 입증된 내구성으로 인해 자동차 및 식품 물류 분야의 표준 선택지로 자리 잡고 있지만, 2024년에 18%에 달하는 가격 변동으로 인해 수명 주기 비용 차이에 대한 면밀한 검토가 요구되고 있습니다. 폴리프로필렌(PP)은 경량화와 엄격한 내화학성 요건을 배경으로 4.23%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 포드사는 2024년 엔진 부품용 캐리어를 PP로 전환함으로써 컨테이너 무게를 23% 줄였습니다. 재활용 소재 함유율 의무화는 HDPE에 유리하게 작용하고 있습니다. 이는 확립된 공급 경로를 통해 물성 저하 없이 25-30%의 함유율을 충족할 수 있기 때문이며, 이를 통해 사용자는 버진 수지 가격 변동 위험으로부터 보호받고 있습니다.
부차적인 동향으로는 의약품 라인에서 투명성 요구 사항이 높아지고 있는 점을 들 수 있으며, 이로 인해 폴리카보네이트가 입지를 다지고 있습니다. 은 이온을 이용한 항균성 의무화로 인해 수지 비용은 15-20% 상승하지만, 식품 접촉 관련 규제가 엄격해지는 가운데 사용자들은 다소 높은 가격을 수용하고 있습니다. 전반적으로, 소재 선정에 있어서는 더 이상 수지의 정가뿐만 아니라 1회당 총비용, 재활용 가능성 및 규정 준수가 중요시되고 있으며, HDPE가 주도권을 유지하는 한편, PP는 고성능 틈새 시장에서 점유율을 확대되고 있습니다.
2025년에는 팔레트가 해당 부문 매출의 37.74%를 차지하며, 여전히 소비재 유통의 기반을 이루었습니다. 표준화된 크기, 자동 운반 시스템과의 호환성, 그리고 전 세계적인 풀 네트워크의 보급이 그 지배적인 지위를 공고히 하고 있습니다. 팔레트와 관련된 재사용 가능 플라스틱 회수식 운송용 포장재 시장 규모는 산업 생산의 성장률을 상회하지 않고, 이와 비슷한 추세를 보일 것으로 예상되며, 이는 시장이 거의 포화 상태에 있음을 반영합니다.
중간 벌크 컨테이너(IBC)는 화학제품 및 식품 원료 화주들이 부식 및 중량 문제로 인해 강철 컨테이너 사용을 중단함에 따라 4.66%라는 가장 높은 연평균 성장률(CAGR)을 보이고 있습니다. 다우 케미칼(Dow Chemical)은 플라스틱 IBC로 전환함으로써 컨테이너 무게를 35% 줄이고, 2024년에는 연간 180만 유로(200만 달러)의 비용 절감을 실현했습니다. 유엔의 성능 시험 및 위험물 관련 규제는 인증을 받은 공급업체를 우대하고 있어, 신규 시장 진출기업에게는 진입 장벽이 높아지는 반면, 기존 기업에게는 프리미엄 가격 책정을 뒷받침하는 요인이 되고 있습니다. 토트와 크레이트는 전자상거래 자동화의 혜택을 계속 누리고 있지만, 팔레트나 IBC에 비해 규모는 여전히 작은 임베디드니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, United States and Europe reusable plastic returnable transport packaging market size in 2026 is estimated at USD 24 billion, growing from 2025 value of USD 23.25 billion with 2031 projections showing USD 28.14 billion, growing at 3.21% CAGR over 2026-2031.
This report is Segmented by Material (HDPE, PP and More), Product Type (RPCs, Pallets, Crates, Ibcs and More), End-User (Food and Beverage, Automotive, Electronics, Chemicals and More), Distribution Model (Pooled, Captive) and Geography the Market Forecasts are Provided in Terms of Value (USD).
United States And Europe Reusable Plastic Returnable Transport Packaging Market Trends and Insights
Favorable Governmental Regulations on Circular Packaging
Royal Decree 1055/2022 in Spain imposes a EUR 0.45 per kilogram (USD 0.50 per kilogram) tax on non-reusable plastic and mandates 65% reuse by 2030, prompting rapid container conversion. California's Senate Bill 54 requires a 25% cut in single-use formats by 2032, influencing procurement across the state's USD 3.6 trillion economy. The EU Packaging and Packaging Waste Regulation sets a 10% reuse goal for transport packaging by 2030, reinforcing investments by multinational shippers. Federal procurement rules under the U.S. Environmental Protection Agency now prioritize reusable options, expanding demand from public-sector contractors. Collectively, these policies supply a durable tailwind for the reusable plastic returnable transport packaging market.
Warehouse and Distribution-Center Automation Accelerating RTP Uptake
Automated storage and retrieval systems prefer uniform containers with RFID tags, pushing enterprises toward reusable units. General Motors achieved a 23% drop in material-handling expense after standardizing containers across 15 plants in 2024. IEEE guidelines for IoT sensor installation in containers have lifted 98.5% asset visibility, enabling lights-out warehouse shifts. Multichannel fulfillment centers that ship 10,000 SKUs or more have reported 15-20% efficiency gains from reusable container use. Amazon fulfillment case work shows 40% higher robotic throughput with standardized totes, underscoring automation's multiplier effect.
Stakeholder Resistance to Process Change
Switching to reusable systems requires cross-enterprise coordination, and plants often endure 8-12% temporary productivity dips during the 6-18-month ramp-up. Many warehouse-management solutions cannot natively track reusable pools, forcing costly upgrades. Small and midsized companies struggle with minimum-volume thresholds imposed by pooling operators. Training expenses further dampen adoption, as staff must learn inspection and return protocols unfamiliar in single-use workflows. Mid-tier automotive suppliers have spent USD 150,000-300,000 on warehouse retrofits and training for reusable rollouts, illustrating the transition hurdle
Other drivers and restraints analyzed in the detailed report include:
- E-Grocery and Meal-Kit Boom Driving Crate Demand
- ESG-Linked Retailer Financing Programs
- Competition from Fibre-Based Alternatives
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
HDPE accounts for 53.88% of the reusable plastic returnable transport packaging market. Its proven ruggedness across -40 °C to +60 °C keeps it the default for automotive and food logistics, even as price swings of 18% in 2024 triggered scrutiny of lifecycle cost spreads. Polypropylene claims the fastest 4.23% CAGR on the back of lightweighting and tight chemical-resistance needs. Ford cut container weight 23% by switching engine-part carriers to PP in 2024. Recycled-content mandates tilt in HDPE's favor because established streams can meet 25-30% content without property loss, shielding users from virgin-resin volatility.
Second-order trends include rising clarity requirements for pharmaceutical lines that give polycarbonate a toehold. Silver-ion antimicrobial mandates lift resin costs by 15-20%, yet users accept premiums when food-contact rules tighten. Overall, material choice now weighs total-cost-per-trip, recyclability, and regulatory compliance rather than resin sticker price alone, ensuring HDPE retains leadership while PP builds share in high-performance niches.
Pallets supplied 37.74% of sector revenue in 2025 and remain the bedrock of fast-moving consumer goods flows. Standard footprint, automated handling compatibility, and global pooling coverage cement their dominant position. The reusable plastic returnable transport packaging market size tied to pallets will keep pace with industrial-production growth rather than outpace it, reflecting a near-saturation environment.
Intermediate bulk containers show the highest 4.66% CAGR as chemical and food-ingredient shippers abandon steel due to corrosion and weight. Dow Chemical trimmed container mass by 35% and saved EUR 1.8 million (USD 2.0 million) annually in 2024 after switching to plastic IBCs. UN performance tests and hazardous-goods mandates favor certified suppliers, raising barriers for late entrants but supporting premium pricing for incumbents. Totes and crates continue to benefit from e-commerce automation but remain subscale relative to pallets and IBCs.
Complete Report Scope:
- By Material
- High-Density Polyethylene
- Polypropylene
- Other Materials
- By Product Type
- Reusable Plastic Containers (RPCs)
- Pallets
- Crates and Totes
- Intermediate Bulk Containers (IBCs)
- Other Product Types
- By End-User Industry
- Food and Beverage
- Automotive
- Consumer Durables and Electronics
- Industrial and Chemicals
- Other End-user Industries
- By Distribution Model
- Pooled / Rental
- Captive Ownership
- By Geography
- United States
- Europe
- United Kingdom
- Germany
- France
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- IFCO Systems N.V.
- Brambles Limited (CHEP)
- Schoeller Allibert Services B.V.
- Orbis Corporation (Menasha Corporation)
- CABKA N.V.
- SSI Schaefer Systems International GmbH
- Rehrig Pacific Company
- Tosca Services LLC
- RPP Containers Inc.
- Corplex SAS
- Friedola TECH GmbH (Con-Pearl)
- Friedola TECH GmbH (Con-Pearl)
- Sohner Plastics LLC
- Conteyor NV
- KTP Kunststoff-Palettentechnik GmbH
- Wellplast AB
- AUER Packaging GmbH
- W.I. Sales Co. Inc.
- Wisechmann GmbH
- DW Reusables NV
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Favourable governmental regulations on circular packaging
- 4.2.2 Warehouse and DC automation accelerating RTP uptake
- 4.2.3 E-grocery and meal-kit boom driving crate demand
- 4.2.4 ESG-linked retailer financing programmes
- 4.2.5 AI-enabled asset-tracking reduces shrinkage
- 4.2.6 Scope-3-emission disclosure mandates
- 4.3 Market Restraints
- 4.3.1 Stakeholder resistance to process change
- 4.3.2 Competition from fibre-based alternatives
- 4.3.3 Reverse-logistics labour shortages
- 4.3.4 Antimicrobial compliance cost escalation
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
- 4.8 The Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material
- 5.1.1 High-Density Polyethylene
- 5.1.2 Polypropylene
- 5.1.3 Other Materials
- 5.2 By Product Type
- 5.2.1 Reusable Plastic Containers (RPCs)
- 5.2.2 Pallets
- 5.2.3 Crates and Totes
- 5.2.4 Intermediate Bulk Containers (IBCs)
- 5.2.5 Other Product Types
- 5.3 By End-User Industry
- 5.3.1 Food and Beverage
- 5.3.2 Automotive
- 5.3.3 Consumer Durables and Electronics
- 5.3.4 Industrial and Chemicals
- 5.3.5 Other End-user Industries
- 5.4 By Distribution Model
- 5.4.1 Pooled / Rental
- 5.4.2 Captive Ownership
- 5.5 By Geography
- 5.5.1 United States
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Spain
- 5.5.2.5 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Share, Products and Services, Recent Developments)
- 6.4.1 IFCO Systems N.V.
- 6.4.2 Brambles Limited (CHEP)
- 6.4.3 Schoeller Allibert Services B.V.
- 6.4.4 Orbis Corporation (Menasha Corporation)
- 6.4.5 CABKA N.V.
- 6.4.6 SSI Schaefer Systems International GmbH
- 6.4.7 Rehrig Pacific Company
- 6.4.8 Tosca Services LLC
- 6.4.9 RPP Containers Inc.
- 6.4.10 Corplex SAS
- 6.4.11 Friedola TECH GmbH (Con-Pearl)
- 6.4.12 Friedola TECH GmbH (Con-Pearl)
- 6.4.13 Sohner Plastics LLC
- 6.4.14 Conteyor NV
- 6.4.15 KTP Kunststoff-Palettentechnik GmbH
- 6.4.16 Wellplast AB
- 6.4.17 AUER Packaging GmbH
- 6.4.18 W.I. Sales Co. Inc.
- 6.4.19 Wisechmann GmbH
- 6.4.20 DW Reusables NV
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


