

|
시장보고서
상품코드
2124628
5G IoT : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)5G IoT - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
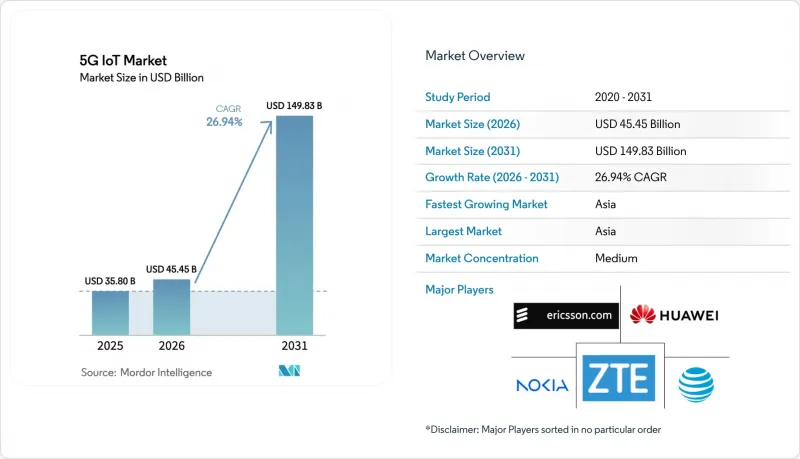
에 의하면, 5G IoT 시장 규모는 2025년에 358억 달러로 평가되었습니다. 2026년 454억 5,000만 달러에서 2031년까지 1,498억 3,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 26.94%를 나타낼 전망입니다.
본 보고서는 기술별(초고신뢰성 저지연 통신(URLLC), 저전력 광역 네트워크(LPWAN)), 최종 사용자 산업별(제조, 공급망·물류, 의료, 소매, 스마트시티·인프라, 자동차 및 운송), 지역별로 분류되어 있습니다.
세계의 5G IoT 시장 동향 및 인사이트
RedCap의 도입을 통한 방대한 디바이스 밀도 실현
릴리스 17의 RedCap은 피크 데이터 전송 속도를 250 Mbps로 제한하고, 보다 단순한 안테나 아키텍처를 채택함으로써 모듈 비용을 30-40% 절감하고 있습니다. 수년에 걸친 배터리 수명은 산업 자동화, 스마트 계량, 도시 전체의 센싱에 적합하며, 하위 호환성을 통해 전국적인 커버리지가 유지됩니다.
통신 사업자의 클라우드 및 네트워크 API를 통한 수익화 전략
클라우드 네이티브 5G 코어를 통해 통신 사업자는 API를 통해 서비스 품질(QoS), 위치 정보, 슬라이싱 기능을 제공할 수 있게 됩니다. 기업은 결정론적 성능에 대해 추가 요금을 지불하므로, 막대한 주파수 대역 및 인프라 투자를 상쇄할 수 있는 서비스 수익이 창출됩니다.
2달러 미만의 디바이스 등급에는 4G/LPWAN으로 충분
많은 저가형 센서는 하루에 몇 킬로바이트밖에 전송하지 않습니다. LTE Cat-1이나 NB-IoT는 모듈 비용을 절반으로 줄이면서도 이미 이러한 요구를 충족시키고 있습니다. 따라서 지방의 유틸리티체나 농업 기술 기업들은 가격이 제공하는 가치에 상응할 때까지 5G로의 업그레이드를 미루고 있습니다.
부문별 분석
LPWAN(5G RedCap)은 2025년에 5G 시장의 53.00%를 차지했으며, 이는 비용과 네트워크 기능 간의 최적의 균형을 반영합니다. URLLC는 규모는 작지만, 공장이나 자율주행차가 1밀리초 미만의 지연을 요구함에 따라 연평균 성장률(CAGR) 40.63%를 나타낼 것으로 예측됩니다. 2027년까지 모듈 가격이 4달러 수준으로 하락함에 따라, LPWAN 기기를 위한 5G IoT 시장 규모는 크게 확대될 것으로 예측됩니다. 기업들은 5G 하드웨어의 전체 비용을 부담하지 않고도 네트워크 슬라이싱을 활용하기 위해 자산 추적 및 환경 모니터링 워크로드를 LTE Cat-1에서 RedCap으로 이전하고 있습니다. 한편, 로봇 용접이나 원격 수술과 같은 분야에서는 URLLC의 프리미엄 가격이 정당화되어 특수 칩셋의 혁신을 주도하고 있습니다.
URLLC 이용 사례에서는 프라이빗 5G 네트워크 내의 엣지 컴퓨팅 노드와 결합되는 경우가 많으며, 결정론적인 유선 이더넷을 대체하고 있습니다. 아우디가 프레스 공장에 도입한 사례에서는 사이클 타임이 개선되고 가동 중단 시간이 단축되어 비즈니스 사례의 유효성이 입증되었습니다. 각 부품 공급업체들은 패킷 전달을 보장하는 타임-센시티브 네트워킹 기능이나 FEC 방식으로 경쟁하며, 대역폭 지표를 넘어선 차별화를 꾀하고 있습니다. 요컨대, 5G IoT 시장에서의 기술 선택은 획일적인 로드맵이 아닌, 개별적인 지연 시간, 전력 소비, 비용 제약에 맞추어 이루어지고 있습니다.
지역별 분석
아시아태평양은 5G IoT 시장을 주도하고 있으며, 통신 사업자의 설비 투자와 정책적 인센티브에 힘입어 2025년에는 중국이 매출의 41.25%를 차지했습니다. 차이나 유니콤(China Unicom)은 2025년 말까지 300개 도시에서 5G-Advanced의 커버리지를 확대할 계획이며, 이를 통해 대규모 머신 유형 통신 용량이 추가되고 네트워크 이용률이 향상될 전망입니다. 현지 시스템 통합사업자들은 철강, 섬유, 전자 산업의 생산 라인을 개조하고, 사설 네트워크에 대한 노하우를 확산시키고 있습니다. 인도는 RedCap사의 5달러 미만 모듈이 중소기업의 예산에 부합하기 때문에 2031년까지 지역별 연평균 성장률(CAGR)이 34.95%로 가장 높은 성장세를 보이고 있습니다. ‘디지털 인디아’ 및 ‘메이크 인 인디아’와 같은 정부 프로그램에 따라 주파수 대역 임대 규제가 완화되면서, 제약, 자동차, 에너지 분야의 캠퍼스 전체에 걸친 구축이 가속화되고 있습니다.
북미에서는 ‘CHIPS 법’의 보조금을 바탕으로 반도체 팹 및 국방 거점에서의 사설 네트워크 시범 도입이 우선적으로 진행되고 있습니다. 미시간주에서 텍사스주에 이르는 자동차 산업 회랑에서는 도로변의 V2X 장치와 공장 내의 URLLC 링크가 도입되어, 고대역폭·저지연 서비스의 투자 대비 효과가 입증되고 있습니다. 클라우드 하이퍼스케일러는 통신 사업자와 제휴하여, 기업이 코드를 통해 경로를 설정할 수 있는 네트워크 API를 제공함으로써 서비스 가동까지의 주기를 수개월에서 수분으로 단축하고 있습니다. 이 플랫폼의 역동성 덕분에 5G IoT 시장은 단순한 연결성을 넘어 애플리케이션 호스팅 영역으로 확대되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the 5G IoT market size was valued at USD 35.80 billion in 2025 and estimated to grow from USD 45.45 billion in 2026 to reach USD 149.83 billion by 2031, at a CAGR of 26.94% during the forecast period (2026-2031).
This report is Segmented by Technology (Ultra-Reliable Low-Latency Communications (URLLC), Low-Power Wide-Area Network (LPWAN)), End-User Industry (Manufacturing, Supply Chain and Logistics, Healthcare, Retail, Smart Cities and Infrastructure, Automotive and Transportation), and Geography
Global 5G IoT Market Trends and Insights
Massive device-density enablement after RedCap roll-out
Release 17 RedCap limits peak data rates to 250 Mbps and employs simpler antenna architectures, trimming module costs by 30-40%. Multi-year battery life aligns with industrial automation, smart metering, and city-wide sensing, while backward compatibility maintains nationwide coverage.
Telco cloud & network-API monetization playbooks
Cloud-native 5G cores let operators expose quality-of-service, location, and slicing functions through APIs. Enterprises pay a premium for deterministic performance, creating service revenue that offsets heavy spectrum and infrastructure investments.
4G/LPWAN sufficiency for sub-USD 2 device classes
Many low-value sensors only transmit kilobytes per day; LTE Cat-1 and NB-IoT already meet such needs at half the module cost. Rural utilities and agri-tech firms therefore defer 5G upgrades until pricing aligns with value delivered.
Other drivers and restraints analyzed in the detailed report include:
- 3GPP-approved reduced-capability chipsets below USD 5
- Energy-price-linked demand for ultra-low-power modules
- Security-compliance costs (NIS2, SBOM) squeeze OEM margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
LPWAN (5G RedCap) captured 53.00% of the 5G market in 2025, reflecting optimum trade-offs between cost and network capabilities. URLLC, although smaller, is projected to grow at a 40.63% CAGR as factories and autonomous vehicles demand sub-1 ms latency. The 5G Internet of Things market size for LPWAN devices is projected to rise significantly as module prices fall toward USD 4 by 2027. Enterprises migrate asset-tracking and environmental-monitoring workloads from LTE Cat-1 to RedCap to leverage network slicing without incurring full 5G hardware costs. Conversely, domains such as robotic welding and remote surgery justify the premium of URLLC, driving specialized chipset innovation.
URLLC use cases frequently pair with edge-compute nodes inside private 5G networks, replacing deterministic wired Ethernet. Audi's implementation in press-shops improved cycle times and reduced downtime, validating the business case. Component vendors compete on time-sensitive networking features and FEC schemes that guarantee packet delivery, distinguishing offers beyond bandwidth metrics. In sum, technology choice in the 5G Internet of Things market aligns with distinct latency, power, and cost envelopes instead of a one-size-fits-all roadmap.
Complete Report Scope:
- By Technology
- Ultra-Reliable Low-Latency Communications (URLLC)
- Low-Power Wide-Area Network (LPWAN 5G RedCap/NB)
- By End-User Industry
- Manufacturing
- Supply-Chain and Logistics
- Healthcare
- Retail
- Smart Cities and Infrastructure
- Automotive and Transportation
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Europe
- Germany
- United Kingdom
- France
- Spain
- Russia
- Asia-Pacific
- China
- Japan
- India
- Australia and New Zealand
- Middle East and Africa
- Middle East
- Africa
- North America
Geography Analysis
Asia-Pacific dominated the 5G Internet of Things market with China accounting for 41.25% of revenue in 2025, backed by operator capex and policy incentives. China Unicom plans 5G-Advanced coverage in 300 cities by end-2025, adding massive machine-type capacity and raising network utilization. Local integrators retrofit production lines in steel, textiles, and electronics, mainstreaming private-network know-how. India posts the fastest regional CAGR at 34.95% through 2031 as RedCap's sub-USD 5 modules fit the budget of small and medium enterprises. Government programs such as Digital India and Make-in-India relax spectrum-leasing rules, accelerating campus-wide deployments in pharma, auto, and energy verticals.
North America prioritizes private-network pilots in semiconductor fabs and defense hubs, aided by CHIPS Act grants. The automotive corridor from Michigan to Texas deploys roadside V2X units and factory URLLC links, validating return-on-investment for high-bandwidth, low-latency services. Cloud hyperscalers partner with carriers to expose network APIs that let enterprises configure paths with code, shortening service-activation cycles from months to minutes. This platform's dynamic extends the 5G Internet of Things market beyond connectivity into application hosting.
- Nokia
- Ericsson
- Huawei
- ZTE
- Cisco
- Qualcomm
- ATandT
- Verizon
- Deutsche Telekom
- Vodafone
- China Mobile
- SK Telecom
- KT Corp
- Telefonica
- Telstra
- Rogers
- Orange
- Bell Canada
- NTT DOCOMO
- Reliance Jio
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Massive device-density enablement after RedCap roll-out
- 4.2.2 Telco cloud and network-API monetisation playbooks
- 4.2.3 3GPP-approved reduced-capability (NR-Light) chipsets below US$5
- 4.2.4 Energy-price-linked demand for ultra-low-power modules
- 4.2.5 Supply-chain pressure to digitise asset-tracking post EU CSRD
- 4.2.6 Government-subsidised 5G private-network grants (US CHIPS, EU IPCEI)
- 4.3 Market Restraints
- 4.3.1 4G/LPWAN sufficiency for sub-US$2 device classes
- 4.3.2 High mmWave module BOM (>US$60) for industrial cameras
- 4.3.3 Fragmented certification regimes for RedCap in LATAM and Africa
- 4.3.4 Security-compliance costs (NIS2, SBOM) squeeze OEM margins
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology
- 5.1.1 Ultra-Reliable Low-Latency Communications (URLLC)
- 5.1.2 Low-Power Wide-Area Network (LPWAN 5G RedCap/NB)
- 5.2 By End-User Industry
- 5.2.1 Manufacturing
- 5.2.2 Supply-Chain and Logistics
- 5.2.3 Healthcare
- 5.2.4 Retail
- 5.2.5 Smart Cities and Infrastructure
- 5.2.6 Automotive and Transportation
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 South America
- 5.3.2.1 Brazil
- 5.3.2.2 Argentina
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Spain
- 5.3.3.5 Russia
- 5.3.4 Asia-Pacific
- 5.3.4.1 China
- 5.3.4.2 Japan
- 5.3.4.3 India
- 5.3.4.4 Australia and New Zealand
- 5.3.5 Middle East and Africa
- 5.3.5.1 Middle East
- 5.3.5.2 Africa
- 5.3.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Recent Developments)
- 6.4.1 Nokia
- 6.4.2 Ericsson
- 6.4.3 Huawei
- 6.4.4 ZTE
- 6.4.5 Cisco
- 6.4.6 Qualcomm
- 6.4.7 ATandT
- 6.4.8 Verizon
- 6.4.9 Deutsche Telekom
- 6.4.10 Vodafone
- 6.4.11 China Mobile
- 6.4.12 SK Telecom
- 6.4.13 KT Corp
- 6.4.14 Telefonica
- 6.4.15 Telstra
- 6.4.16 Rogers
- 6.4.17 Orange
- 6.4.18 Bell Canada
- 6.4.19 NTT DOCOMO
- 6.4.20 Reliance Jio
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


