

|
시장보고서
상품코드
2124644
동남아시아의 광고 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Southeast Asia Advertising - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 동남아시아의 광고 시장 규모는 2025년에 283억 4,000만 달러로 평가되었습니다. 2026년 324억 6,000만 달러에서 2031년까지 638억 9,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 14.52%를 나타낼 전망입니다.
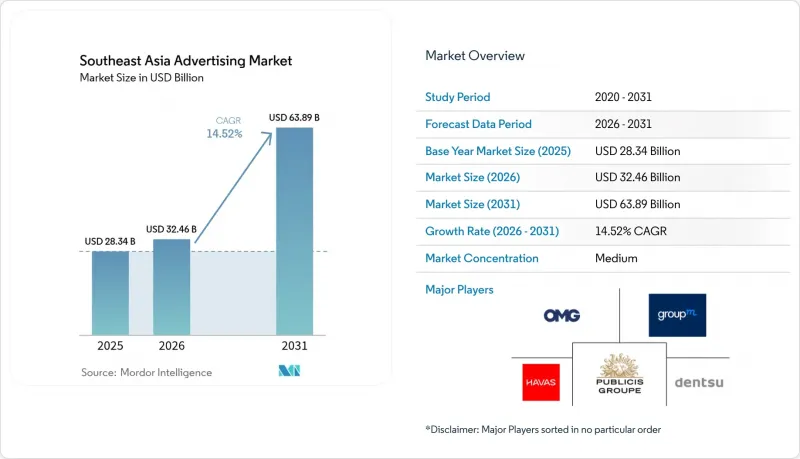
본 보고서는 채널 유형(전통적 미디어 및 디지털 미디어), 광고 매체(TV, 디지털 광고, 인쇄물 등), 거래 유형(프로그래매틱 및 비프로그래매틱), 최종 사용자 산업(FMCG, 소매 및 전자상거래, 자동차, 은행, 금융서비스 및 보험(BFSI), 통신 및 IT 등), 그리고 국가별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
동남아시아의 광고 시장 동향 및 인사이트
모바일 광대역 보급률 상승
모바일 연결은 동남아시아의 광고 시장에서 광고의 도달 범위를 재정의하고 있습니다. GSMA의 예측에 따르면, 월간 데이터 사용량은 2030년까지 4배 이상 급증하여, 그동안 대역폭 제약으로 인해 제한되었던 고비트레이트 동영상 및 몰입형 포맷의 길이 열릴 전망입니다. 인도네시아의 유선 광대역 보급률은 20% 미만이므로, 모바일이 기본 디지털 게이트웨이 역할을 하고 있으며, 광고주들은 위치 기반 타겟팅과 ‘동영상 우선’ 크리에이티브를 채택하고 있습니다. 통신 속도의 향상은 프로그래매틱 플랫폼이 활용할 수 있는 데이터의 질도 높여, 실시간 참여 지표를 광고 공간 구매 및 최적화의 핵심 메커니즘으로 변화시키고 있습니다.
프로그래매틱 DOOH의 확산 가속화
현재 디지털 사이니트에서는 실시간 기상 정보 및 교통 정보를 바탕으로 생성된 동적 광고가 전달되고 있습니다. 2024년 7월 Moving Walls와 GroupM 간에 체결된 계약을 통해 말레이시아의 구매자들은 검증된 DOOH 인벤토리를 이용할 수 있게 되었으며, 기존에 존재하던 가시성에 대한 우려가 완화되었습니다. 인구 밀도가 높은 싱가포르와 방콕에서는 알고리즘을 통한 스케줄링을 통해 브랜드가 시간대, 교통 체증 노선, 또는 모바일 기기에서 수집한 시장 내 행동 패턴에 따라 광고 크리에이티브를 순환시킬 수 있습니다. ‘Open Measurement in Out-of-Home Group’과 같은 표준화 단체는 오픈소스 노출 프레임워크를 공개하여, 광고주가 온라인 채널에서 기대하는 설명 책임을 실현하고 있습니다.
퍼블리셔 인벤토리의 고도화된 세분화
말레이시아에는 300개 이상의 간판 소유자가 존재하기 때문에 구매자는 캠페인을 파편적으로 조합할 수밖에 없습니다. CtrlShift의 AMP 마켓플레이스는 현재 7개 주요 퍼블리셔의 인벤토리를 통합하고 있지만, 그 규모는 여전히 제한적입니다. 인도네시아와 필리핀 전역에 흩어져 있는 소규모 디지털 퍼블리셔들은 공통된 애드테크 스택이나 가격 책정 투명성이 부족하여 이 문제를 더욱 심각하게 만들고 있습니다. 이러한 파편화는 거래 비용을 상승시키고, 신규 진입을 저해하며, 동남아시아의 광고 시장에서 프로그래매틱 광고 지출의 성장세를 둔화시키고 있습니다.
부문별 분석
2025년, 동남아시아의 광고 시장에서 전통적인 채널은 60.12%의 점유율을 유지했습니다. 이는 지방 및 고령층의 TV 시청 습관에 힘입은 결과입니다. 그러나 이 부문의 완만한 성장은 디지털 미디어의 연평균 성장률(CAGR) 15.05%와 대조적이며, 스마트폰과 저렴한 데이터 요금제에 힘입은 돌이킬 수 없는 소비 패턴의 변화를 시사합니다. 이러한 급속한 성장은 TV나 인쇄 매체에서는 실현할 수 없는 프로그래매틱 바이잉의 효율성과 세밀한 타겟팅에 기인합니다. 2024년, 태국에서는 디지털 광고 지출이 TV를 앞질렀으며(45% 대 35%), 소비자들의 온라인 동영상 및 소셜 피드로의 전환이 두드러졌습니다.
디지털의 진출은 실시간 현지화가 필요한 크로스보더 전자상거래 캠페인에 의해 더욱 가속화되고 있으며, 이러한 기능은 알고리즘 기반 채널에서만 제공 가능합니다. 한편, 영화관이나 기존의 옥외 광고 형식은 프리미엄 계층이 몰입감이 있고 브랜드에 안전한 환경을 중시하는 대도시권에서 여전히 중요한 역할을 하고 있습니다. 그러나 성과 지표, 어트리뷰션, 오디언스 데이터의 격차로 인해 예산은 디지털에 크게 치우쳐 있으며, 이러한 피드백 루프가 예측 기간 동안 동남아시아의 광고 시장의 지출 구성을 재편하고 있습니다.
2025년 TV의 점유율은 29.35%로, 가장 수익성이 높은 단일 미디어로서의 지위를 유지했습니다. 이는 기존의 시청 습관과 대중에 대한 도달 효율성을 모두 반영한 결과입니다. 그러나 디지털 아웃 오브 홈(DOOH)은 스크린 비용의 하락, 5G 연결, 그리고 표준화된 노출 집계 프레임워크에 힘입어 연평균 성장률(CAGR) 15.72%라는 가장 높은 성장 궤도를 보이고 있습니다. 광고주들은 DOOH가 시간대별로 광고물을 갱신하거나, 날씨나 교통 체증과 같은 지역별 특성에 따라 광고를 전달할 수 있다는 점을 높이 평가했습니다.
기존의 인쇄 매체와 라디오는 고령 독자층을 대상으로 한 신문 삽입 광고나 교통 체증이 심한 노선의 출퇴근 시간대 라디오 광고 등 틈새 시장의 매력을 유지하고 있지만, 측정 불확실성이 높아짐에 따라 그 점유율은 축소되고 있습니다. 영화관은 대히트작 개봉을 활용한 프리미엄 광고 슬롯을 제공하고 있지만, 극장의 수용 인원이 성장의 걸림돌이 되고 있습니다. 검색, 소셜, 디스플레이, OTT 동영상을 포함한 디지털 광고는 더 우수한 어트리뷰션 모델과 AI를 활용한 크리에이티브 테스트를 통해 동남아시아의 광고 시장 전반에서 브랜드의 운영 성과를 최적화하고 있으며, 방송 광고 예산에서 지속적으로 자금을 흡수하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the south East Asia advertising market size was valued at USD 28.34 billion in 2025 and estimated to grow from USD 32.46 billion in 2026 to reach USD 63.89 billion by 2031, at a CAGR of 14.52% during the forecast period (2026-2031).
This report is Segmented by Channel Type (Traditional Media and Digital Media), Advertising Medium (Television, Digital Advertising, Print, and More), Transaction Type (Programmatic and Non-Programmatic), End-User Industry (FMCG, Retail and E-Commerce, Automotive, BFSI, Telecom and IT, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Southeast Asia Advertising Market Trends and Insights
Rising Mobile Broadband Penetration
Mobile connectivity is redefining ad reach across the Southeast Asia Advertising market. GSMA projects that monthly data usage will surge more than fourfold by 2030, opening space for high-bit-rate video and immersive formats that were previously bandwidth-constrained. With Indonesia's fixed broadband penetration below 20%, mobile is the default digital gateway, prompting advertisers to adopt location-based targeting and video-first creative. Faster speeds also enrich the data available to programmatic platforms, turning real-time engagement metrics into the primary mechanism for buying and optimizing inventory.
Accelerated Uptake of Programmatic DOOH
Digital billboards now stream dynamic ads shaped by live weather or traffic feeds. A July 2024 deal between Moving Walls and GroupM gave Malaysian buyers verified DOOH inventory, mitigating historical viewability doubts. In dense Singapore and Bangkok, algorithmic scheduling lets brands rotate creative by daypart, congested routes, or in-market behaviors pulled from mobile devices. Standard-setting bodies such as the Open Measurement in Out-of-Home Group released open-source impression frameworks, bringing the accountability that advertisers expect from online channels.
High Fragmentation of Publisher Inventory
Malaysia counts more than 300 billboard owners, forcing buyers to stitch together campaigns piecemeal. CtrlShift's AMP marketplace now aggregates inventory from seven major publishers, but scale remains limited. Smaller digital publishers across Indonesia and the Philippines compound the problem, lacking common ad-tech stacks or transparency in pricing. Fragmentation raises transaction costs, deters new entrants, and slows the growth trajectory of programmatic spend within the Southeast Asia Advertising market.
Other drivers and restraints analyzed in the detailed report include:
- Government-Led Digital-First SME Incentives
- AI-Driven Dynamic Creative Optimization
- Opaque Agency Rebate Practices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Traditional channels retained a 60.12% share of the South East Asia Advertising market in 2025, buoyed by entrenched TV viewership among rural and older audiences. Yet the segment's modest growth contrasts with digital media's 15.05% CAGR, signaling an irreversible consumption pivot fueled by smartphones and cheaper data plans. Rapid gains stem from programmatic buying efficiencies and granular targeting that television or print cannot match. Thailand marked a pivotal moment in 2024 when digital ad spend surpassed TV, taking 45% versus 35%, underlining consumer migration to online video and social feeds.
Digital's advance is accelerated further by cross-border e-commerce campaigns demanding real-time localization, a capability only algorithmic channels can deliver. Meanwhile, cinema and classic outdoor formats remain relevant in dense metros, where premium audiences value immersive, brand-safe settings. Still, the differential in performance metrics, attribution, and audience data tilts budgets heavily toward digital, reinforcing a feedback loop that reshapes the spending mix of the Southeast Asia Advertising market over the forecast period.
Television's 29.35% stake in 2025 still positions it as the most lucrative single medium, reflecting both legacy habit and mass-reach efficiency. However, Digital Out-of-Home exhibits the highest trajectory at 15.72% CAGR, aided by falling screen costs, 5G connectivity, and standardized impression counting frameworks. Advertisers appreciate DOOH's ability to refresh creative by daypart or trigger ads based on localized stimuli such as weather or traffic congestion.
Traditional print and radio keep niche appeal, newspaper inserts among older readers, and commuter-time radio ads on high-congestion routes, but their share contracts as measurement gaps widen. Cinema capitalizes on blockbuster releases for premium placements, yet venue capacity caps growth. Digital advertising covering search, social, display, and OTT video continues to siphon dollars from broadcast budgets, riding on better attribution models and AI-enhanced creative testing that optimize in-flight performance for brands across the Southeast Asia Advertising market.
Complete Report Scope:
- By Channel Type
- Traditional Media
- Digital Media
- By Advertising Medium
- Television
- Digital Advertising
- Radio
- Cinema
- Out-of-Home (OOH)
- Digital OOH (DOOH)
- By Transaction Type
- Programmatic
- Non-Programmatic
- By End-User Industry
- Fast-Moving Consumer Goods (FMCG)
- Retail and E-commerce
- Automotive
- BFSI
- Telecom and IT
- Healthcare and Pharma
- Travel and Tourism
- Other End-User Industries
- By Country
- Singapore
- Malaysia
- Indonesia
- Thailand
- Vietnam
- Philippines
- Other Countries (Cambodia, Laos, Myanmar, Brunei, Timor-Leste)
List of Companies Covered in this Report:
- Dentsu International Asia Pte. Ltd.
- GroupM Asia Pacific Holdings Ltd.
- Omnicom Media Group Asia Pacific Pte. Ltd.
- Publicis Groupe SA
- Havas Media Asia Pacific Pte. Ltd.
- IPG Mediabrands Singapore Pte. Ltd.
- JCDecaux Singapore Pte. Ltd.
- Clear Channel Singapore Pte. Ltd.
- XCO Media Pte. Ltd.
- Mediacorp OOH Media Pte. Ltd.
- Moove Media Pte. Ltd.
- SPH Media Limited (SPHMBO)
- Moving Walls Sdn. Bhd.
- Spectrum Outdoor Sdn. Bhd.
- TAC Media Sdn. Bhd.
- VGI Global Media Public Co. Ltd.
- Sea Digital Media Pte. Ltd.
- AdColony (Digital Turbine Singapore Pte. Ltd.)
- GrabAds Holdings Pte. Ltd.
- Gojek Ads (PT Dompet Anak Bangsa)
- Kantar Media Singapore Pte. Ltd.
- Innity Corporation Berhad
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising mobile broadband penetration
- 4.2.2 Accelerated uptake of programmatic DOOH
- 4.2.3 Government-led digital-first SME incentives
- 4.2.4 AI-driven dynamic creative optimisation
- 4.2.5 Super-app advertising ecosystems (Grab, Gojek)
- 4.2.6 Cross-border e-commerce boom
- 4.3 Market Restraints
- 4.3.1 High fragmentation of publisher inventory
- 4.3.2 Opaque agency rebate practices
- 4.3.3 Stringent personal-data regulations (PDPA variants)
- 4.3.4 Limited measurement standards for DOOH
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Channel Type
- 5.1.1 Traditional Media
- 5.1.2 Digital Media
- 5.2 By Advertising Medium
- 5.2.1 Television
- 5.2.2 Digital Advertising
- 5.2.3 Print
- 5.2.4 Radio
- 5.2.5 Cinema
- 5.2.6 Out-of-Home (OOH)
- 5.2.7 Digital OOH (DOOH)
- 5.3 By Transaction Type
- 5.3.1 Programmatic
- 5.3.2 Non-Programmatic
- 5.4 By End-User Industry
- 5.4.1 Fast-Moving Consumer Goods (FMCG)
- 5.4.2 Retail and E-commerce
- 5.4.3 Automotive
- 5.4.4 BFSI
- 5.4.5 Telecom and IT
- 5.4.6 Healthcare and Pharma
- 5.4.7 Travel and Tourism
- 5.4.8 Other End-User Industries
- 5.5 By Country
- 5.5.1 Singapore
- 5.5.2 Malaysia
- 5.5.3 Indonesia
- 5.5.4 Thailand
- 5.5.5 Vietnam
- 5.5.6 Philippines
- 5.5.7 Other Countries (Cambodia, Laos, Myanmar, Brunei, Timor-Leste)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Dentsu International Asia Pte. Ltd.
- 6.4.2 GroupM Asia Pacific Holdings Ltd.
- 6.4.3 Omnicom Media Group Asia Pacific Pte. Ltd.
- 6.4.4 Publicis Groupe SA
- 6.4.5 Havas Media Asia Pacific Pte. Ltd.
- 6.4.6 IPG Mediabrands Singapore Pte. Ltd.
- 6.4.7 JCDecaux Singapore Pte. Ltd.
- 6.4.8 Clear Channel Singapore Pte. Ltd.
- 6.4.9 XCO Media Pte. Ltd.
- 6.4.10 Mediacorp OOH Media Pte. Ltd.
- 6.4.11 Moove Media Pte. Ltd.
- 6.4.12 SPH Media Limited (SPHMBO)
- 6.4.13 Moving Walls Sdn. Bhd.
- 6.4.14 Spectrum Outdoor Sdn. Bhd.
- 6.4.15 TAC Media Sdn. Bhd.
- 6.4.16 VGI Global Media Public Co. Ltd.
- 6.4.17 Sea Digital Media Pte. Ltd.
- 6.4.18 AdColony (Digital Turbine Singapore Pte. Ltd.)
- 6.4.19 GrabAds Holdings Pte. Ltd.
- 6.4.20 Gojek Ads (PT Dompet Anak Bangsa)
- 6.4.21 Kantar Media Singapore Pte. Ltd.
- 6.4.22 Innity Corporation Berhad
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


