

|
시장보고서
상품코드
2124651
겸상 적혈구증 치료 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Sickle Cell Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
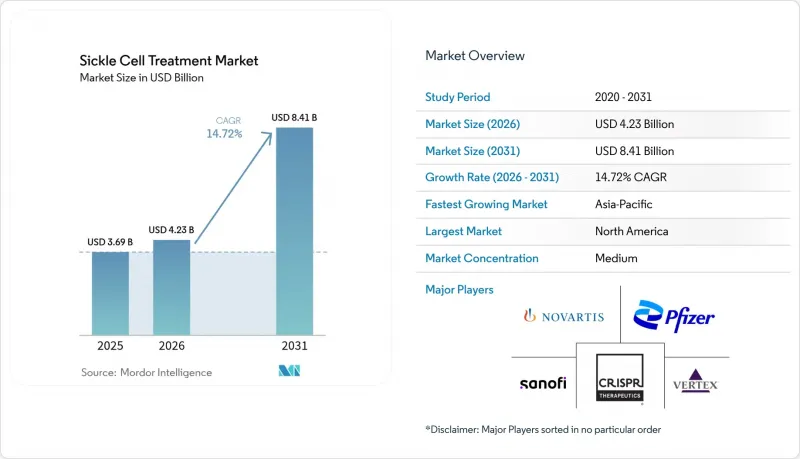
에 의하면, 세계의 겸상 적혈구증 치료 시장 규모는 2025년에 36억 9,000만 달러로 평가되었습니다. 2026년 42억 3,000만 달러에서 2031년까지 84억 1,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 14.72%를 나타낼 전망입니다.
본 보고서는 치료법(수혈, 조혈모세포이식(HSCT), 약물 요법, 유전자 편집 요법), 환자 연령대(소아 : 0-17세, 성인 : 18-49세,고령자 : 50세 이상), 질환의 중증도(급성 발작, 만성 질환 수정 요법, 근치 요법), 최종 사용자(병원, 전문 클리닉 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 겸상 적혈구증 치료 시장 동향 및 인사이트
낫적혈구 변이 유병률 증가
2021년, 전 세계적으로 낫적혈구병의 영향을 받는 신생아 수는 51만 5,000명에 달했으며, 연간 사망자 수는 37만 6,000명으로 여전히 높은 수준을 유지하여, 치료적 개입에 대한 다지역적인 수요가 지속되고 있습니다. 나이지리아는 전 세계 환자 수의 3분의 1을 차지하고 있는 반면, 이민자 유입으로 인해 유럽 및 걸프 국가들의 환자 수가 증가하고 있습니다. 사우디아라비아의 국가 등록 제도에서는 공공 의료 기관에 등록된 2만 2,956명의 환자를 추적하고 있으며, 이를 통해 의료 연계 및 실제 임상 데이터 수집이 가능해졌습니다. 고소득 국가에서의 평균 수명 연장으로 인해, 장기적인 질병 수정 요법이나 근치적 치료가 필요한 성인 환자가 다시 급증하고 있습니다.
견고한 후기 단계 연구개발 파이프라인
유전자 편집제, 대사 조절제, 후성유전학적 조절제가 2상 및 3상 임상시험 프로그램을 진행 중이어서 임상 개발의 모멘텀은 여전히 견고합니다. 에타보피바트는 혈관 폐색성 발작을 완화하는 것으로 나타났으며, 미타피바트는 적혈구 대사를 표적으로 합니다. 또한 노바티스의 dWIZ-1이나 풀크럼의 후성유전학적 후보 약물과 같은 차세대 약물은 작용기전의 폭을 넓히고 있습니다. 임상시험 설계에는 환자 보고 결과(PRO) 및 실세계 데이터가 통합되어 있어, 이를 통해 승인 신청 서류의 효율성이 제고되고 상용화 위험이 감소하고 있습니다.
높은 총 치료비와 유전자 편집 치료의 1회 사용 가격
Casgevy의 상업적 정가 220만 달러, Lyfgenia의 310만 달러라는 가격은 입원 횟수 감소로 인한 평생 비용 절감이 예상에도 불구하고, 경제적 부담의 무게라는 과제를 야기하고 있습니다. Bluebird Bio사는 70곳 이상의 치료 센터를 설립했으나, 지불 기관이 치료 성과 연동형 지불 일정을 협상함에 따라 치료의 보급은 정체되어 있습니다. 전처치, 입원, 모니터링에 드는 추가 비용이 총 비용을 부풀려 광범위한 접근성 실현을 지연시키고 있습니다.
부문별 분석
유전자 편집은 2026년부터 2031년에 걸쳐 연평균 성장률(CAGR) 17.05%라는 가장 빠른 성장 궤도를 그리고 있으며, 이는 일회성 근치적 개입에 대한 지불 기관의 강한 관심을 반영하고 있습니다. 약물 요법은 2025년 매출의 45.97%를 차지하며, 하이드록시우레아 및 최근 도입된 질환 수정 약물에 대한 꾸준한 수요를 뒷받침했습니다. 2025년 겸상 적혈구증 치료 시장에서 약물 요법 시장 규모는 17억 달러에 달했으나, 유전자 편집의 점유율은 이보다 작았으나 Casgevy 및 Lyfgenia의 승인을 받아 성장세가 가속화되고 있습니다. 줄기세포 이식의 경우, 기증자 부족이나 전처치에 따른 합병증과 같은 과제가 여전히 존재하여 시술 건수의 확대를 제한하고 있습니다.
블루버드 바이오와 버텍스는 서로 다른 전개 전략을 선택했습니다. 블루버드는 광범위한 치료 시설의 인증을 우선시한 반면, 버텍스는 35개의 허브를 통해 환자의 동선을 효율화하고 처리 능력 향상에 주력했습니다. 테세라 테라퓨틱스는 채취 및 재주입 공정을 생략할 수 있는 ‘생체 내 유전자 라이터’ 연구를 진행 중이며, 이를 통해 서비스 제공 비용 절감과 자원이 제한된 환경에서의 겸상적혈구빈혈 치료 시장 확대가 기대됩니다.
18-49세의 성인 환자는 생존율 향상과 유전자 치료 적격 기준에 포함된 점에 힘입어 연평균 성장률(CAGR) 15.76%를 기록했습니다. 소아 부문은 의무적 선별 검사 및 조기 개입 프로그램의 지원에 힘입어 2025년에는 겸상 적혈구증 치료 시장의 50.12% 점유율을 차지했습니다. 사우디아라비아의 등록 데이터에 따르면, 환자의 평균 연령은 28세로, 성인 의료로의 전환이 순조롭게 진행되고 있음을 반영합니다.
고령층에서는 장기 합병증이 누적되기 때문에 병용 요법이나 다학제적 후속 관리가 요구되고 있습니다. 자금 조달 및 임상 역량이 갖춰진 지역에서는 성인 대상 유전자 치료 도입이 진행되고 있으며, 이는 첨단 치료법을 대상으로 하는 겸상 적혈구증 치료 시장 규모를 확대시키고 있습니다.
지역별 분석
북미는 조기 승인, 높은 보험 적용률, 그리고 밀집된 전문의 네트워크 덕분에 2025년에는 매출의 35.92%를 차지했습니다. 미국은 여전히 정책 동향을 주도하고 있으며, CMS(미국 의료보험서비스센터)를 통해 가치 기반 지불 모델을 설계하여 전 세계 상환 제도에 대한 논의에 영향을 미치고 있습니다. 캐나다와 멕시코는 주 및 사회보장 체계를 활용하여 고가의 치료법을 지원하고 있으나, 도입률은 주나 자금 조달 주기에 따라 다릅니다. 국경을 초월한 협력을 통해 멕시코 환자들은 미국의 의료 센터를 이용할 수 있게 되어 치료 선택의 폭이 넓어지고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 15.93%로 가장 높은 성장세를 보이고 있습니다. 인도의 ‘겸상적혈구빈혈 근절 미션’은 17개 주에서 보편적 선별 검사를 실시하며, 환자 교육 및 지원되는 약물 요법을 통합하고 있습니다. 이러한 노력을 통해 진단되는 환자 수가 증가하고 있으며, 제네릭 의약품 조달 규모도 확대되고 있습니다. 말레이시아, 태국, 인도네시아에서는 의료 제공업체의 78%가 치료비 부담을 주요 장벽으로 꼽고 있어, 비용 대비 효과가 높은 혁신 기술에 대한 수요가 높아지고 있습니다. 각 지역 정부는 공공 예산과 환자의 치료 성과 간 균형을 맞추기 위해 단계적 가격 책정에 대해 협상을 진행 중이며, 인프라가 정비되는 대로 궁극적으로 근원적 치료법 도입을 위한 기반이 마련될 전망입니다.
유럽에서는 견고한 사회보험 제도와 유럽의약품청(EMA)의 규제 일관성을 기반으로 착실한 도입이 진행되고 있습니다. 독일과 프랑스에서는 위험 분담 계약에 따라 유전자 편집 치료 비용이 상환되고 있는 반면, 영국에서는 예산 주기 전체에 비용을 분산시키기 위해 연금 방식의 지불 구조를 시범적으로 도입하고 있습니다. 중동 및 아프리카에서는 상황이 양극화되어 있습니다. 바레인이 미국 이외의 국가 중 최초로 CRISPR 치료를 시행한 것을 필두로, 걸프 국가들은 정밀 의학에 막대한 투자를 하고 있습니다. 사하라 이남 아프리카는 유병률이 가장 높음에도 불구하고 인프라 제약에 직면해 있어, 첨단 제품의 단기적 도입이 더딘 양상을 보이고 있습니다. WHO의 2024년 지침 패키지에서는 기부자 자금을 검사실 역량 강화, 인력 양성 및 공급망 회복력 향상에 활용하도록 권고하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the global sickle cell treatment market size was valued at USD 3.69 billion in 2025 and estimated to grow from USD 4.23 billion in 2026 to reach USD 8.41 billion by 2031, at a CAGR of 14.72% during the forecast period (2026-2031).
This report is Segmented by Treatment Modality (Blood Transfusion, HSCT, Pharmacotherapy, Gene-Editing Therapies), Patient Age Group (Pediatric 0-17 Yrs, Adult 18-49 Yrs, Older Adult 50+ Yrs), Disease Severity (Acute Crisis, Chronic Disease-Modifying, Curative), End-User (Hospitals, Specialty Clinics, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Sickle Cell Treatment Market Trends and Insights
Increasing Prevalence of Sickle-Cell Mutations
Global births affected by sickle cell disease reached 515,000 in 2021, and annual mortality remains high at 376,000 deaths, sustaining multi-regional demand for therapeutic interventions. Nigeria drives one-third of the global patient pool, while migration elevates case numbers in Europe and the Gulf. National registries in Saudi Arabia track 22,956 patients across state facilities, enabling care coordination and real-world data capture. Longevity gains in high-income countries create a second surge of adult patients who require long-term disease-modifying or curative options.
Robust Late-Stage R&D Pipeline
Clinical momentum remains strong as gene editors, metabolic modulators, and epigenetic regulators advance through Phase 2 and Phase 3 programs. Etavopivat shows reduction in vaso-occlusive crises, mitapivat targets red cell metabolism, and next-generation agents such as Novartis dWIZ-1 and Fulcrum's epigenetic candidates broaden mechanisms of action. Trial designs integrate patient-reported outcomes and real-world evidence, streamlining approval packages and lowering commercialization risk.
High Total Cost of Care & Single-Use Gene-Editing Prices
Commercial list prices of USD 2.2 million for Casgevy and USD 3.1 million for Lyfgenia create affordability stress despite projected lifetime savings from reduced hospitalizations. Bluebird Bio established more than 70 treatment centers, yet uptake stalled as payers negotiated outcome-linked payment schedules. Additional costs for conditioning, hospitalization, and monitoring inflate total spending envelopes, delaying widespread access.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Fast-Track & Orphan-Drug Incentives
- Commercial Rollout of Disease-Modifying Drugs
- Cold-Chain & Infusion-Centre Infrastructure Gaps in LMICs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Gene editing commanded the fastest trajectory with a 17.05% CAGR between 2026 and 2031, reflecting strong payer interest in one-time curative interventions. Pharmacotherapy retained 45.97% of revenue in 2025, underscoring entrenched demand for hydroxyurea and recently introduced disease-modifying drugs. The sickle cell treatment market size for pharmacotherapy reached USD 1.7 billion in 2025, while gene-editing's share was smaller but accelerating following Casgevy and Lyfgenia approvals. Stem cell transplantation continues to face donor limitations and conditioning-related morbidity that restrict procedural volumes.
Bluebird Bio and Vertex selected divergent roll-out strategies. Bluebird prioritized broad treatment-site certification, whereas Vertex focused on streamlined patient funneling through 35 hubs to improve throughput. Tessera Therapeutics explores in-vivo gene writers that could bypass harvesting and reinfusion steps, potentially lowering cost-to-serve and expanding the sickle cell treatment market in resource-limited settings.
Adult patients aged 18-49 posted a 15.76% CAGR, supported by survival gains and inclusion in gene-therapy eligibility criteria. The pediatric segment held a 50.12% sickle cell treatment market share in 2025, backed by mandatory screening and early intervention programs. Saudi registry averages indicate a patient age of 28 years, reflecting successful transition to adult care.
Higher age groups bring cumulative organ complications, driving combination therapy regimens and multidisciplinary follow-up. Adult uptake of gene therapy is rising where financing and clinical capacity align, enlarging the sickle cell treatment market size for advanced modalities.
Complete Report Scope:
- By Treatment Modality
- Blood Transfusion
- Hematopoietic Stem-Cell Transplant (HSCT)
- Pharmacotherapy
- Hydroxyurea
- L-Glutamine
- Voxelotor
- Crizanlizumab
- Others (incl. Pain-management, Folic Acid)
- Gene-Editing / Gene-Addition Therapies
- By Patient Age Group
- Paediatric (0-17 yrs)
- Adult (18-49 yrs)
- Older Adult (50 yrs +)
- By Disease Severity / Clinical Objective
- Acute Crisis Management
- Chronic Disease-Modifying
- Curative / Potentially Curative
- By End-User
- Hospitals
- Specialty Clinics
- Ambulatory Surgical Centres
- Academic & Research Institutes
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America commanded 35.92% revenue in 2025 due to early approvals, high insurance coverage, and dense specialist networks. The United States remains the policy trendsetter, designing value-based payment models through CMS that influence global reimbursement debate. Canada and Mexico leverage provincial and social security frameworks to subsidize costly therapies, although adoption rates vary by province and funding cycle. Cross-border collaborations allow Mexican patients to access US centers, expanding treatment choices.
Asia-Pacific carries the highest growth momentum at a 15.93% CAGR. India's National Sickle Cell Anaemia Elimination Mission implements universal screening across 17 states, integrating patient education and subsidized pharmacotherapy. The initiative enlarges the diagnosed pool and creates procurement scale for generics. Malaysia, Thailand, and Indonesia report that 78% of providers highlight treatment affordability as a primary barrier, reinforcing demand for cost-effective innovation. Regional governments negotiate tiered pricing to balance public budgets and patient outcomes, paving the way for eventual curative therapy roll-out once infrastructure matures.
Europe exhibits steady adoption anchored by strong social insurance systems and EMA regulatory synchrony. Germany and France reimburse gene editing under risk-sharing deals, while the United Kingdom pilots annuity payment structures to spread cost across budget cycles. Middle East and Africa are bifurcated. Gulf states, led by Bahrain's first CRISPR treatment outside the United States, invest heavily in precision medicine. Sub-Saharan Africa, despite highest prevalence, confronts infrastructure limits that dull near-term adoption of advanced products. WHO's 2024 guideline package directs donor funding toward lab capacity, workforce training, and supply-chain resilience.
- Novartis
- Pfizer
- Sanofi
- Vertex Pharmaceuticals Inc.
- CRISPR Therapeutics AG
- Emmaus Life Sciences Inc.
- Teva Pharmaceutical Industries
- Hikma Pharmaceuticals
- Cipla
- Apotex
- Sandoz Group AG
- Fresenius
- Terumo
- Cerus
- Grifols
- CSL Behring GmbH
- Kedrion Biopharma SpA
- Baxter
- Medunik USA
- Accord Healthcare Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Prevalence Of Sickle-Cell Mutations
- 4.2.2 Robust Late-Stage R&D Pipeline
- 4.2.3 Regulatory Fast-Track & Orphan-Drug Incentives
- 4.2.4 Commercial Rollout Of Disease-Modifying Drugs (Voxelotor, Crizanlizumab)
- 4.2.5 Expansion Of Newborn Screening In Sub-Saharan Africa
- 4.2.6 Value-Based Reimbursement For Curative Gene-Editing Therapies
- 4.3 Market Restraints
- 4.3.1 High Total Cost Of Care & Single-Use Gene-Editing Prices
- 4.3.2 Limited Matched-Donor Availability For HSCT
- 4.3.3 Cold-Chain & Infusion-Centre Infrastructure Gaps In LMICs
- 4.3.4 Uneven Insurance Coverage And Benefit-Design Exclusions
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technology Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value-USD)
- 5.1 By Treatment Modality
- 5.1.1 Blood Transfusion
- 5.1.2 Hematopoietic Stem-Cell Transplant (HSCT)
- 5.1.3 Pharmacotherapy
- 5.1.3.1 Hydroxyurea
- 5.1.3.2 L-Glutamine
- 5.1.3.3 Voxelotor
- 5.1.3.4 Crizanlizumab
- 5.1.3.5 Others (incl. Pain-management, Folic Acid)
- 5.1.4 Gene-Editing / Gene-Addition Therapies
- 5.2 By Patient Age Group
- 5.2.1 Paediatric (0-17 yrs)
- 5.2.2 Adult (18-49 yrs)
- 5.2.3 Older Adult (50 yrs +)
- 5.3 By Disease Severity / Clinical Objective
- 5.3.1 Acute Crisis Management
- 5.3.2 Chronic Disease-Modifying
- 5.3.3 Curative / Potentially Curative
- 5.4 By End-User
- 5.4.1 Hospitals
- 5.4.2 Specialty Clinics
- 5.4.3 Ambulatory Surgical Centres
- 5.4.4 Academic & Research Institutes
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Novartis AG
- 6.3.2 Pfizer Inc.
- 6.3.3 Sanofi SA
- 6.3.4 Vertex Pharmaceuticals Inc.
- 6.3.5 CRISPR Therapeutics AG
- 6.3.6 Emmaus Life Sciences Inc.
- 6.3.7 Teva Pharmaceutical Industries Ltd.
- 6.3.8 Hikma Pharmaceuticals PLC
- 6.3.9 Cipla Ltd.
- 6.3.10 Apotex Inc.
- 6.3.11 Sandoz Group AG
- 6.3.12 Fresenius Kabi AG
- 6.3.13 Terumo BCT Inc.
- 6.3.14 Cerus Corporation
- 6.3.15 Grifols SA
- 6.3.16 CSL Behring GmbH
- 6.3.17 Kedrion Biopharma SpA
- 6.3.18 Baxter International Inc.
- 6.3.19 Medunik USA
- 6.3.20 Accord Healthcare Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


