

|
시장보고서
상품코드
2124690
미국의 멀티 테넌트(코로케이션) 데이터센터 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)United States Multi-Tenant (Colocation) Data Center - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
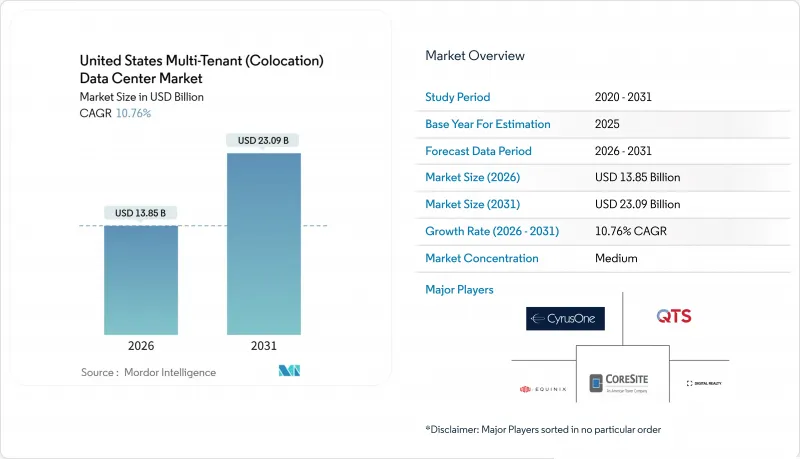
에 의하면, 미국의 멀티 테넌트(코로케이션) 데이터센터 시장 규모는 2026년에 138억 5,000만 달러로 추정되며, 2026-2031년 예측 기간에서 CAGR 10.76%로 성장을 지속하여 2031년에는 230억 9,000만 달러에 이를 전망입니다.
본 보고서는 솔루션 유형(도매형 멀티테넌트 및 소매형 멀티테넌트), 티어 유형(Tier 1 및 2, Tier 3, 티어 4), 데이터센터 규모(소규모 데이터센터, 중규모 데이터센터, 대규모 데이터센터, 하이퍼스케일 데이터센터)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
미국 멀티테넌트(코로케이션) 데이터센터 시장 동향 및 인사이트
고밀도 코로케이션을 필요로 하는 AI 및 ML 워크로드의 급속한 확대
대규모 언어 모델의 훈련을 지원하는 Nvidia H100 클러스터는 캐비닛당 100kW를 상시 초과하는 밀도를 보이지만, 2025년 12월 시점에서 이 밀도를 수용할 수 있는 미국의 코로케이션 시설은 고작 18%에 불과합니다. 따라서 각 하이퍼스케일러 기업들은 다음 GPU 할당 주기를 앞두고 액체 냉각 준비를 완료하기 위해 5-10 MW 규모의 도매용 스위트를 확보하고 있습니다. CyrusOne은 2025년 1-3분기 전체 수주 중 AI 관련 고객이 42%를 차지했다고 밝혔습니다. 리어 도어 방식의 열교환기에 투자하고 있는 사업자에 따르면, 기존 도입 방식에 비해 30-40%의 가격 프리미엄이 발생하고 있으며, 이로 인해 투자 회수 기간이 4년 미만으로 단축되고 있습니다. 미국 화재방지협회(NFPA)는 이러한 고밀도 클러스터용 리튬 이온 배터리 소화 프로토콜을 명확히 하기 위해 NFPA 75의 개정을 추진하고 있습니다.
하이브리드 클라우드 및 엣지 컴퓨팅 아키텍처 도입 가속화
Flexential의 조사에 따르면, 2024년부터 2025년에 걸쳐 하이브리드 배포를 시행하는 기업 고객의 비율이 51%에서 63%로 급증했습니다. 기업들은 지연 시간 및 데이터 주권 관련 요건을 충족하기 위해 On-Premise 랙, 퍼블릭 클라우드 리전, 코로케이션 케이지에 워크로드를 분산하고 있습니다. EdgeConneX는 전국 규모의 플랫폼이 간과했던 오마하, 보이시, 롤리 같은 도시에 집중함으로써 엣지 거점을 42곳으로 확대했습니다. 분석가들은 2028년까지 800-1,000 MW의 새로운 엣지 코로케이션 수요가 발생할 것으로 전망하고 있습니다. HIPAA와 같은 규제 제약으로 인해, 캐리어 중립적인 사업자와의 하이브리드 클라우드 제휴가 계속해서 유리한 입지를 차지하고 있습니다.
전력망 제약의 심화와 전력 회사의 리드타임
버지니아주 북부의 미처리 계통 연계 신청은 4.2 GW를 초과하며, 이는 약 3년 치의 미처리 물량에 해당합니다. 도미니언 에너지(Dominion Energy)는 2025년, 라우던 카운티의 일부 지역에서 신규 대용량 부하의 계통 연계를 동결했으며, 건설 사업자는 변전소 건설 비용을 자체 부담하거나 전력 공급을 연기할 수밖에 없게 되었습니다. 애리조나 퍼블릭 서비스(Arizona Public Service)도 피닉스에서 유사한 공급 부족에 직면해 있으며, 이 지역에서는 2025년에 데이터센터 신청량이 1.8 GW를 넘어섰습니다. 연방에너지규제위원회(FERC)는 대기 목록을 신속히 해소하기 위해 부지 확보가 확실하고 환경 심사가 완료된 프로젝트를 우선적으로 처리할 가능성이 있습니다. 사업자들은 발전 설비 인접지에서 코로케이션을 시작하거나, 50MW 규모의 홀당 5,000만-8,000만 달러의 추가 비용을 들여 부지 내에 천연가스 피크 발전 설비를 설치하고 있습니다.
부문 분석
2025년, 미국 멀티테넌트(코로케이션) 데이터센터 시장에서 소매 코로케이션은 62.53%의 점유율을 차지했습니다. 이는 설비 투자를 피할 수 있는 턴키 방식의 랙 단위 임대가 중소기업에게 매력적임을 반영합니다. 사업자는 전력, 냉각, 물리적 보안을 패키지로 제공하며, 고객은 랙 단위로 워크로드를 확장할 수 있습니다. 5MW 이상의 도매 임대는 하이퍼스케일러가 전력 공급 대기열에서 발생하는 불확실성을 피하기 위해 연속적인 용량을 확보하고 있기 때문에 연평균 성장률(CAGR) 11.32%라는 더 빠른 속도로 성장하고 있습니다. 도매 부문은 맞춤형 전기 토폴로지, 액체 냉각 루프, 전용 미트룸이 필요한 AI 및 하이브리드 클라우드 워크로드의 혜택을 받고 있습니다.
CyrusOne의 ‘Massively Modular’ 구축 방식을 통해 2025년에는 테넌트가 랙당 최대 30kW를 지정할 수 있게 되어, 프리미엄 요금으로 도매 수요를 유치할 수 있었습니다. Digital Realty는 2025년에 완공 예정인 240 MW 규모의 파이프라인 중, 첫 발전 전에 85%를 사전 임대 계약한 상태이며, 이는 여전히 공급이 수요를 따라가지 못하고 있음을 보여줍니다. 기업들은 여러 대도시권에 걸친 지리적 분산과 재해 복구 옵션을 중시하고 있기 때문에 소매 코로케이션 시장은 계속해서 견조한 모습을 보일 것입니다. 그러나 도매 부문의 급속한 확대로 인해, 예측 기간 동안 가동에 들어가는 신규 메가와트의 대부분은 도매 부문이 차지하게 될 것입니다. 그 결과, 미국의 멀티테넌트(코로케이션) 데이터센터 시장에서는 확고히 자리 잡은 소매 도입 기반을 훼손하지 않으면서도 점차 도매 쪽으로 균형이 재조정될 것입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.14According to Mordor Intelligence, the United States multi-tenant (colocation) data center market size is estimated at USD 13.85 billion in 2026, and is expected to reach USD 23.09 billion by 2031, at a CAGR of 10.76% during the forecast period 2026-2031.
This report is Segmented by Solution Type (Wholesale Multi-Tenant and Retail Multi-Tenant), Tier Type (Tier 1 and 2, Tier 3, and Tier 4), and Data Center Size (Small Data Center, Medium Data Center, Large Data Center, and Hyperscale Data Center). The Market Forecasts are Provided in Terms of Value (USD).
United States Multi-Tenant (Colocation) Data Center Market Trends and Insights
Rapid Proliferation of AI and ML Workloads Requiring High-Density Colocation
Nvidia H100 clusters that underpin large-language-model training routinely exceed 100 kW per cabinet, a density that only 18% of US colocation halls could support in December 2025. Hyperscalers therefore reserve wholesale suites of 5-10 MW to secure liquid-cooling readiness before the next GPU allocation cycle. CyrusOne disclosed that AI customers represented 42% of all bookings during the first three quarters of 2025. Operators that invest in rear-door heat exchangers report 30-40% pricing premiums relative to legacy deployments, compressing payback periods to under four years. National Fire Protection Association is revising NFPA 75 to clarify lithium-ion battery suppression protocols for such high-density clusters.
Accelerating Adoption of Hybrid Cloud and Edge Computing Architectures
Flexential recorded a jump from 51% to 63% of enterprise customers running hybrid deployments between 2024 and 2025. Enterprises distribute workloads across on-premises racks, public-cloud regions, and colocation cages to satisfy latency and data-sovereignty mandates. EdgeConneX expanded to 42 edge locations by focusing on Omaha, Boise, and Raleigh, cities overlooked by national platforms. Analysts expect 800-1,000 MW of new edge colocation demand by 2028. Regulatory strictures such as HIPAA continue to favor hybrid cloud alliances with carrier-neutral operators.
Escalating Power Grid Constraints and Utility Lead Times
Pending interconnection requests in Northern Virginia exceed 4.2 GW, representing nearly three years of backlog. Dominion Energy froze new large-load hookups in portions of Loudoun County during 2025, compelling builders to self-fund substations or postpone energization. Arizona Public Service faces a similar strain in Phoenix, where data-center applications surpassed 1.8 GW in 2025. The Federal Energy Regulatory Commission may prioritize projects with firm site control and completed environmental reviews to clear queues faster. Operators have begun colocating adjacent to generation assets or installing on-site natural-gas peakers at an added USD 50-80 million per 50-MW hall.
Other drivers and restraints analyzed in the detailed report include:
- Hyperscaler Preference for Build-to-Suit Wholesale Colocation in Tier-2 US Metros
- Growing Availability of Renewable Energy Purchase Agreements in US Power Markets
- Rising Land Acquisition and Construction Costs in Core Hubs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Retail colocation held 62.53% share of the United States multi-tenant (colocation) data center market in 2025, reflecting the appeal of turnkey rack-level leasing to small and midsized enterprises that avoid capital expenditure. Operators bundle power, cooling, and physical security so customers can scale workloads a single rack at a time. Wholesale leases of 5 MW or more are growing faster, at an 11.32% CAGR, as hyperscalers reserve contiguous capacity to bypass uncertainty in utility queues. The wholesale segment benefits from AI and hybrid-cloud workloads that demand bespoke electrical topologies, liquid-cooling loops, and dedicated meet-me rooms.
CyrusOne's Massively Modular builds allowed tenants to specify up to 30 kW per rack in 2025, capturing wholesale demand at premium rates. Digital Realty pre-leased 85% of its 240-MW 2025 pipeline before first power, signaling that supply still trails demand. Retail colocation will remain resilient because enterprises value geographic diversity and disaster-recovery options across multiple metros, yet wholesale's faster expansion ensures it will capture the majority of incremental megawatts commissioned during the forecast window. As a result, the United States multi-tenant (colocation) data center market will see a gradual rebalancing toward wholesale without eroding the entrenched retail installed base.
Complete Report Scope:
- By Solution Type
- Wholesale Multi-tenant
- Retail Multi-tenant
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Size
- Small Data Center
- Medium Data Center
- Large Data Center
- Hyperscale Data Center
List of Companies Covered in this Report:
- Equinix Inc.
- Digital Realty Trust Inc.
- CyrusOne LLC
- Quality Technology Services (QTS Realty Trust)
- CoreSite Realty Corporation (American Tower)
- Switch Inc.
- Iron Mountain Data Centers
- Aligned Data Centers
- Flexential Corp.
- Sabey Data Centers
- EdgeConneX Inc.
- STACK Infrastructure
- Compass Datacenters
- DataBank Ltd.
- NTT Communications Corporation
- KDDI Corporation (Telehouse America)
- DataGryd
- Rackspace Technology Inc.
- IBM Corporation
- Vantage Data Centers
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions
- 1.2 Market Definition and Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating Adoption of Hybrid Cloud and Edge Computing Architectures
- 4.2.2 Rapid Proliferation of AI/ML Workloads Requiring High-Density Colocation
- 4.2.3 Growing Availability of Renewable Energy Purchase Agreements in US Power Markets
- 4.2.4 Surging Demand for Interconnection Hubs from Content and OTT Providers
- 4.2.5 Hyperscaler Preference for Build-to-Suit Wholesale Colocation in Tier-2 US Metros
- 4.2.6 Federal and State Tax Incentives for Data Center Construction and Modernization
- 4.3 Market Restraints
- 4.3.1 Escalating Power Grid Constraints and Utility Lead Times in High-Demand Markets
- 4.3.2 Rising Land Acquisition and Construction Costs in Core US Data Center Hubs
- 4.3.3 Intensifying Sustainability Reporting Requirements Increasing Compliance Burden
- 4.3.4 Competition from Hyperscalers' Self-Built Facilities in Select Regions
- 4.4 Industry Supply-Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Solution Type
- 5.1.1 Wholesale Multi-tenant
- 5.1.2 Retail Multi-tenant
- 5.2 By Tier Type
- 5.2.1 Tier 1 and 2
- 5.2.2 Tier 3
- 5.2.3 Tier 4
- 5.3 By Data Center Size
- 5.3.1 Small Data Center
- 5.3.2 Medium Data Center
- 5.3.3 Large Data Center
- 5.3.4 Hyperscale Data Center
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Equinix Inc.
- 6.4.2 Digital Realty Trust Inc.
- 6.4.3 CyrusOne LLC
- 6.4.4 Quality Technology Services (QTS Realty Trust)
- 6.4.5 CoreSite Realty Corporation (American Tower)
- 6.4.6 Switch Inc.
- 6.4.7 Iron Mountain Data Centers
- 6.4.8 Aligned Data Centers
- 6.4.9 Flexential Corp.
- 6.4.10 Sabey Data Centers
- 6.4.11 EdgeConneX Inc.
- 6.4.12 STACK Infrastructure
- 6.4.13 Compass Datacenters
- 6.4.14 DataBank Ltd.
- 6.4.15 NTT Communications Corporation
- 6.4.16 KDDI Corporation (Telehouse America)
- 6.4.17 DataGryd
- 6.4.18 Rackspace Technology Inc.
- 6.4.19 IBM Corporation
- 6.4.20 Vantage Data Centers
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


