|
시장보고서
상품코드
2124702
인도의 산업용 펌프 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)India Industrial Pump - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 인도의 산업용 펌프 시장 규모는 2025년에 9억 7,000만 달러로 평가되었습니다. 2026년 10억 2,000만 달러에서 2031년까지 12억 8,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 4.74%를 나타낼 전망입니다.
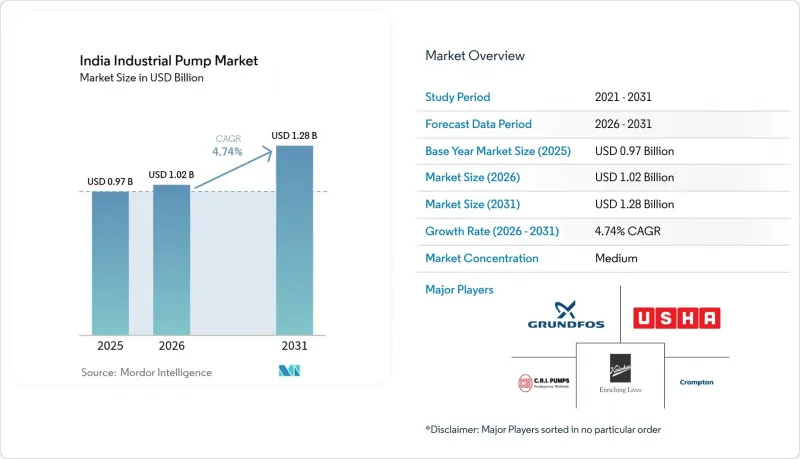
본 보고서는 펌프 유형(원심식, 용적식), 최종 사용자 산업(석유 및 가스,상하수도, 화학제품 및 석유화학제품, 발전, 광업 등), 구동 방식(전기식, 엔진 구동식, 태양광 발전식), 설치 형태(지상 설치형 펌프, 수중 펌프), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
인도의 산업용 펌프 시장 동향 및 분석
국가 인프라 파이프라인(NIP)에 기반한 정부의 설비 투자가 산업용 펌프 수요를 가속화하고 있다.
2025년까지를 기간으로 하는 111카롤 루피 규모의 국가 인프라 파이프라인(NIP)은 모든 신규 유틸리티, 정유시설 개보수 및 산업 단지에 디지털 성능 요건을 통합함으로써 펌프 조달 관행을 영구적으로 변화시켰습니다. 현재 민관 파트너십에서는 공급업체에 가동 시간 지표 보증을 요구하고 있으며, 벤더들은 산업용 IoT 센서, API 610 준수 및 장기 서비스 계약을 패키지로 제공해야 하는 상황에 처해 있습니다. 파라딥 정유시설의 2만 4,000 카롤 루피 규모의 브라운필드 프로젝트는 이러한 새로운 기준을 여실히 보여주고 있으며, 모든 펌프 스키드에 원격 진단 및 예측 유지보수 대시보드를 탑재하도록 규정하고 있습니다. 이 모델은 전국 규모의 서비스 인력과 클라우드 기반 제어 플랫폼을 유지하는 기업에 유리한 한편, 데이터 게이트웨이와 표준화된 프로토콜이 없는 저사양 수입품에 대한 진입 장벽을 높이고 있습니다. NIP의 자금 배분이 진행됨에 따라 원심 펌프의 개조는 상태 기반 교체로 전환되어, 설비 투자가 감소한 후에도 애프터마켓 수익을 유지할 수 있게 될 것입니다.
폐수 처리 능력의 급속한 확대가 특수 펌프 수요를 견인
하수 처리 커버율은 2024년 37%에서 2030년까지 70%에 달했으며, 이에 따라 효율 75% 이상의 내식성·고형물 처리 펌프 조달량이 사상 최고치를 기록하게 될 것입니다. 뭄바이 대도시권만 해도 분산형 하수 양수 및 슬러지 탈수를 위해 2만 5,000 카롤 루피의 예산이 편성되어 있으며, 부식성 환경에서 무인 운전이 가능한 2,000대 이상의 정밀 펌프가 요구되고 있습니다. 현재 사업자는 변동하는 유입 부하에 대응하기 위해 가변 주파수 구동 장치(VFD)의 채택을 의무화하고 있으며, 이에 따라 금속 공학 노하우와 VFD 패키지를 보유한 제조업체에게는 고부가가치의 틈새 시장이 형성되고 있습니다. 중앙공해관리위원회의 규제 강화로 인해 실시간 모니터링 및 이중화에 대한 수요가 더욱 높아지고 있으며, 누출이 없는 자기 구동 방식을 갖춘 원심 펌프가 경쟁 우위를 발휘하고 있습니다.
저가 중국산 펌프의 수입 급증으로 국내 시장 역학에 압박이 가해지고 있다.
중국산 모델은 국내 동급 제품보다 30-40% 저렴하여, 범용적인 상수도 및 공조(HVAC) 관련 수주를 확보함으로써 매출 총이익률을 압박하고 있습니다. 리드타임 단축과 유연한 신용 조건이 중소기업을 끌어들이고 있어, 인도 제조업체들은 생산 자동화와 간접비 절감을 강요받고 있습니다. 그러나 애프터서비스의 미비나 예비 부품의 구하기 어려움은 기존 제조업체들에게 서비스를 중시하는 대응 전략을 펼칠 기회를 제공하고 있으며, 특히 인도 표준청(BIS)이 ISI 인증 집행을 강화하고 있는 상황에서는 이러한 경향이 두드러집니다.
부문별 분석
원심 펌프는 물, 냉각 및 일반적인 공정 루프에서 적당한 양정에서 대량의 유체를 효율적으로 이송할 수 있기 때문에 2025년 인도의 산업용 펌프 시장 규모 매출의 65.02%를 차지했습니다. 용적식 펌프는 출하 대수 기준으로는 34.98%에 그치지만, 2031년까지 연평균 성장률(CAGR) 6.79%를 기록할 전망이며,특수 화학 및 제약 업계의 고객들이 가변 점도 조건 하에서 정밀한 계량을 요구하고 있기 때문에 원심 펌프의 3.95%라는 성장 속도를 상회할 것으로 예측됩니다. 각 공급업체는 원심 펌프 제품 라인에 자기 구동 장치와 세라믹 베어링을 채택함으로써 그 격차를 좁혀가고 있는 반면, 용적식 펌프 제조업체는 기존 설비의 개조를 위해 고속이며 컴팩트한 스키드형 유닛을 추진하고 있습니다. IoT를 활용한 개조를 통해 그 경계는 더욱 모호해질 것이며, 운영자는 실시간으로 효율을 벤치마킹하고 가동 주기 분석을 바탕으로 기술을 전환할 수 있게 될 것입니다. 예측 기간 동안 원심 펌프의 출하 대수는 여전히 용적식 펌프를 크게 상회하겠지만, 특수 합금 및 누출을 억제하는 이음매 없는 구조를 통한 프리미엄 가격 책정으로 인해 용적식 펌프의 매출 점유율은 상승할 전망입니다.
2025년, 인도의 산업용 펌프 시장 점유율 중 상하수도 처리 분야는 28.86%를 차지했습니다. 이는 Jal Jeevan 계획 및 3.6 카롤 루피를 초과하는 도시 지역 STP(하수 처리장)에 대한 투자에 힘입은 결과입니다. 광업 부문은 현재 매출에서 차지하는 비중이 8.40%에 그치지만, Coal India와 주요 철강 제조업체들이 기계화를 통해 생산량을 늘리고 있어 연평균 성장률(CAGR) 7.18%로 선두를 달리고 있습니다. 탈수,슬러리 및 광미 처리 라인에서는 내마모성 엘라스토머와 이상 스테인리스 스틸에 대한 수요가 높아지고 있어, 이로 인해 평균 판매 가격(ASP)이 상승하고 있습니다. 석유 및 가스 업계는 정유시설 개조를 통해 안정적인 수요를 유지하고 있는 반면, 화학 업계에서는 수입 대체 정책을 활용하여 PD 펌프 도입을 촉진하고 있습니다. 차티스가르 주의 철광석 벨트나 오디샤 주의 크롬철광 광산과 같은 지역 클러스터에서는 두 자릿수의 지출이 예상되지만, 성숙한 화력 발전소의 경우 설비 투자의 대부분이 확장이 아닌 갱신에 할당되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the India industrial pump market size was valued at USD 0.97 billion in 2025 and estimated to grow from USD 1.02 billion in 2026 to reach USD 1.28 billion by 2031, at a CAGR of 4.74% during the forecast period (2026-2031).
[1] Ministry of Finance, "Union Budget 2024-25," INDIABUDGET.GOV.IN The solid growth stems from sustained government capex under the National Infrastructure Pipeline, widening wastewater treatment coverage, and the steady shift toward smart, energy-efficient pumping systems. This report is Segmented by Pump Type (Centrifugal, and Positive-Displacement), End-User Industry (Oil and Gas, Water and Wastewater, Chemicals and Petrochemicals, Power Generation, Mining, and More), Driver Type (Electric-Motor Driven, Engine-Driven, and Solar-Powered), Installation (Surface Pumps, and Submersible Pumps), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
India Industrial Pump Market Trends and Insights
Government Capex Under the National Infrastructure Pipeline Accelerates Industrial Pump Demand
The INR 111 lakh crore National Infrastructure Pipeline (NIP) earmarked through 2025 has permanently changed pump procurement behaviour by embedding digital-performance requirements in every new utility, refinery upgrade, and industrial park. Public-private partnerships now expect suppliers to guarantee uptime metrics, pushing vendors to bundle Industrial IoT sensors, API 610 compliance, and long-term service contracts. Paradip refinery's INR 24,000 crore brown-field project illustrates the new norm, specifying remote diagnostics and predictive-maintenance dashboards with every pump skid. The model favours enterprises that maintain nationwide service crews and cloud-ready control platforms while elevating entry barriers for low-spec imports lacking data gateways or standardized protocols. As NIP disbursements progress, centrifugal pump retrofits give way to condition-based replacements, sustaining aftermarket revenue even after capital outlays taper.
Rapid Expansion of Wastewater Treatment Capacity Drives Specialized Pump Requirements
Wastewater coverage is slated to reach 70% by 2030 from 37% in 2024, triggering record procurement of corrosion-resistant, solids-handling pumps rated above 75% efficiency. Mumbai Metropolitan Region alone has budgeted INR 25,000 crore for decentralized sewage lifting and sludge dewatering, demanding more than 2,000 precision pumps able to operate unattended in corrosive environments. Operators now stipulate variable-frequency drives to match fluctuating influent loads, creating premium niches for manufacturers with metallurgy know-how and VFD bundles. Tightened Central Pollution Control Board norms further elevate demand for real-time monitoring and redundancy, placing centrifugal offerings with leak-free magnetic drives at a competitive edge.
Import Surge of Low-Cost Chinese Pumps Pressures Domestic Market Dynamics
Chinese models undercut domestic equivalents by 30-40%, capturing commodity water and HVAC orders and compressing gross margins. Shorter lead times and flexible credit terms lure SMEs, compelling Indian producers to automate fabrication and trim overhead. However, inconsistent after-sales service and spares unavailability offer incumbents a service-oriented counterpunch, especially as the Bureau of Indian Standards tightens ISI enforcement.
Other drivers and restraints analyzed in the detailed report include:
- Brown-field Expansion in Indian Refineries Creates High-Value Pump Opportunities
- Increasing Solar-Powered Pump Installations Transform Industrial Energy Economics
- High Total Cost of Ownership Constrains Market Expansion in Energy-Intensive Applications
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Centrifugal models commanded 65.02% of 2025 revenue of the India industrial pump market size, because they efficiently move large flows at moderate heads in water, cooling, and general process loops. Positive-displacement pumps, though only 34.98% of shipments, are set for a 6.79% CAGR by 2031, outstripping centrifugal's 3.95% pace as specialty chemical and pharma customers demand precise metering under variable viscosities. Vendors are closing the gap by adding magnetic drives and ceramic bearings to centrifugal lines, while PD makers push higher-speed, compact skids for brown-field retrofits. IoT retrofits blur lines further, letting operators benchmark efficiency in real time and switch technologies based on duty cycle analytics. Over the forecast, centrifugal unit volumes will still dwarf PD counts, yet PD value share will rise on premium pricing for exotic alloys and seamless architectures that curb fugitive emissions.
Water and wastewater accounted for 28.86% of the India industrial pump market share in 2025 on the back of Jal Jeevan and urban STP investments valued above INR 3.6 lakh crore. Mining, though only 8.40% of current sales, leads with a 7.18% CAGR as Coal India and steel majors increase mechanized output. Dewatering, slurry, and tailings lines call for abrasion-resistant elastomers and duplex stainless steels, lifting ASPs. Oil and gas remain a steady buyer through refinery upgrades, while chemicals leverage import-substitution policies to spur PD pump adoption. Regional clusters such as Chhattisgarh iron-ore belts or Odisha chromite pits will show double-digit spends, whereas mature thermal power plants mostly allocate capex for replacements rather than expansions.
Complete Report Scope:
- By Pump Type
- Centrifugal
- Positive-Displacement
- By End-user Industry
- Oil and Gas
- Water and Wastewater
- Chemicals and Petrochemicals
- Power Generation
- Mining
- Other End-User Industry
- By Driver Type
- Electric-motor Driven
- Engine-Driven (Diesel/CNG)
- Solar-Powered
- By Installation
- Surface Pumps
- Submersible Pumps
List of Companies Covered in this Report:
- Kirloskar Brothers Limited
- KSB SE and Co. KGaA (India)
- CRI Pumps Private Limited
- Grundfos Pumps India Private Limited
- Xylem Inc. (India)
- Shakti Pumps (India) Limited
- Crompton Greaves Consumer Electricals Limited
- CNP Pumps India Private Limited
- Falcon Pumps Private Limited
- Chemlin Pumps and Valves Private Limited
- La-Gajjar Machineries Private Limited
- Kishor Pumps Private Limited
- Unnati Pumps Private Limited
- V-Guard Industries Limited
- Flowserve India Controls Private Limited
- Sulzer Pumps India Private Limited
- Wilo Mather and Platt Pumps Private Limited
- Ebara Pumps India Private Limited
- ITT Goulds Pumps India Private Limited
- Roto Pumps Limited
- Netzsch Technologies India Private Limited
- Armstrong Fluid Technology (India) Private Limited
- Alfa Laval India Private Limited
- Peerless Pump India Private Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition - Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government cap-ex under National Infrastructure Pipeline (NIP)
- 4.2.2 Rapid expansion of wastewater treatment capacity
- 4.2.3 Brown-field expansion in Indian refineries
- 4.2.4 Increasing solar-powered pump installations in industries
- 4.2.5 Shift toward API 610/ISO 13709-compliant pumps
- 4.2.6 Industrial IoT-enabled predictive-maintenance adoption
- 4.3 Market Restraints
- 4.3.1 Import surge of low-cost Chinese pumps
- 4.3.2 High total cost of ownership (energy + maintenance)
- 4.3.3 Volatility in steel and copper prices
- 4.3.4 Lengthy approval cycles in public sector projects
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Pump Type
- 5.1.1 Centrifugal
- 5.1.2 Positive-Displacement
- 5.2 By End-user Industry
- 5.2.1 Oil and Gas
- 5.2.2 Water and Wastewater
- 5.2.3 Chemicals and Petrochemicals
- 5.2.4 Power Generation
- 5.2.5 Mining
- 5.2.6 Other End-User Industry
- 5.3 By Driver Type
- 5.3.1 Electric-motor Driven
- 5.3.2 Engine-Driven (Diesel/CNG)
- 5.3.3 Solar-Powered
- 5.4 By Installation
- 5.4.1 Surface Pumps
- 5.4.2 Submersible Pumps
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Kirloskar Brothers Limited
- 6.4.2 KSB SE and Co. KGaA (India)
- 6.4.3 CRI Pumps Private Limited
- 6.4.4 Grundfos Pumps India Private Limited
- 6.4.5 Xylem Inc. (India)
- 6.4.6 Shakti Pumps (India) Limited
- 6.4.7 Crompton Greaves Consumer Electricals Limited
- 6.4.8 CNP Pumps India Private Limited
- 6.4.9 Falcon Pumps Private Limited
- 6.4.10 Chemlin Pumps and Valves Private Limited
- 6.4.11 La-Gajjar Machineries Private Limited
- 6.4.12 Kishor Pumps Private Limited
- 6.4.13 Unnati Pumps Private Limited
- 6.4.14 V-Guard Industries Limited
- 6.4.15 Flowserve India Controls Private Limited
- 6.4.16 Sulzer Pumps India Private Limited
- 6.4.17 Wilo Mather and Platt Pumps Private Limited
- 6.4.18 Ebara Pumps India Private Limited
- 6.4.19 ITT Goulds Pumps India Private Limited
- 6.4.20 Roto Pumps Limited
- 6.4.21 Netzsch Technologies India Private Limited
- 6.4.22 Armstrong Fluid Technology (India) Private Limited
- 6.4.23 Alfa Laval India Private Limited
- 6.4.24 Peerless Pump India Private Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment