

|
시장보고서
상품코드
2124707
스페인의 전력 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Spain Power - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
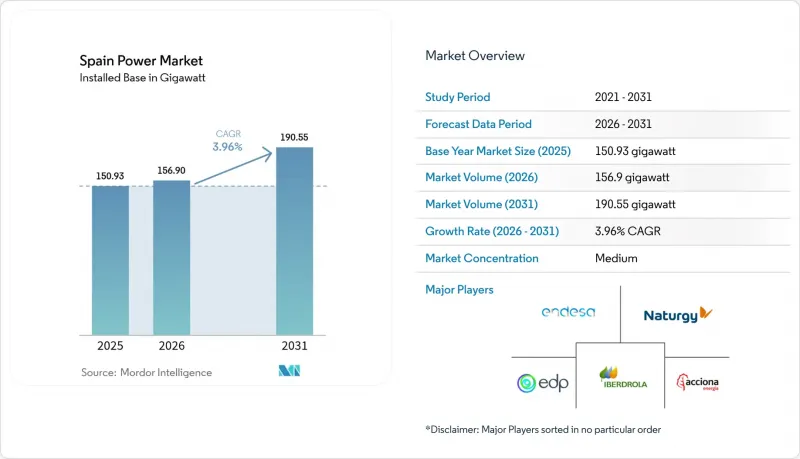
에 의하면, 스페인의 전력 시장 규모는 2025년 150.93기가와트로 평가되었습니다. 2026년에는 156.9기가와트로 확대되어 2026년부터 2031년에 걸쳐 CAGR 3.96%로 성장을 지속하여, 2031년에는 190.55기가와트에 이를 것으로 예측됩니다.
본 보고서는 동력원(화력, 원자력, 재생에너지), 최종 사용자(유틸리티, 상업 및 산업, 주택), T&D 전압 수준별로 분류되어 있습니다. 시장 규모 및 전망은 설비 용량(GW) 기준으로 제시되어 있습니다.
스페인의 전력 시장 동향 및 인사이트
계통 연계형 태양광 발전 도입 가속화
스페인의 태양광 발전 부문은 2024년에 가스 및 풍력을 제치고 국내 최대 전력원이 됨으로써 획기적인 전환점을 맞이했습니다. 당국은 2024년에 26,159.2 MW 규모의 재생에너지 건설을 승인했으며, 이 중 22,326.1 MW가 태양광 발전입니다. 이는 비용 하락, 허가 절차의 효율화, 그리고 기업들의 재생에너지 크레딧(REC) 수요를 뒷받침하는 것입니다. 카스티야 이 레온,아라곤, 카스티야-라만차 각 주는 우수한 일조 조건과 토지 확보가 유리하게 작용하여 최대 할당량을 확보했습니다. 마찬가지로, 산업단지 전역에서 분산형 옥상 태양광 발전 시스템이 급속히 보급되고 있으며, 이는 에너지 비용과 스코프 2 배출량 감축에 기여하고 있습니다. 대규모 발전소와 현장 발전 설비가 결합되어 스페인의 전력 시장 내 재생에너지 보급률을 높이고 있으며, 2030년까지 재생에너지 비율을 81%로 끌어올리겠다는 목표 달성이 수월해지고 있습니다.
하이퍼스케일 데이터센터의 진출이 주도하는 기업용 PPA
하이퍼스케일 플랫폼 수요가 스페인의 전력 시장의 수익 모델을 변화시키고 있습니다. 구글의 35MW 풍력 발전 PPA(10년), 아마존의 469MW 태양광 발전 도입 약속, 그리고 애플의 105MW 계약은 대형 기술 기업의 지원을 받은 개발업체들의 자금 조달 기반 건설로의 전환을 여실히 보여주고 있습니다. 데이터센터용량은 2026년에 600MW, 2030년까지 3,000MW에 달할 가능성이 있으며, 이로 인해 수 기가와트 규모의 재생에너지 개발 파이프라인이 유지될 전망입니다. PPA는 안정적인 현금 흐름과 자금 조달 비용 절감을 가져오고, 하이퍼스케일 기업의 넷제로 전략과도 부합하기 때문에 기존 전력회사의 조달량을 상회하는 설치량을 가속화하고 있습니다.
송전망 업그레이드를 위한 설비 투자(CAPEX) 확대
Red Electrica는 2026년까지 송전망 강화에 65억 유로를 예산으로 책정했으나, 2030년까지 100억 유로가 필요할 것으로 예상되어 35억 유로의 자금 부족이 발생하고 있습니다. 요금 상한제로 인해 연간 15%의 인상률로 제한되어 있어 비용 회수가 저해되고 있습니다. 변전소 건설에서는 부지 분쟁이 발생하고 있으며, 15곳의 400kV 시설 중 8곳이 법적 이의 제기로 인해 2년간의 지연을 피할 수 없게 되었습니다. 철강 및 구리 가격 급등으로 인해 송전선로 건설 비용은 2020년 km당 120만 유로에서 2024년에는 km당 180만 유로로 상승했습니다. 개혁이 이루어지지 않을 경우, 2028년까지 매년 5 TWh의 재생에너지 발전량이 감소하고, 태양광 발전의 실효 이용률은 22%까지 떨어질 가능성이 있습니다.
부문별 분석
2025년에는 재생에너지가 설비 용량의 67.10%를 차지했으며, 연평균 6.95%의 성장률에 힘입어 스페인의 청정 에너지 원에 의한 전력 시장 규모는 2025년 101.27 GW에서 2031년에는 150.66GW로 확대될 것이 확실합니다. 태양광 발전은 2025년 1월 기준 32.0 GW로 풍력 발전과 동등한 수준에 도달하여 풍력 발전을 추월했습니다. 이는 낮은 입찰 가격과 24%의 설비 가동률이 뒷받침한 결과입니다. 리파워링을 통해 새로운 부지를 확보하지 않고도 육상 풍력의 생산성이 향상되는 한편, 2 GW 규모의 부유식 해상 풍력 발전 임대 계약을 통해 미개척 해양 자원이 활용될 것입니다. 수력 발전은 17 GW로 정체 상태이지만, 저수지 수위 저하로 인해 피크 절감 능력이 제한받고 있습니다. 2027년까지 석탄 화력 발전에서 철수하고, 재생에너지를 위한 피크 대응용 비과세 용량으로 가스 화력 발전이 전환됨에 따라, 풍력이나 일사량이 적은 날에는 예비율이 더욱逼迫하게 될 것입니다.
2025년에는 화력 발전의 설비 용량에서 차지하는 비중이 25.80%로 낮아졌습니다. Endesa의 석탄 화력 단계적 폐지에 따라 2GW가 감축되었으며, CO2 배출량은 연간 1,200만 톤 감소했습니다. 복합 사이클 가스 발전의 총 용량은 24GW이지만, 재생에너지의 확대에 따라 가동 시간은 감소하고 있으며, 하이브리드형 축전 시스템을 통해 4시간의 출력 조정이 가능해졌습니다. 원자력 발전은 2035년까지 7.1GW로 정체 상태를 유지하겠지만, 그 후 발전소 폐쇄로 인해 50TWh공급 공백이 발생하여 이를 수입 또는 축전지로 보충해야 합니다. 바이오매스 발전은 순환형 경제에 대한 인센티브로 인해 1.2GW에서 2030년까지 1.8GW로 확대될 것으로 예측됩니다. 이러한 변화는 송전망의 유연성과 관련된 과제가 증가하는 상황 속에서도 스페인의 전력 시장이 어떻게 탈탄소 기술로 전환되고 있는지를 여실히 보여주고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the Spain power market size is expected to grow from 150.93 gigawatt in 2025 to 156.9 gigawatt in 2026 and is forecast to reach 190.55 gigawatt by 2031 at 3.96% CAGR over 2026-2031.
This report is Segmented by Power Source (Thermal, Nuclear, and Renewables) and End-User (Utilities, Commercial and Industrial, and Residential). The Market Sizes and Forecasts are Provided in Terms of Installed Capacity (GW).
Spain Power Market Trends and Insights
Accelerating Grid-Connected Solar PV Build-Out
Spain's solar segment set a watershed in 2024 when it overtook gas and wind as the country's top power source. Authorities cleared 26,159.2 MW of renewable construction in 2024, 22,326.1 MW of which is PV, underscoring cost declines, streamlined permitting, and corporate REC demand. Castilla y Leon, Aragon, and Castilla-La Mancha garnered the largest quotas, benefiting from superior irradiation and land availability. Distributed rooftop systems are likewise proliferating across industrial estates, cutting energy bills and Scope-2 emissions. Together, utility-scale and on-site arrays are raising the Spain electricity market's renewable penetration, easing compliance with the 81% green-power target for 2030.
Corporate PPAs Led by Hyperscale Data-Center Entrants
Demand from hyperscale platforms is reshaping revenue models in the Spain electricity market. Google's 35 MW, 10-year wind PPA, Amazon's 469 MW solar commitment, and Apple's 105 MW deal illustrate a shift toward developer-financed build-outs backstopped by tech majors. Data-center capacity could hit 600 MW in 2026 and 3,000 MW by 2030, sustaining multi-gigawatt renewable pipelines. PPAs provide bankable cash flows, lower financing costs, and dovetail with hyperscalers' net-zero strategies, accelerating installations beyond traditional utility procurement volumes.
Escalating Transmission Upgrade CAPEX
Red Electrica budgets EUR 6.5 billion for reinforcements through 2026, yet identifies a EUR 10 billion need by 2030, leaving a EUR 3.5 billion gap. Tariff caps limit annual hikes to 15%, throttling cost recovery. Substation builds face land disputes, with 8 of 15 400-kV facilities delayed two years by legal appeals. Steel and copper inflation pushed line costs from EUR 1.2 million /km in 2020 to EUR 1.8 million /km in 2024. Absent reform, 5 TWh of renewable output could be shed each year by 2028, trimming effective solar utilization to 22%.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Electrification of Mobility & Heating
- EU Fit-for-55 & NECP-2030 Decarbonisation Mandates
- Lengthy Environmental & Municipal Permitting
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Renewables accounted for 67.10% of installed capacity in 2025, and their 6.95% yearly advance ensures the Spain power market size for clean sources rises from 101.27 GW in 2025 to 150.66 GW in 2031. Solar photovoltaic eclipsed wind at 32.0 GW versus 32.0 GW in January 2025, propelled by low auction tariffs and 24% capacity factors. Repowering lifts onshore wind productivity without new land, while 2 GW of floating offshore leases open an untapped marine resource. Hydropower remains steady at 17 GW but suffers from lower reservoir levels that curb peak-shaving ability. Coal's exit by 2027 and gas's shift to peaking duty-free capacity for renewables will yet tighten reserve margins on low-wind, low-sun days.
Thermal fleets fell to 25.80% of capacity in 2025. Endesa's coal phase-out removed 2 GW, slashing 12 million tpy of CO2. Combined-cycle gas totals 24 GW but runs fewer hours as renewables scale, with hybrid storage enabling four-hour ramps. Nuclear stays flat at 7.1 GW through 2035, after which closures leave a 50 TWh gap to fill with imports or batteries. Biomass grows from 1.2 GW to a projected 1.8 GW by 2030 under circular-economy incentives. Together, this transformation underlines how the Spain power market pivots toward carbon-free technologies even as grid flexibility challenges mount.
Complete Report Scope:
- By Power Source
- Thermal (Coal, Natural Gas, Oil and Diesel)
- Nuclear
- Renewables (Solar, Wind, Hydro, Geothermal, Biomass & Waste, Tidal)
- By End User
- Utilities
- Commercial and Industrial
- Residential
- By T&D Voltage Level (Qualitative Analysis only)
- High-Voltage Transmission (Above 230 kV)
- Sub-Transmission (69 to 161 kV)
- Medium-Voltage Distribution (13.2 to 34.5 kV)
- Low-Voltage Distribution (Up to 1 kV)
List of Companies Covered in this Report:
- Endesa S.A.
- Iberdrola S.A.
- Naturgy Energy Group S.A.
- EDP Group (EDP HC Energia)
- Acciona Energia
- Repsol Electricidad y Gas
- Grupo Red Electrica
- Siemens Gamesa Renewable Energy
- Nordex SE
- TotalEnergies SE
- Enel Green Power Espana
- Vestas Mediterranean
- ABO Wind AG
- Engie Espana
- Capital Energy
- Forestalia Renovables
- Grenergy Renovables
- Hive Energy Spain
- Solarpack Corporacion Tecnologica
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating grid-connected solar PV build-out
- 4.2.2 Repowering of 1990s-2000s wind farms
- 4.2.3 Corporate PPAs led by hyperscale data-centre entrants
- 4.2.4 EU Fit-for-55 & NECP-2030 decarbonisation mandates
- 4.2.5 Rapid electrification of mobility & heating
- 4.2.6 EU funding for cross-border HVDC links
- 4.3 Market Restraints
- 4.3.1 Escalating transmission upgrade CAPEX
- 4.3.2 Lengthy environmental & municipal permitting
- 4.3.3 Rising curtailment risk in resource-rich regions
- 4.3.4 Local opposition to on-shore wind siting
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 PESTLE Analysis
5 Market Size & Growth Forecasts
- 5.1 By Power Source
- 5.1.1 Thermal (Coal, Natural Gas, Oil and Diesel)
- 5.1.2 Nuclear
- 5.1.3 Renewables (Solar, Wind, Hydro, Geothermal, Biomass & Waste, Tidal)
- 5.2 By End User
- 5.2.1 Utilities
- 5.2.2 Commercial and Industrial
- 5.2.3 Residential
- 5.3 By T&D Voltage Level (Qualitative Analysis only)
- 5.3.1 High-Voltage Transmission (Above 230 kV)
- 5.3.2 Sub-Transmission (69 to 161 kV)
- 5.3.3 Medium-Voltage Distribution (13.2 to 34.5 kV)
- 5.3.4 Low-Voltage Distribution (Up to 1 kV)
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Endesa S.A.
- 6.4.2 Iberdrola S.A.
- 6.4.3 Naturgy Energy Group S.A.
- 6.4.4 EDP Group (EDP HC Energia)
- 6.4.5 Acciona Energia
- 6.4.6 Repsol Electricidad y Gas
- 6.4.7 Grupo Red Electrica
- 6.4.8 Siemens Gamesa Renewable Energy
- 6.4.9 Nordex SE
- 6.4.10 TotalEnergies SE
- 6.4.11 Enel Green Power Espana
- 6.4.12 Vestas Mediterranean
- 6.4.13 ABO Wind AG
- 6.4.14 Engie Espana
- 6.4.15 Capital Energy
- 6.4.16 Forestalia Renovables
- 6.4.17 Grenergy Renovables
- 6.4.18 Hive Energy Spain
- 6.4.19 Solarpack Corporacion Tecnologica
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


