

|
시장보고서
상품코드
2124709
구강 점막 흡수 약물 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Oral Transmucosal Drugs - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 구강 점막 흡수 약물 시장 규모는 2025년에 176억 9,000만 달러로 평가되었습니다. 2026년 188억 7,000만 달러에서 2031년까지 260억 5,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 6.66%를 나타낼 전망입니다.
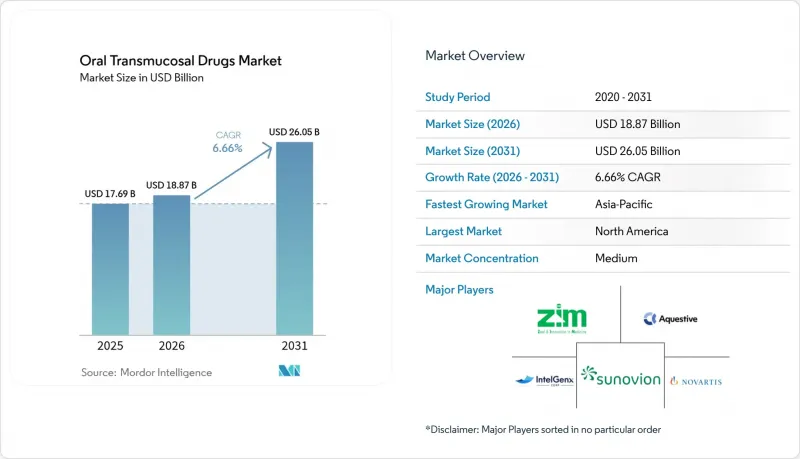
본 보고서에서는 시장을 제품 유형별(설하정, 구강점막정 등), 투여 경로별(설하 점막, 구강 점막 등), 적응증별(오피오이드 의존증 등), 유통 채널별(병원 약국, 소매 약국, 온라인 약국 및 전문 약국), 그리고 지역별로 분류하고 있습니다. 시장 규모 및 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 구강 점막 흡수 약물 시장 동향 및 인사이트
중추신경계(CNS) 질환 및 통증성 질환의 부담 증가
오피오이드 사용 장애, 간질 및 암으로 인한 돌발성 통증의 유병률 증가로 인해, 구강 점막 투과형 제제에 대한 수요가 뒷받침되고 있습니다. 2025년 FDA가 비오피오이드계 구강 점막용 진통제 수제트리긴을 승인한 것은 보다 안전한 진통 대체 약물에 대한 규제 당국의 지지를 보여주는 것입니다. Libervant가 소아용 승인을 획득함에 따라 소아 군발성 발작에 대한 요구를 충족시키고, 벤조디아제핀계 약물을 이용한 신속한 응급 처치의 대상 연령 범위가 확대되었습니다. 연하 곤란을 겪는 고령자 증가로 인해, 물 없이 용해되는 필름 제제나 스프레이 제제에 대한 처방 경향이 더욱 강해지고 있습니다. 이러한 역학적 요인과 편의성이 결합되어 구강 점막 흡수 약물 시장의 장기적인 성장 궤도를 뒷받침하고 있습니다.
2023년 이후의 연구개발 파이프라인 및 승인 건수의 급증
2023년 이후, 획기적인 치료제 및 희귀질환 의약품 심사 지정이 확대됨에 따라 심사 주기가 단축되었습니다. 그 예로 편두통 치료제 RizaFilm, 고용량 제품의 승인이 가능하도록 한 부프레노르핀 투여 지침의 개정을 들 수 있습니다. Atai Life Sciences의 DMT 구강 점막 필름과 같은 환각제 계열 후보 약물은 2상 임상시험 단계로 진입했으며, 이는 중추신경계(CNS)의 새로운 적응증이 후기 개발 단계에 접어들었음을 시사합니다. 승인 절차의 신속화는 투자를 촉진하고 시장의 성장 곡선을 끌어올리고 있습니다.
약제 함량 제한 및 맛 마스킹 과제
필름 제제는 용해성을 저해하지 않으면서 유효 성분을 수 밀리그램 이상 함유하는 경우가 드물며, 이 제형은 강력한 분자로 제한되어 있습니다. 부프레노르핀과 같은 쓴맛이 나는 원료의약품(API)에는 고도의 쓴맛 마스킹 기술이 필요하며, 이로 인해 개발 기간이 연장되고 비용이 증가하고 있습니다. 제제 개발자들은 침투 촉진제의 평가를 진행하고 있지만, 새로운 첨가제 모두가 독성학적 과제에 직면해 있어, 이것이 승인 지연이나 단기적인 시장 성장의 걸림돌이 될 가능성이 있습니다.
부문별 분석
2025년, 설하정은 확고한 처방 관행과 광범위한 보험 적용을 배경으로 시장 규모의 41.98%를 차지했습니다. 그러나 필름의 지속적인 혁신에 힘입어, 구강 내 용해 정제는 2031년까지 연평균 성장률(CAGR) 7.12%를 나타낼 것으로 예측되며, 이는 천천히 용해되어 투여 빈도를 줄여주는 소아용 제제에 의해 주도되고 있습니다. 구강 내 분해 필름은 PharmFilm 기술의 혜택을 받아 난용성 분자의 생체 이용률을 높이며, 편두통 및 정신 질환 파이프라인에서 활용되고 있습니다. 액상 제제 및 스프레이 제제는 아나필락시스 및 신생아 경련에 대한 응급 치료 틈새 시장을 개척하고 있는 반면, 약용 과자는 만성 질환의 복약 순응도 향상에 기여하고 있습니다. 40°C의 상온 보관이 가능한 온도 안정성을 갖춘 정제는 열대 지역에서의 접근성을 확대되고 있습니다.
정제가 주류를 이루고 있지만, 각 제조업체는 점막 부착성 고분자를 접목하여 체류 시간을 연장하고 침투성을 높이고 있습니다. 필름 제제는 대부분의 경우 2분 이내에 신속한 통증 완화를 가져오기 때문에 돌발성 통증 발작에 대해 전략적인 역할을 수행하고 있습니다. 신흥 시장 수요 증가에 따라, 콜드체인의 부담을 줄여주는 상온 보관이 가능한 블리스터 팩에 대한 투자가 진행되고 있습니다. 이러한 제품의 다양성이 결합되어 구강 점막 흡수 약물 시장 전체의 성장 모멘텀을 유지하고 있습니다.
설하 투여 경로는 전신 흡수를 촉진하는 풍부한 혈관 분포 덕분에 2025년 구강 점막 흡수 약물 시장에서 35.22%의 점유율을 차지했습니다. 구강 점막 투여는 기분 안정제나 진통제 등 더 긴 접촉 시간이 필요한 치료에 대응함으로써 2031년까지 연평균 7.70%의 성장률을 보이고 있습니다. 혀 표면 및 잇몸 경로는 국소적인 치주통이나 표적 호르몬 요법에 대응하는 등 여전히 특수한 용도로만 사용되고 있습니다.
담즙산 유도체 등의 투과 촉진제를 통해, 기존에는 주사가 필요했던 펩타이드의 구강 점막을 통한 흡수가 향상되고 있습니다. 뺨에 부착되는 점막 접착형 패치는 8시간 이상 혈장 농도를 유지하여 추가 투여 빈도를 줄여줍니다. 생체이용률에 관한 데이터가 축적됨에 따라 처방집상의 적용 범위가 확대되고 있으며, 이는 구강 점막 흡수 약물 시장에서 볼 점막 투여법의 성장 추세를 뒷받침하고 있습니다.
지역별 분석
북미는 획기적인 치료법으로서의 승인 절차와 광범위한 보험 적용 범위의 혜택을 받아 2025년에는 매출의 42.10%를 차지했습니다. FDA가 2024년에 부프레노르핀의 최대 투여량 제한을 철폐함에 따라, 오피오이드 사용 장애 치료 프로그램에서 약물 유지 효과를 높이는 고용량 필름 제제의 개발이 촉진되고 있습니다. 미국의 주요 간질 치료 센터에서의 산학 협력을 통해 소아 임상시험 피험자 모집이 가속화되어, 이 지역의 리더십이 확고해지고 있습니다. 아시아태평양은 2031년까지 연평균 성장률(CAGR) 8.52%로 가장 높은 성장을 기록할 전망입니다. 중국 국가의약품감독관리국은 심사 신속화를 시행하여 2024년에 통증 및 종양학용 점막 투과 제제를 포함한 60종 이상의 혁신 의약품을 승인했습니다. 수탁 제조업체인 WuXi STA의 펩타이드 및 고효능 필름 생산에 대한 투자는 이 지역의 규모적 우위를 부각시키고 있습니다. 아세안(ASEAN)의 규제 조화 노력은 국경을 초월한 시장 진입을 촉진하고 잠재적 환자 수를 확대되고 있습니다. 유럽에서는 소아에게 적합한 제형을 장려하는 유럽의약품청(EMA)의 소아용 시판 허가를 배경으로 꾸준한 성장을 유지하고 있습니다. 최근 승인된 Buprenorphine Neuraxpharm은 성숙한 적응증 분야에서 지속적인 혁신을 상징합니다. 각국의 의료 제도에서 경구 정제보다 복약 순응도가 높은 것으로 입증된 필름 제제에 대한 보험 급여가 확대되고 있습니다. 중동, 아프리카 및 남미에서는 온도 안정성이 뛰어난 필름 제제가 콜드체인의 과제를 극복함으로써 판매량이 점진적으로 증가할 것으로 전망됩니다. 오피오이드 중독 대책으로 경구 점막 흡수형 나록손 필름을 비축하는 인도적 지원 프로그램을 통해 초기 시장 입지가 확립되었으며, 경제 상황이 개선되면 향후 성장 여지가 기대됩니다. 이러한 지역적 다각화가 맞물려 구강 점막 흡수 약물 시장의 지속적인 확장을 뒷받침하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the oral transmucosal drugs market size was valued at USD 17.69 billion in 2025 and estimated to grow from USD 18.87 billion in 2026 to reach USD 26.05 billion by 2031, at a CAGR of 6.66% during the forecast period (2026-2031).
This report Segments the Industry Into by Product Type (Sublingual Tablets, Buccal Tablets, and More), by Route of Administration (Sublingual Mucosa, Buccal Mucosa, and More), by Indication (Opioid Dependence, and More), by Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies), and Geography. The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Oral Transmucosal Drugs Market Trends and Insights
Growing burden of CNS and pain disorders
Rising prevalence of opioid use disorder, epilepsy, and breakthrough cancer pain sustains demand for fast-acting transmucosal options. The FDA approval of buccal non-opioid pain drug suzetrigine in 2025 signals regulator support for safer pain alternatives . Pediatric seizure-cluster needs were addressed when Libervant received pediatric approval, broadening age coverage for rapid benzodiazepine rescue. Aging populations with dysphagia further tilt prescribing toward films and sprays that dissolve without water. Together, epidemiology and usability reinforce the long-run trajectory of the oral transmucosal drugs market.
Post-2023 surge in R&D pipelines and approvals
Expanded breakthrough and orphan-drug designations after 2023 shortened review cycles. Examples include RizaFilm for migraine and the re-scoped buprenorphine dosing guidance that cleared higher-strength products. Psychedelic candidates such as atai Life Sciences' DMT buccal film advanced to Phase 2, pointing to novel CNS indications entering late-stage development. Faster approvals encourage investment, lifting the market growth curve.
Limited drug-load and taste-masking challenges
Films rarely exceed a few milligrams of active ingredient without compromising dissolution, restricting the modality to potent molecules. Bitter APIs such as buprenorphine demand sophisticated flavor-blocking that lengthens development and raises cost . Formulators are evaluating permeation enhancers, yet every new excipient faces toxicology hurdles that may delay approvals and weigh on near-term market growth.
Other drivers and restraints analyzed in the detailed report include:
- Patient preference for needle-free, swallow-free dosing
- Rapid adoption of transmucosal rescue in EMS protocols
- Patent cliffs for first-generation opioid-dependence films
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Sublingual tablets held 41.98% share of oral transmucosal drugs market size in 2025 on the strength of established prescribing habits and broad reimbursement. Continuous film innovation, however, allows buccal tablets to register a 7.12% CAGR to 2031, propelled by pediatric formulations that dissolve slowly and reduce dosing frequency. Oro-dispersible films benefit from PharmFilm technology, giving poorly soluble molecules higher bioavailability in migraine and psychiatric pipelines. Liquids and sprays carve out rescue niches for anaphylaxis and neonatal seizures, while medicated confectionaries improve compliance in chronic settings. Temperature-stable tablet formats targeting 40°C ambient storage broaden access in tropical regions.
Although tablets dominate, manufacturers integrate mucoadhesive polymers to extend retention time and enhance permeation. Films deliver rapid relief-often within two minutes-making them strategic for breakthrough pain episodes. Elevated demand in emerging markets encourages investment in ambient-stable blister packs that reduce cold-chain burden. Collectively, product diversity maintains growth momentum across the oral transmucosal drugs market.
The sublingual pathway commanded 35.22% oral transmucosal drugs market share in 2025 thanks to rich vascularization that speeds systemic uptake. Buccal delivery grows 7.70% annually through 2031 by catering to therapies that require longer contact time, such as mood stabilizers and analgesics. Lingual and gingival routes remain specialized, addressing localized periodontal pain or targeted hormone therapy.
Permeation enhancers such as bile-salt derivatives improve buccal absorption of peptides that previously required injection. Mucoadhesive patches anchored to the cheek maintain plasma levels over eight hours, reducing rescue-dose frequency. As bioavailability data build, formularies are widening coverage, reinforcing the upward path for buccal applications in the oral transmucosal drugs market.
Complete Report Scope:
- By Product Type
- Sublingual Tablets
- Buccal Tablets
- Oro-dispersible Films
- Buccal Films
- Liquids & Sprays
- Medicated Confectionaries (Lozenges, Lollipops, Gums)
- Others (Patches, Gels)
- By Route of Administration
- Sublingual Mucosa
- Buccal Mucosa
- Lingual
- Gingival
- By Indication
- Opioid Dependence
- Seizure Clusters & Epilepsy
- Pain / Oncology Pain
- Nausea & Vomiting
- Erectile Dysfunction
- Others
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online & Specialty Pharmacies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America contributed 42.10% revenue in 2025, benefiting from breakthrough-therapy pathways and wide insurance coverage. The FDA's 2024 update removing buprenorphine dose ceilings has encouraged higher-strength films that enhance retention in opioid-use-disorder programs. Academic-industry collaborations at leading U.S. epilepsy centers speed recruitment for pediatric trials, consolidating the region's leadership.Asia-Pacific registers the fastest 8.52% CAGR through 2031. China's National Medical Products Administration implemented accelerated reviews that cleared more than 60 innovative drugs in 2024, including transmucosal formulations for pain and oncology. Investment in peptide and high-potency-film production by contract manufacturer WuXi STA underscores the region's scale advantage. Regulatory harmonization initiatives in ASEAN facilitate cross-border market entry, expanding total addressable patients.Europe maintains steady growth on the back of the European Medicines Agency Pediatric-Use Marketing Authorization, which encourages child-friendly formulations. Recent approval of Buprenorphine Neuraxpharm illustrates ongoing innovation within mature indications . National health systems increasingly reimburse films that demonstrate superior adherence over oral tablets.Middle East & Africa and South America deliver incremental volume where temperature-stable films bypass cold-chain gaps. Humanitarian programs that stock oral transmucosal naloxone films for opioid toxicity build early market presence, offering future upside once economic conditions improve. Combined, geographic diversification supports sustained expansion of the oral transmucosal drugs market.
- Aquestive Therapeutics
- Intelgenx
- ZIM Laboratories
- C.L. Pharm Co., Ltd.
- Novartis
- Sunovion Pharmaceuticals
- Pfizer
- GW Pharmaceuticals (Jazz)
- Seoul Pharmaceuticals
- Shilpa Therapeutics
- Indivior
- Cure Pharmaceutical
- Catalent
- Takeda Pharmaceuticals
- Dr. Reddy's Laboratories
- Glenmark Pharmaceuticals
- AdhexPharma
- Astellas Pharma
- BioDelivery Sciences (Collegium)
- Johnson & Johnson
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Burden Of Target CNS And Pain Disorders
- 4.2.2 Surge In R&D Pipelines & Regulatory Approvals Post-2023
- 4.2.3 Preference For Needle-Free, Swallow-Free Dosage Forms Among Geriatrics & Paediatrics
- 4.2.4 Rapid Take-Up Of Transmucosal Rescue Therapies In Community Ems Protocols
- 4.2.5 Micro-Dose Psychedelic & Cannabinoid Films Entering Phase-Ii Pipelines
- 4.2.6 Temperature-Stable Film Formulations Supporting Low-Cold-Chain Markets
- 4.3 Market Restraints
- 4.3.1 Limited Drug-Load & Taste-Masking Challenges
- 4.3.2 Patent Cliffs For First-Generation Opioid Dependence Films
- 4.3.3 Emerging Competition From Intranasal Powder Auto-Injectors
- 4.3.4 Persistent Fda Concerns On Paediatric Dosing Uniformity For High-Potency Apis
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook (Films, muco-adhesive polymers, permeation enhancers)
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD million)
- 5.1 By Product Type
- 5.1.1 Sublingual Tablets
- 5.1.2 Buccal Tablets
- 5.1.3 Oro-dispersible Films
- 5.1.4 Buccal Films
- 5.1.5 Liquids & Sprays
- 5.1.6 Medicated Confectionaries (Lozenges, Lollipops, Gums)
- 5.1.7 Others (Patches, Gels)
- 5.2 By Route of Administration
- 5.2.1 Sublingual Mucosa
- 5.2.2 Buccal Mucosa
- 5.2.3 Lingual
- 5.2.4 Gingival
- 5.3 By Indication
- 5.3.1 Opioid Dependence
- 5.3.2 Seizure Clusters & Epilepsy
- 5.3.3 Pain / Oncology Pain
- 5.3.4 Nausea & Vomiting
- 5.3.5 Erectile Dysfunction
- 5.3.6 Others
- 5.4 By Distribution Channel
- 5.4.1 Hospital Pharmacies
- 5.4.2 Retail Pharmacies
- 5.4.3 Online & Specialty Pharmacies
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Aquestive Therapeutics
- 6.3.2 IntelGenx Corp.
- 6.3.3 ZIM Laboratories
- 6.3.4 C.L. Pharm Co., Ltd.
- 6.3.5 Novartis AG
- 6.3.6 Sunovion Pharmaceuticals
- 6.3.7 Pfizer Inc.
- 6.3.8 GW Pharmaceuticals (Jazz)
- 6.3.9 Seoul Pharmaceuticals
- 6.3.10 Shilpa Therapeutics
- 6.3.11 Indivior PLC
- 6.3.12 Cure Pharmaceutical
- 6.3.13 Catalent Inc.
- 6.3.14 Takeda Pharmaceutical
- 6.3.15 Dr. Reddy's Laboratories
- 6.3.16 Glenmark Pharmaceuticals
- 6.3.17 AdhexPharma
- 6.3.18 Astellas Pharma
- 6.3.19 BioDelivery Sciences (Collegium)
- 6.3.20 Johnson & Johnson (Janssen)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


