

|
시장보고서
상품코드
2124739
일회용 바이오프로세싱 프로브 및 센서 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Single-Use Bioprocessing Probes And Sensors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
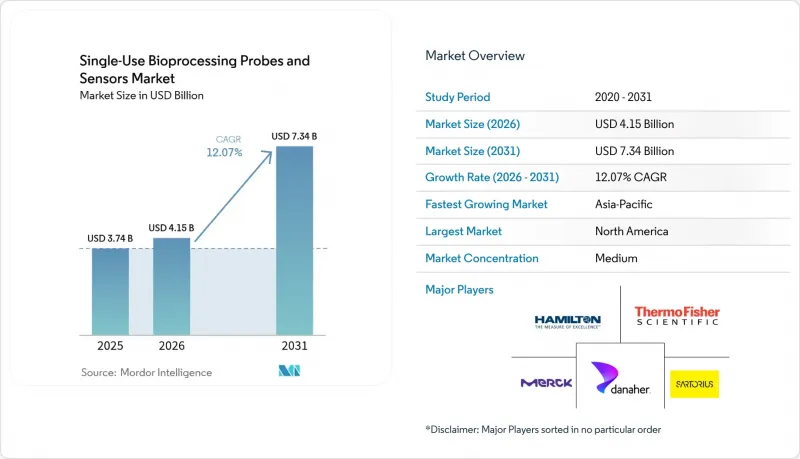
에 의하면, 일회용 바이오프로세싱 프로브 및 센서 시장 규모는 2025년 37억 4,000만 달러로 평가되었고, 2026년에는 41억 5,000만 달러로 추정되고, 2031년까지 73억 4,000만 달러에 이를 것으로 예상되며, 2026-2031년 CAGR 12.07%로 성장할 전망입니다.
본 보고서는 센서 유형별(pH, 용존 산소, 전도도, 온도, 압력, 유량), 감지 기술별(광학식 등), 멸균 방식별(감마선 등), 용도별(업스트림 바이오프로세스 등), 최종 사용자별(바이오의약품·제약 기업 등), 지역별(북미 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 일회용 바이오프로세싱 프로브 및 센서 시장 동향과 인사이트
바이오의약품 제조 분야에서 일회용 기술의 급속한 보급
바이오의약품 파이프라인은 고정식 스테인리스 인프라로는 분자의 다양화에 대응할 수 없기 때문에 일회용 시스템으로 전환되고 있습니다. 화이자(Pfizer)는 2025년에는 임상용 바이오의약품의 60%에서 일회용 제품이 사용되었으며(2022년 38%에서 증가), 2028년까지 공정 분석 관련 지출의 75%를 일회용 센서가 차지할 것으로 예측했습니다. 항체-약물 복합체(ADC)를 제조하는 시설에서는 세포 독성 잔류물을 제거하기 위해 표면을 폐기해야 하므로 일회용 제품이 선호됩니다. 사전 교정 및 방사선 조사된 센서는 이 모델에 부합하며, 전환 시간을 5일에서 24시간 미만으로 단축합니다. FDA의 2024년 연속 제조 지침에 따라 공장 내 교정이 공식적으로 인정됨에 따라, 과거 재사용 가능한 프로브를 선호했던 규정 준수상의 장벽이 해소되었습니다.
유연한 모니터링이 필요한 세포 및 유전자 치료 파이프라인의 확대
자가 CAR-T 제조에서는 환자별로 개별 배치를 병렬로 처리하지만, 각각에 대해 개별적인 pH 및 용존 산소 모니터링이 필요합니다. 노바티스(Novartis)는 2025년에 전 시설에서 월 340세트의 일회용 센서를 도입할 것이라고 보고했는데, 이는 2023년 도입량의 약 3배에 해당합니다. 모든 반응조에 재사용 가능한 프로브를 설치하면 스위트당 120만 달러의 설비 투자가 필요하지만, 반면 소모품 비용은 월 8만 5,000달러로 충분하며, 검증 작업도 필요하지 않습니다. 바이러스 벡터 제조업체의 경우, 부착 배양에는 유선 프로브로는 대응할 수 없는 분산형 센싱이 필요하기 때문에 복잡성이 더욱 커지지만, 무선 일회용 프로브라면 쉽게 대응할 수 있습니다.
재사용 가능한 프로브에 비해 높은 단가
일회용 용존 산소 센서는 배치당 180-280달러의 비용이 들지만, 재사용 가능한 유닛은 초기 비용 3,200달러를 지불한 후 배치당 12달러로 상각됩니다. Genentech의 바카빌(Vacaville) 사업장과 같은 연속 생산 시설에서는 일회용 센서로 전환할 경우 연간 900만 달러의 추가 비용이 발생하게 됩니다. 2025년에는 원자재 가격 급등으로 인해 사이클로올레핀 코폴리머 가격이 18% 상승하여 그 격차는 더욱 확대되었습니다.
부문 분석
pH 센서는 2025년 일회용 바이오프로세싱 프로브 및 센서 시장 매출의 34.43%를 차지했으며, 시드 트레인에서 제형화에 이르는 전 공정에 걸친 보편적인 수요를 반영하고 있습니다. 광학식 및 다중 매개변수형 장치는 제조업체가 여러 측정값을 적은 수의 포트에 통합함으로써 하드웨어 비용과 검증 부담을 줄이고 있어 연평균 성장률(CAGR) 15.23%로 증가하고 있습니다. 기존의 유리 전극은 고밀도 관류 배양에서 오염이 발생하기 쉬우므로, 형광 광학식 pH 센서가 부상하고 있습니다. 용존 산소 센서는 호기성 포유류 배양에서 여전히 필수적이며, 젖산 프로브와 통합됨으로써 대사 프로파일을 파악할 수 있게 됩니다. 유량 및 압력 센서는 자기 부상식 설계를 통해 입자를 방출하는 씰을 제거함으로써, 다운스트림 공정인 크로마토그래피에 혁신을 가져오고 있습니다.
Sartorius가 2025년에 포트 수를 줄여 비용을 22% 절감하는 pH·용존 산소·온도 복합 프로브를 출시함에 따라, 3가지 매개변수를 지원하는 일회용 바이오프로세싱 프로브 및 센서 시장 규모는 급속히 확대될 것으로 예측됩니다. 압력 센서의 혁신에는 고유량 여과 시 백 파열을 방지하는 버스트 디스크의 통합이 포함되어 있으며, 또한 정전용량식 프로브는 오프라인 생존 세포 수와 95%의 상관관계를 보여줌으로써 실시간 세포 밀도 제어를 지원하고 있습니다.
2025년 매출에서 전기화학식 장치가 56.13%를 차지했으나, 광학식 장치는 비침습적이며 여러 분석 대상 물질을 모니터링할 수 있어 연평균 성장률(CAGR) 14.89%가 예상됩니다. 라만 분광법은 포도당, 젖산, 암모니아, 글루타민을 동시에 측정하여 배치당 40-60회의 오프라인 샘플링을 불필요하게 만들어 기술자의 작업 시간을 단축합니다. 해밀턴(Hamilton)의 2025년 조사에 따르면, 12개의 검증 배치에서 라만 분광법을 통해 효능의 편차가 14% 감소했습니다. 한편, 근적외선 센서는 한외여과 중 단백질 농도를 추적하여 수동 시료 채취로 인한 오염을 방지합니다.
광학 시스템 하드웨어 비용은 80,000-12만 달러인 반면, 전기화학식 장치는 8,000달러이지만, 인건비 절감과 더 정밀한 제어를 통해 총 소유 비용(TCO)의 균형을 맞추고 있습니다. ISFET pH 센서는 소형 폼 팩터와 전기화학 방식의 간편함을 겸비한 하이브리드형이며, Endress+Hauser는 2025년에 최초의 감마선 멸균 대응 모델을 출하했습니다.
지역별 분석
북미는 매사추세츠주, 노스캐롤라이나주, 캘리포니아주에 CMO(수탁 제조 기업)의 생산 능력이 집중되어 있어 2025년 매출의 37.82%를 차지했습니다. 2025년에 12건의 세포 치료제가 FDA 승인을 받음에 따라 급속한 설비 확충이 진행되고 있으며, 신제품 1개당 연간 최대 400만 달러의 센서 소비가 예상됩니다. 현재, 국내 조달 촉진 정책에 따라 조립 공정이 사우스캐롤라이나주로 이전되면서 납기 기간이 6주로 단축되었습니다.
아시아태평양은 중국의 120억 달러 규모 바이오 제조 추진과 싱가포르가 지역 내 세포 치료 임상시험의 거점으로 부상한 것을 배경으로, 2031년까지 연평균 성장률(CAGR) 14.77%를 나타낼 것으로 예측됩니다. Autobio Diagnostics와 Mindray Medical은 2025년, 수입품보다 최대 40% 저렴한 가격으로 감마선 멸균이 가능한 센서를 출시하여 현지에서의 보급을 가속화했습니다. Lonza, Thermo Fisher, Merck는 싱가포르에서 유럽 및 미국의 센서 사양을 준수하는 GMP 복합 시설을 운영하고 있으며, 이로 인해 고품질 광학 장치에 대한 수요가 발생하고 있습니다.
유럽에서는 지속가능성과 관련된 역풍에 직면해 있습니다. 유럽의약품청(EMA)이 마련한 수명 주기 평가(LCA) 초안에 따라 일부 프로젝트에서는 재사용 가능한 프로브로의 회귀가 진행되고 있습니다. Sartorius는 2025년, 전자 부품을 회수하여 재활용하는 센서 회수 프로그램을 도입하여 환경에 미치는 영향을 40% 줄였습니다. 기타에도 GCC 국가들에서는 바이오테크놀러지 파크에 대한 자금 지원이 진행되고 있으며, 브라질에서의 백신 생산 확대가 전기화학식 기반 센서 수요를 완만하게 끌어올리고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the single-Use bioprocessing probes and sensors market size is expected to increase from USD 3.74 billion in 2025 to USD 4.15 billion in 2026 and reach USD 7.34 billion by 2031, growing at a CAGR of 12.07% over 2026-2031.
This report is Segmented by Sensor Type (pH, Dissolved Oxygen, Conductivity, Temperature, Pressure, Flow), Detection Technology (Optical, and More), Sterilization Compatibility (Gamma, and More), Application (Upstream, and More), End User (Biopharma, and More), and Geography (North America, and More). Market Forecasts are Provided in Terms of Value (USD).
Global Single-Use Bioprocessing Probes And Sensors Market Trends and Insights
Rapid Adoption of Single-Use Technologies in Biologics Manufacturing
Biologics pipelines are shifting to single-use systems because fixed stainless infrastructure cannot flex with rising molecule diversity. Pfizer noted that 60% of its clinical biologics used disposables in 2025, up from 38% in 2022, and predicts single-use sensors will command 75% of its process-analytics spend by 2028. Facilities producing antibody-drug conjugates prefer disposables because surfaces must be discarded to eliminate cytotoxic residue. Pre-calibrated, irradiated sensors align with this model and compress changeovers from five days to less than 24 hours. FDA's 2024 continuous-manufacturing guidance legitimized factory calibration, erasing a compliance roadblock that once favored reusable probes.
Expanding Pipeline of Cell & Gene Therapies Demanding Flexible Monitoring
Autologous CAR-T manufacturing runs patient-specific batches in parallel, each needing separate pH and dissolved-oxygen monitoring. Novartis reported deploying 340 single-use sensor sets per month across its facilities in 2025, nearly triple 2023 volume. Installing reusable probes in every vessel would lock in USD 1.2 million in capital per suite, versus a monthly USD 85,000 consumables bill with no validation labor. Viral-vector producers add complexity because adherent cultures demand distributed sensing that wired probes cannot supply, but wireless disposables manage with ease.
High Per-Unit Cost Versus Reusable Probes
A single-use dissolved-oxygen sensor costs USD 180-280 per batch, while a reusable unit amortizes at USD 12 per batch after the USD 3,200 upfront spend. Continuous facilities such as Genentech's Vacaville site would incur a USD 9 million annual penalty by going disposable. Raw material inflation pushed cyclic olefin copolymer prices up 18% in 2025, widening the gap.
Other drivers and restraints analyzed in the detailed report include:
- Growth of CMOs/CDMOs Accelerating Disposable-Probe Procurement
- Standardization of Single-Use Sensor Formats by Industry Consortia
- Environmental Concerns over Single-Use Plastic Waste
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
pH sensors held 34.43% of 2025 revenue within the single-use bioprocessing probes and sensors market, reflecting universal demand from seed train through formulation. Optical and multi-parameter devices are rising at a 15.23% CAGR as manufacturers fold multiple readings into fewer ports, reducing hardware cost and validation burden. Traditional glass electrodes foul in high-density perfusion cultures, so fluorescent optical pH alternatives are gaining ground. Dissolved-oxygen sensors remain vital for aerobic mammalian cultures, with integration into lactate probes to complete metabolic profiles. Flow and pressure sensors are shaking up downstream chromatography as magnetically levitated designs eliminate seals that shed particles.
The single-use bioprocessing probes and sensors market size for tri-parameter devices is projected to expand swiftly following Sartorius' 2025 release of a combined pH-DO-temperature probe that trims port count and slash costs 22%. Pressure-sensor innovation includes burst-disc integration, preventing bag rupture during high-flow filtration, and capacitance probes now correlate 95% with offline viable-cell counts, supporting real-time cell-density control.
Electrochemical devices delivered 56.13% of 2025 revenue, but optical formats are slated for 14.89% CAGR because they offer non-invasive, multi-analyte monitoring. Raman spectroscopy measures glucose, lactate, ammonia, and glutamine simultaneously, eliminating 40-60 offline samples per batch and trimming technician hours. Hamilton's 2025 study showed Raman cut titer variability by 14% in 12 validation batches. Near-infrared sensors, meanwhile, track protein concentration during ultrafiltration to avoid contamination from manual sampling.
Optical hardware costs USD 80,000-120,000 versus USD 8,000 for electrochemical suites, yet the labor savings and tighter control tilt total cost of ownership. ISFET pH sensors represent a hybrid, offering small form factor with electrochemical simplicity, and Endress+Hauser shipped the first gamma-sterilizable model in 2025.
Complete Report Scope:
- By Sensor Type
- pH Sensors
- Dissolved Oxygen Sensors
- Conductivity Sensors
- Temperature Sensors
- Pressure Sensors
- Flow Sensors & Meters
- By Detection Technology
- Optical (fluorescence, Raman, NIR)
- Electrochemical (potentiometric, amperometric, ISFET)
- Capacitive / Piezo-resistive
- Other / Hybrid
- By Sterilization Compatibility
- Gamma-irradiable Sensors
- X-ray / E-beam-sterilizable Sensors
- Autoclavable / Steam-in-Place Sensors
- Non-sterilizable, Pre-sterilized Sensors
- By Application
- Upstream Bioprocessing
- Downstream Bioprocessing
- Quality Control & Assurance
- Research & Development
- By End User
- Biopharmaceutical & Pharmaceutical Companies
- Contract Manufacturing & Development Organizations (CMOs/CDMOs)
- Academic & Research Institutes
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 37.82% of 2025 revenue thanks to concentrated CMO capacity in Massachusetts, North Carolina, and California. FDA approvals of 12 cell therapies in 2025 triggered rapid build-outs, with each new product demanding up to USD 4 million in annual sensor consumption. Domestic-content incentives now pull assembly into South Carolina, trimming delivery times to six weeks.
Asia-Pacific is forecast to post a 14.77% CAGR through 2031 on the back of China's USD 12 billion biomanufacturing push and Singapore's emergence as a hub for regional cell-therapy trials. Autobio Diagnostics and Mindray Medical launched competitively priced gamma-sterilizable sensors in 2025 that undercut imports by up to 40%, accelerating local uptake. Lonza, Thermo Fisher, and Merck operate GMP complexes in Singapore that mirror Western sensor specifications, creating demand for premium optical devices.
Europe faces sustainability headwinds. EMA's draft mandate for life-cycle assessments is steering some projects back toward reusable probes. Sartorius introduced a sensor take-back scheme in 2025 that recovers electronics for refurbishment, slicing environmental impact by 40%. Elsewhere, GCC states are funding biotech parks, and Brazil's vaccine expansion is fueling modest sensor demand anchored in electrochemical formats.
- Aber Instruments
- Applikon Biotechnology
- Broadley-James
- Danaher
- Emerson Electric (Rosemount)
- Endress+Hauser Group
- Eppendorf
- Getinge
- Hamilton Company
- Levitronix
- Malema Engineering
- Meissner Filtration Products
- Merck
- Mettler Toledo
- Parker Hannifin
- PendoTECH
- Polestar Technologies
- PreSens Precision Sensing
- Repligen
- Saint-Gobain Life Sciences
- Sartorius
- Sensirion
- Thermo Fisher Scientific
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Adoption of Single-Use Technologies in Biologics Manufacturing
- 4.2.2 Expanding Pipeline of Cell & Gene Therapies Demanding Flexible Monitoring
- 4.2.3 Growth of CMOs/CDMOs Accelerating Disposable-Probe Procurement
- 4.2.4 Standardization of Single-Use Sensor Formats by Industry Consortia
- 4.2.5 Integration of Disposable Sensors with Digital Twins & Real-Time Analytics
- 4.2.6 Tariff-Driven Regionalization of Sensor Supply Chains
- 4.3 Market Restraints
- 4.3.1 High Per-Unit Cost Versus Reusable Probes
- 4.3.2 Environmental Concerns over Single-Use Plastic Waste
- 4.3.3 Supply-Chain Volatility of Medical-Grade Polymers & Optical Components
- 4.3.4 Calibration-Data Integrity Challenges in GMP Audits
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts ( Value in USD)
- 5.1 By Sensor Type
- 5.1.1 pH Sensors
- 5.1.2 Dissolved Oxygen Sensors
- 5.1.3 Conductivity Sensors
- 5.1.4 Temperature Sensors
- 5.1.5 Pressure Sensors
- 5.1.6 Flow Sensors & Meters
- 5.2 By Detection Technology
- 5.2.1 Optical (fluorescence, Raman, NIR)
- 5.2.2 Electrochemical (potentiometric, amperometric, ISFET)
- 5.2.3 Capacitive / Piezo-resistive
- 5.2.4 Other / Hybrid
- 5.3 By Sterilization Compatibility
- 5.3.1 Gamma-irradiable Sensors
- 5.3.2 X-ray / E-beam-sterilizable Sensors
- 5.3.3 Autoclavable / Steam-in-Place Sensors
- 5.3.4 Non-sterilizable, Pre-sterilized Sensors
- 5.4 By Application
- 5.4.1 Upstream Bioprocessing
- 5.4.2 Downstream Bioprocessing
- 5.4.3 Quality Control & Assurance
- 5.4.4 Research & Development
- 5.5 By End User
- 5.5.1 Biopharmaceutical & Pharmaceutical Companies
- 5.5.2 Contract Manufacturing & Development Organizations (CMOs/CDMOs)
- 5.5.3 Academic & Research Institutes
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 France
- 5.6.2.3 United Kingdom
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Aber Instruments
- 6.3.2 Applikon Biotechnology
- 6.3.3 Broadley-James Corporation
- 6.3.4 Danaher Corporation
- 6.3.5 Emerson Electric (Rosemount)
- 6.3.6 Endress+Hauser Group
- 6.3.7 Eppendorf AG
- 6.3.8 Getinge AB
- 6.3.9 Hamilton Company
- 6.3.10 Levitronix
- 6.3.11 Malema Engineering Corporation
- 6.3.12 Meissner Filtration Products
- 6.3.13 Merck KGaA
- 6.3.14 Mettler Toledo
- 6.3.15 Parker Hannifin
- 6.3.16 PendoTECH
- 6.3.17 Polestar Technologies
- 6.3.18 PreSens Precision Sensing
- 6.3.19 Repligen Corporation
- 6.3.20 Saint-Gobain Life Sciences
- 6.3.21 Sartorius AG
- 6.3.22 Sensirion AG
- 6.3.23 Thermo Fisher Scientific
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-need assessment


