

|
시장보고서
상품코드
2124744
플렉스 연료 차량 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Flex-fuel Vehicle - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 플렉스 연료 차량 시장 규모는 1조 1,028억 8,000만 달러로 추정되고, 2025년 1조 1,300억 달러에서 축소될 전망입니다.
또한, 2031년의 예측치는 9,761억 2,000만 달러로 예상되며, 2026-2031년 연평균 성장률(CAGR)은 -2.4%를 기록할 전망입니다.
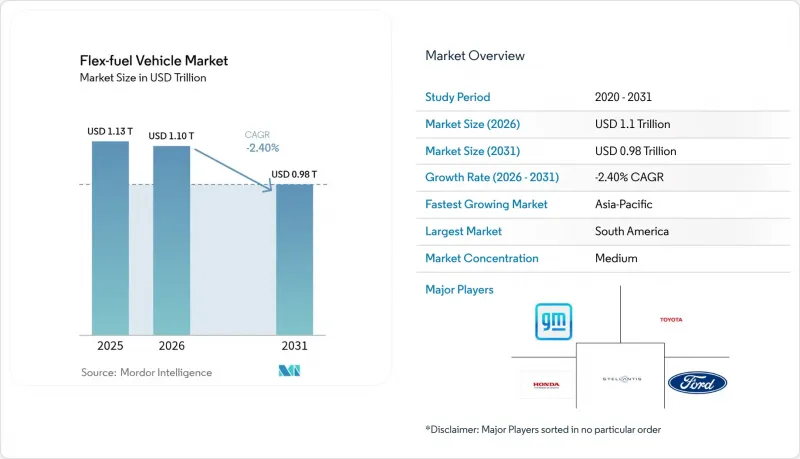
본 보고서는 에탄올 혼합 유형별(E-10-E-25, E-25-E-85, E-85 이상), 차량 유형별(승용차, 소형 상용차, 대형 상용차), 연료 유형별(가솔린, 디젤 대응 듀얼 연료), 판매 채널별(OEM 순정 장착, 애프터마켓용 변환 키트), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 플렉스 연료 차량 시장 동향 및 인사이트
개발도상국에서의 E-10/E-15 세계 확산
인도, 인도네시아, 필리핀에서 혼합 비율 의무화가 확대됨에 따라, 정책 입안자들이 에너지 안보와 농업 소득 다각화를 추구하는 가운데 에탄올 수요가 증가하고 있습니다. 인도가 2026년까지 5분의 1의 혼합 비율 달성을 목표로 하는 움직임에 따라, 이 나라는 옥수수 수출국에서 순수입국으로 전환되고 있으며, 그 결과 전 세계 원료 공급이 부족해지고 있습니다. 2030년까지 E-10, 2040년까지 E-20 도입을 위한 일본의 로드맵은 전기차 인프라가 확대되는 가운데 내연기관의 선택지를 유지하려는 아시아 전체의 협력적 전략을 부각시키고 있습니다. 가금류·축산 부문과의 원료 경쟁으로 인해 투입 가격이 상승하고 있어, 연료 정책과 식량 안보 사이의 미묘한 균형이 드러나고 있습니다. 국영 석유 회사는 물류 및 가격 책정에서 여전히 중요한 역할을 수행하며, 지역적 유통 제약을 완화하는 데 기여하고 있습니다. 이러한 프로그램들은 전반적으로 배기가스 내 CO2 배출량을 단계적으로 감축하고 있지만, 전기차에 대한 인센티브가 동시에 시행되는 가운데 플렉스 연료 차량 시장의 축소를 막지는 못하고 있습니다.
브라질 RenovaBio의 탄소 크레딧 프리미엄
RenovaBio는 에탄올 공급망의 효율성 향상으로 인한 모든 증분 효과를 금전적 가치로 환산하는 수명 주기 기반의 탄소 크레딧 벤치마크를 설정하고 있습니다. 저탄소 CBIO 인증 프리미엄은 2025년 초에 CO2e 톤당 115달러에 달했으며, 사탕수수와 옥수수를 원료로 하는 에탄올 공장에 수익성 높은 수입원을 제공합니다. 브라질 중서부 지역의 확장으로 인해 이미 25곳의 옥수수 에탄올 공장이 가동 중이며, 추가로 15곳이 건설 중이므로 2024/25년 수확기의 총 생산량은 82억 리터에 달할 전망입니다. 이 정책의 기술 중립적 프레임워크는 업계 최고 수준의 생산자들에게 유리하게 작용하며, 정밀 농업에 대한 투자와 폐열 회수 시스템을 장려하고 있습니다. ‘미래 연료법’에 따라 페트로브라스(Petrobras)가 고농도 에탄올 혼합 연료를 지지한 것은 이러한 방향에 대한 국가의 지속적인 지원을 시사합니다. RenovaBio는 설탕 가격에 연동되는 수익 변동을 완화하지만, 전기차로의 거시적인 전환 추세를 완전히 상쇄할 수는 없습니다.
유럽 및 중국의 전기차 보급 목표 가속화
유럽연합(EU)의 2035년 내연기관 차량 판매 금지 및 중국에서 상향 조정되고 있는 신에너지차(NEV) 할당량으로 인해, 자동차 제조업체들의 투자는 완전한 전동화로 방향을 전환하고 있습니다. 중국 브랜드는 2023년 기준 EU 내 배터리 전기차 판매 대수의 7.9%를 차지했으며, 2027년까지 20%를 차지할 가능성이 있어 경쟁 압력이 더욱 고조되고 있습니다. 유럽의 전기차 시장은 2030년까지 기하급수적으로 성장할 것으로 예측되며, 이는 바이오연료 플랫폼에서 자본을 빨아들이는 자금의 자석 역할을 하고 있습니다. 중국의 비용 우위로 인해 플렉스 연료 전략은 경제적으로 열세에 놓인 것으로 보이며, 정책, 인프라, 소비자 선호도가 상호 작용하는 선순환을 강화하고 있습니다. 공공 충전 네트워크가 확대됨에 따라 주행 거리 불안감이 줄어들면서, 플렉스 연료의 경쟁력은 더욱 약화되고 있습니다. 이러한 억제요인은 플렉스 연료 차량 시장의 연평균 성장률(CAGR)에서 가장 큰 단일 요인을 차감하게 될 것입니다.
부문 분석
E-25-E-85 카테고리는 2025년에 플렉스 연료 차량 시장 규모의 48.55%를 차지했으나, 2031년까지 연평균 성장률(CAGR) -2.30%로 축소될 것으로 예측됩니다. 중간 정도의 혼합 비율을 가진 연료는 고가의 하드웨어 변경이 필요하지 않고 기존 주유소의 펌프와 엔진 보정 기능을 활용할 수 있기 때문에 보급이 확대되고 있습니다. 브라질의 E30 휘발유 도입은 이러한 최적의 균형에 부합하며, 에탄올 함유율 변화에 원활하게 적응하는 2,000만 대의 차량을 활용하고 있습니다. 캘리포니아주에서 E85 소매 판매가 급증한 것은 경제적으로 허용되는 경우 지역별 과세 및 가격 인센티브가 운전자들을 더 높은 농도의 바이오연료 혼합 연료로 유도할 수 있음을 여실히 보여줍니다. 그러나 조사에 따르면, E30은 저속 영역에서 조기 점화 제어의 전환점에 위치해 있으며, 에탄올 농도를 더욱 높이면 엔진 매핑이 복잡해지고 콜드 스타트 시의 위험이 커집니다. 이러한 실용적인 한계가 OEM의 설계 선택을 이끌고 있으며, 전환 기간 동안 중농도 혼합 연료가 업계 표준으로 자리 잡고 있습니다.
E85를 초과하는 고농도 혼합 연료는 재생 가능 연료의 함유율을 극대화하는 한편, 전용 연료 공급망이 필요하고 에너지 밀도 저하로 인해 주행 거리가 단축된다는 단점이 있습니다. E10이나 E15와 같은 엔트리 레벨 혼합 연료는 아직 공급망이 발전 단계에 있는 시장을 지원하지만, 탄소 감축 효과가 제한적이기 때문에 엄격한 배기가스 규제 목표 하에서는 전략적 매력이 떨어집니다. 현재의 계층 구조는 전동화가 가속화되고 있는 상황에서도, 지속가능성과 인프라 현실 사이에서 실용적인 절충점을 보여주고 있습니다. 전반적으로, 생산량이 많은 지역에서 휘발유와의 가격 차이가 매력적인 수준을 유지하는 한, 2031년까지 25%에서 85%의 에탄올 혼합 연료가 플렉스 연료의 보급을 계속 주도할 것입니다.
승용차는 2025년 매출의 64.52%를 차지했으나, 상용차 부문보다 완만한 연평균 성장률(CAGR)인 -2.18%로 감소할 전망입니다. 특히 에탄올이 저렴하게 거래되는 지역에서 소비자가 연료 선택지를 중시하는 경향이 기준선 수요를 뒷받침하고 있습니다. 브라질의 소형차 부문에서는 여전히 플렉스 연료 차량이 표준 사양으로 간주되는 반면, 인도의 Tata Punch Flex Fuel은 비용 중심 시장에서도 혁신의 가능성을 보여주고 있습니다. 소형 상용 밴은 적재량에 대한 수요와 내연기관에 대한 규제를 강화하기 시작한 도시 지역의 규제 사이에서 균형을 맞추며 중간적인 위치를 차지하고 있습니다. 대조적으로, 대형 트럭과 버스는 차량 운영 사업자들이 장기적인 운영 비용 절감이 기대되는 배터리식 전기차나 수소 모델로 자본을 전환하고 있기 때문에 가장 빠르게 감소하고 있습니다.
승용차 부문의 높은 회복력은 분산형 급유 체계와 개인의 가격 차익 거래 행동에 기인하며, 이는 집중형 차량 대여 조달에서는 볼 수 없는 특징입니다. 오토바이는 새로운 틈새 시장으로 부상하고 있으며, 혼다는 동남아시아에서 국내산 에탄올을 사용할 수 있는 플렉스 대응 엔진을 도입하고 있습니다. 그러나 도시 지역의 대기 오염 규제 강화와 교통 혼잡 요금 도입으로 인해 전기 스쿠터 및 소형 전기차로의 전환이 가속화될 가능성이 높습니다. 그 결과, 승용차는 플렉스 연료 차량 시장에서 판매 대수 기준 1위를 유지하겠지만, 이 부문의 전략적 중요성은 향후 10년 동안 감소할 것으로 예측됩니다.
지역별 분석
2025년에는 4만 개 이상의 소매 주유 펌프와 견조한 CBIO 탄소 크레딧 시장을 포함한 브라질의 통합 에탄올 생태계에 힘입어 남미가 42.10%의 점유율로 1위를 차지했습니다. 이 나라의 미래 연료법에 따라 의무 혼합 비율이 35%로 상향 조정됨에 따라 국내 수요는 견조한 추세를 보이고 있습니다. 한편, 옥수수 유래 에탄올 생산의 확대에 따라 원료 조달 리스크 분산이 진행되고 있습니다. 스텔란티스(Stellantis)의 56억 유로 규모의 바이오 하이브리드 투자는 이 지역이 에탄올과 전기의 시너지 효과를 입증하는 살아있는 실험장으로서의 역할을 하고 있음을 뒷받침합니다. 아르헨티나와 파라과이는 사탕수수 유래 에탄올을 수입하여 수요를 보완하고 있으며, 공급망의 경제성을 안정시키는 지역 무역 허브로서의 역할을 수행하고 있습니다.
아시아태평양은 적극적인 혼합 정책이 시행되고 있음에도 불구하고, 2031년까지의 연평균 성장률(CAGR)이 -2.23%로 가장 빠르게 축소되고 있는 지역입니다. 중국에서는 신에너지차(NEV) 보급에 국가적으로 주력하고 있는 데다, 배터리식 전기 트럭에 대한 지방 자치 단체의 보조금까지 더해져 플렉스 연료에 대한 투자가 억제되고 있습니다. 인도의 에탄올 프로그램은 옥수수 수입 증가에 따라 원료 조달 측면에서 역풍에 직면하여 비용 경쟁력이 저하되고 있습니다. 일본의 E-10 도입 공약은 정책적 확실성을 제공하고 있지만, 국내 자동차 제조업체들은 고체 배터리 연구개발에 주력하고 있어 틈새 시장인 스포츠 모델 외의 플렉스 연료 차량 생산은 제한적입니다. 동남아시아 국가들에서는 B40 바이오디젤 및 에탄올 시범 사업이 검토되고 있지만, 전기차에 대한 인센티브가 도시권 소비자층을 서서히 끌어들이기 시작하고 있습니다.
북미에서는 45Z 크레딧에 힘입어 대규모 에탄올 생산 능력이 유지되고 있지만, 자동차 제조업체들이 신제품 파이프라인을 전기차 플랫폼에 집중하고 있어 시장 침투율은 정체 상태입니다. 캘리포니아주의 무공해차 의무화는 이러한 전환을 가속화하고 있습니다. 유럽에서도 유사한 경향이 관찰됩니다. 독일이 2035년 이후 e-연료에 대한 예외 조치를 추진하고 있음에도 불구하고, 규제 패키지는 구매자들을 압도적으로 BEV로 유도하고 있습니다.
아프리카 및 중동에서는 식량 안보 및 경제 다각화와 연계된 연료 다각화 전략이 소폭의 기회를 창출하고 있지만, 인프라 부족과 구매력의 한계가 광범위한 보급을 저해하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, flex-fuel vehicle market size in 2026 is estimated at USD 1102.88 billion, growing from 2025 value of USD 1130 billion with 2031 projections showing USD 976.12 billion, growing at -2.4% CAGR over 2026-2031.

This report is Segmented by Ethanol Blend Type (E-10 To E-25, E-25 To E-85, E-85 and Above), Vehicle Type (Passenger Cars, Light Commercial Vehicles, and Heavy Commercial Vehicles), Fuel Type (Gasoline and Diesel-Compatible Dual-Fuel), Sales Channel (OEM-Fitted and Aftermarket Conversion Kits), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Flex-fuel Vehicle Market Trends and Insights
E-10/E-15 global roll-outs in developing nations
Expanding blend mandates across India, Indonesia, and the Philippines are elevating ethanol demand as policymakers seek energy security and farm-income diversification. India's push toward one-fifth blending by 2026 is turning the country from a corn exporter into a net importer, thereby tightening global feedstock supply. Japan's roadmap for E-10 by 2030 and E-20 by 2040 underscores a coordinated Asian strategy that preserves internal-combustion options while EV infrastructure scales. Feedstock competition with poultry and livestock sectors is lifting input prices, exposing the delicate balance between fuel policy and food security. National oil companies remain critical facilitators of logistics and pricing, helping mitigate regional distribution constraints. Collectively, these programs deliver incremental tail-pipe CO2 cuts but struggle to reverse the flex-fuel vehicle market contraction amid simultaneous EV incentives.
Brazilian RenovaBio carbon-credit premiums
RenovaBio sets life-cycle-based carbon-credit benchmarks that monetize every incremental efficiency gain along the ethanol supply chain. Premiums for low-carbon CBIO certificates reached USD 115 per tonne-CO2e in early 2025, adding profitable revenue streams to sugarcane and corn ethanol plants. Expansion in Brazil's Center-West has already spawned 25 operating corn-ethanol mills with another 15 under construction, lifting total output to 8.2 billion liters for the 2024/25 harvest. The policy's technology-neutral framework favors best-in-class producers, incentivizing precision-agriculture inputs and waste-heat recovery systems. Petrobras' endorsement of higher ethanol blends under the "Fuel of the Future" law signals sustained state-backed support for the pathway. While RenovaBio softens revenue volatility tied to sugar prices, it cannot fully offset the macro shift toward electric alternatives.
Accelerated EV adoption targets in Europe & China
The European Union's 2035 combustion ban and China's escalating NEV quotas are redirecting automaker investment toward full electrification. Chinese brands already occupied 7.9% of EU battery-electric sales in 2023 and may capture 20% by 2027, amplifying competitive pressure. The European EV market is forecast to grow exponentially by 2030, a financial magnet that drains capital from biofuel platforms. China's cost advantage makes flex-fuel strategies appear economically inferior, reinforcing a feedback loop of policy, infrastructure, and consumer preference. As public charging networks expand, range anxiety wanes, further eroding flex-fuel defensibility. The restraint subtracts the largest single share from the flex-fuel vehicle market CAGR.
Other drivers and restraints analyzed in the detailed report include:
- Cellulosic-ethanol price inflection after U.S. 45Z credit
- OEM flex-strategy to hedge EV policy uncertainty
- OEM cap-ex re-allocation toward BEV platforms
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The E-25 to E-85 category held 48.55% of flex-fuel vehicle market size in 2025 and is forecast to slip at a -2.30% CAGR to 2031. Moderate blends thrive on existing filling-station pumps and engine calibrations that avoid costly hardware changes. Brazil's evaluation of E30 gasoline aligns with this sweet spot, leveraging a 20-million-vehicle fleet that seamlessly adapts to varying ethanol content. California's rapid E85 retail sales underscore how regional taxation and price incentives can nudge drivers toward higher biofuel mixes when economics allow. Yet research indicates E30 sits at the inflection point for low-speed pre-ignition control, where further ethanol raises engine-mapping complexity and cold-start risk. This practical ceiling guides OEM design choices and keeps mid-range blends the industry's default during the transition period.
High blends above E85, while showcasing maximum renewable content, demand dedicated fuel networks and carry energy-density penalties that erode driving range. Entry-level blends such as E10 or E15 aid markets that are still developing supply chains, but they deliver limited carbon reduction, reducing their strategic appeal under stringent emissions goals. The current hierarchy signals a pragmatic compromise between sustainability and infrastructural reality, even as electrification gains traction. Overall, ethanol blends between 25% and 85% will continue to dominate flex-fuel adoption through 2031, provided price differentials against gasoline remain attractive in high-production regions.
Passenger cars generated 64.52% of 2025 revenue and will taper at a slower -2.18% CAGR than commercial segments. Consumer preference for fuel choice, especially where ethanol trades at a discount, sustains baseline demand. Brazil's compact-car segment still counts flex-fuels as the default configuration, while India's Tata Punch Flex Fuel showcases innovation potential even in cost-sensitive markets. Light-commercial vans occupy an intermediate position, balancing payload needs with urban-zone regulations that are starting to penalize combustion engines. In contrast, heavy-duty trucks and buses are declining fastest as fleet operators shift capital toward battery-electric and hydrogen models that promise long-term operating savings.
The resilience of the passenger car cohort stems from decentralized refueling and individual price arbitrage behavior, both absent in centralized fleet procurement. Motorcycles offer an emerging niche, with Honda introducing flex-compatible engines that can utilize domestic ethanol streams in Southeast Asia. Still, rising urban clean-air rules and congestion charges are likely to accelerate the migration toward electric scooters and compact EVs. Consequently, passenger cars will preserve volume leadership in the flex-fuel vehicle market, yet the segment's strategic importance is expected to diminish over the next decade.
Complete Report Scope:
- By Ethanol Blend Type
- E-10 to E-25
- E-25 to E-85
- E-85 and Above
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- By Fuel Type
- Gasoline
- Diesel-compatible Dual-Fuel
- By Sales Channel
- OEM-fitted
- Aftermarket Conversion Kits
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
South America led with 42.10% share in 2025, powered by Brazil's integrated ethanol ecosystem, which includes more than 40,000 retail pumps and a robust CBIO carbon-credit market. The country's "Fuel of the Future" law raising mandatory blends to 35% keeps domestic demand buoyant, while corn-ethanol expansion diversifies feedstock risk. Stellantis' EUR 5.6 billion Bio-Hybrid investment underscores the region's role as a living laboratory for ethanol-electric synergy. Argentina and Paraguay supplement demand by importing sugarcane ethanol, anchoring a regional trade hub that stabilizes supply-chain economics.
Asia-Pacific, despite active blending policies, is the fastest-declining bloc at -2.23% CAGR through 2031. China's national focus on NEV roll-outs, coupled with provincial subsidies for battery-electric trucks, constrains flex-fuel investments. India's ethanol program faces feedstock headwinds as corn imports grow, dampening cost competitiveness. Japan's E-10 pledge provides policy certainty, but domestic automakers are channeling R&D into solid-state batteries, limiting flex-fuel output beyond niche sports models. Southeast Asian nations are exploring B40 biodiesel and ethanol pilots, yet EV incentives are starting to capture the urban consumer segment.
North America retains large ethanol production capacity supported by the 45Z credit, yet market penetration is flat because OEMs aim new product pipelines at electric platforms. California's zero-emission vehicle mandate accelerates this swing. Europe shows similar patterns: notwithstanding Germany's push for e-fuels carve-outs post-2035, the regulatory package overwhelmingly steers buyers toward BEVs.
In the Middle East and Africa, fuel diversification strategies tied to food-security and economic diversification provide modest openings, but infrastructure gaps and limited purchasing power restrain widespread uptake.
- Stellantis NV
- Volkswagen AG
- General Motors Co.
- Ford Motor Co.
- Toyota Motor Corp.
- Honda Motor Co.
- Hyundai Motor Co.
- Kia Corp.
- Nissan Motor Co.
- Renault SA
- Subaru Corp.
- BMW AG
- Volvo Car Corp.
- Tata Motors Ltd.
- Mahindra & Mahindra Ltd.
- SAIC Motor Corp.
- Great Wall Motor Co.
- Geely Automobile Holdings
- JAC Motors
- Changan Automobile
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 E-10/E-15 Global Roll-Outs In Developing Nations
- 4.2.2 Brazilian Renovabio Carbon-Credit Premiums
- 4.2.3 Cellulosic-Ethanol Price Inflection After U.S. 45Z Credit
- 4.2.4 OEM Flex-Strategy To Hedge EV Policy Uncertainty
- 4.2.5 Next-Gen Port-Fuel-Injection Kits For Legacy Fleets
- 4.2.6 Ethanol-Compatible After-Treatment Cost Deflation
- 4.3 Market Restraints
- 4.3.1 Accelerated EV Adoption Targets In Europe & China
- 4.3.2 OEM Cap-Ex Re-Allocation Toward BEV Platforms
- 4.3.3 Limited Ethanol Feed-Stock In Drought-Prone Geographies
- 4.3.4 Cold-Start Emission Spikes In Sub-Zero Climates
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Ethanol Blend Type
- 5.1.1 E-10 to E-25
- 5.1.2 E-25 to E-85
- 5.1.3 E-85 and Above
- 5.2 By Vehicle Type
- 5.2.1 Passenger Cars
- 5.2.2 Light Commercial Vehicles
- 5.2.3 Heavy Commercial Vehicles
- 5.3 By Fuel Type
- 5.3.1 Gasoline
- 5.3.2 Diesel-compatible Dual-Fuel
- 5.4 By Sales Channel
- 5.4.1 OEM-fitted
- 5.4.2 Aftermarket Conversion Kits
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 France
- 5.5.3.3 United Kingdom
- 5.5.3.4 Spain
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Stellantis NV
- 6.4.2 Volkswagen AG
- 6.4.3 General Motors Co.
- 6.4.4 Ford Motor Co.
- 6.4.5 Toyota Motor Corp.
- 6.4.6 Honda Motor Co.
- 6.4.7 Hyundai Motor Co.
- 6.4.8 Kia Corp.
- 6.4.9 Nissan Motor Co.
- 6.4.10 Renault SA
- 6.4.11 Subaru Corp.
- 6.4.12 BMW AG
- 6.4.13 Volvo Car Corp.
- 6.4.14 Tata Motors Ltd.
- 6.4.15 Mahindra & Mahindra Ltd.
- 6.4.16 SAIC Motor Corp.
- 6.4.17 Great Wall Motor Co.
- 6.4.18 Geely Automobile Holdings
- 6.4.19 JAC Motors
- 6.4.20 Changan Automobile
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


