|
시장보고서
상품코드
2124749
세포배양 배지 백 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Cell Culture Media Bags - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
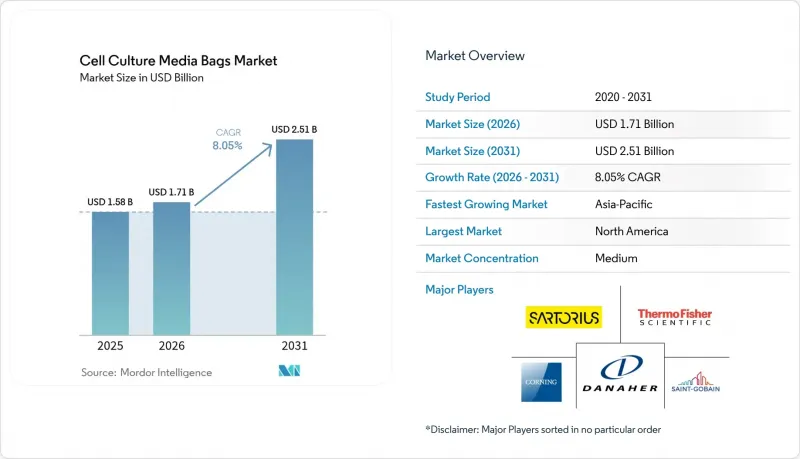
에 의하면, 2026년 세포배양 배지 백 시장 규모는 17억 1,000만 달러로 추정되며, 2025년 15억 8,000만 달러에서 확대해, 2031년에는 25억 1,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 8.05%가 될 것으로 전망됩니다.
본 보고서는 설계별(2D 백, 3D 백 등), 소재별(EVA, LDPE 등), 용량별(5L 미만, 5-50L, 기타), 용도별(바이오의약품 제조, 백신 제조, 기타), 최종 사용자별(CDMO/CRO, 제약·바이오기술 기업, 기타), 지역별(북미, 유럽, 기타)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 세포배양 배지 백 시장 동향 및 인사이트
바이오의약품 및 단일클론 항체(mAB) 생산 파이프라인의 확대
Fujifilm Diosynth의 16억 달러 규모의 덴마크 확장 등, 단일클론 항체의 생산 능력 증강은 대용량 세포배양 배지 백 시장 솔루션에 대한 수요 규모를 부각시키고 있습니다. 고역가 공정에서는 배양 기간이 길어지고 단백질 농도도 상승하기 때문에 추출물의 축적에 내성이 있는 내구성이 높은 백 필름이 필요합니다. 항체-약물 복합체(ADC) 제조에서는 오염 관리에 대한 요구가 더욱 높아지고 있어, 사전 멸균된 일회용 어셈블리로의 전환이 가속화되고 있습니다. 임상시험이 중국과 인도 등지로 지리적으로 다각화됨에 따라, FDA 및 EMA의 요건을 충족하면서도 지역별 조달 기회가 생겨나고 있습니다.
일회용 바이오프로세스 시스템의 급속한 보급
전환 시간이 수 주에서 48시간으로 단축되고 세척 요건도 완화됨에 따라, 일회용 시스템은 다중 제품을 취급하는 CDMO에게 매우 매력적인 선택지가 되고 있습니다. 생애주기 평가에 따르면, 스테인리스 스틸에 비해 전반적인 환경 부하가 적은 것으로 밝혀져 일회용 제품에 대한 오해가 해소되고 있습니다. 세포 및 유전자 치료제 제조업체들은 자가 유래 배치 간의 교차 오염을 줄이기 위해 일회용 시스템이 필수적이라고 여기고 있으며, 퍼퓨전 및 강화 공정에 대응하는 맞춤형 백 형태에 대한 수요가 증가하고 있습니다.
오염 및 용출물 위험과 경질 용기와의 비교
bDtBPP와 같은 세포 독성 화합물의 발견으로 인해 엄격한 추출물 시험이 다시 중요시되고 있으며, FDA는 허용 위험 임계값을 재정의하는 지침을 발표했습니다. USP(88)에서 USP(87)/(665)로의 전환으로 인해 적합성 평가 비용이 증가하고 있어 가격은 비싸지긴 하지만, 공급업체들은 불소 수지 라이닝이 적용된 백의 개발을 추진하고 있습니다.
부문 분석
2025년 현재, 2D 필름은 세포배양 배지 백 시장의 52.58%를 차지했으며, 이는 시드 트레인 및 완충액 조제 작업에서 기존에 가졌던 우위를 반영한 것입니다. 그러나 3D 형식은 강화형 퍼퓨전 및 상업 규모의 바이러스 벡터 스위트에서의 강력한 채택에 힘입어 연평균 성장률(CAGR) 10.05%로 확대되고 있습니다. 유연한 입방체 형태는 바닥 면적을 절약하면서 혼합 및 물질 이동 속도를 향상시킵니다. 이러한 특성은 전산유체역학(CFD) 연구를 통해 입증되었습니다. EVA 코어 층과 불소 수지의 접촉면을 결합한 하이브리드 다층 구조 제품은 고효능 바이오의약품 및 세포 치료용 배치를 대상으로 하며, 가격 프리미엄이 책정되어 있어 매출 성장을 주도하고 있습니다.
3D 백에 대한 수요는 업스트림 공정과 다운스트림 공정 간의 물류를 간소화하는 자동 팔레트 탱크와의 통합에 의해서도 뒷받침되고 있습니다. mAB(단일 클론 항체) 시설에서 2,000 L 용량의 일회용 바이오리액터가 표준화됨에 따라, 각 공급업체들은 최신 잠금 플랫폼의 G-force 제한에 맞추어 3D 백의 설계를 조정하고 있습니다. 3D 구조의 세포배양 배지 백 시장 규모는 2031년까지 10억 1,000만 달러에 달할 것으로 예상되며, 이는 압출 성형 제조업체들의 설비 투자 확대의 원동력이 되고 있습니다. 레이저 에칭을 통한 포트 보강 및 사전 장착된 센서와 같은 혁신적인 기술로 인해 작업자의 조작 횟수가 감소하여 CDMO가 처리 시간을 단축할 수 있도록 지원하고 있습니다.
EVA는 투명성, 용접성, 비용의 균형이 뛰어나 2025년에는 매출의 35.06%를 차지했습니다. 그럼에도 불구하고, 줄기세포 및 유전자 치료 사업자들이 초고순도 접촉층을 강력히 요구하고 있어, PVDF 등의 불소계 폴리머는 연평균 성장률(CAGR) 10.41%를 기록하며 세포배양 배지 백 업계 평균을 상회하고 있습니다. PFAS 물질군에 대한 규제상의 우려가 미래의 불확실성을 야기하고 있지만, 동등한 비활성 특성을 갖춘 비불소계 대체재가 제한적이기 때문에 당분간은 수요가 높은 수준을 유지할 전망입니다.
EVA 지지 웹 사이에 얇은 PVDF 표면을 끼워 넣은 다층 구조는 용출물 성능을 확보하면서도 비용 관리에도 기여하고 있습니다. 또한, 공급업체의 연구 개발에서는 가스 차단 특성을 유지하면서 사용 후 재활용성을 향상시키는 바이오 결합층의 개발도 진행되고 있습니다. 불소계 필름을 사용한 세포배양 배지 백 시장 규모는 기존 시설이 최신 추출물 기준을 충족하기 위해 구형 설비를 개조함에 따라 2031년까지 6억 달러를 넘어설 것으로 전망됩니다. 한편, 프탈레이트 에스테르의 이주에 대한 우려로 인해 PVC 사용은 감소 추세를 보이고 있으며, 고성능 대체 소재로의 재료 구성이 가속화되고 있습니다.
지역별 분석
북미는 탄탄한 임상 파이프라인, 성숙한 GMP 인프라, 그리고 FDA의 규제 측면에서의 주도력 덕분에 2025년에는 전 세계 매출의 38.62%를 차지했습니다. 화이자의 매사추세츠 주 거점에 대한 2억 달러 투자와 후지필름의 노스캐롤라이나 주 공장에 대한 12억 달러 투자 등은 이 지역의 규모의 경제를 더욱 강화하고 있습니다. 캐나다와 멕시코는 틈새 생산 및 비용 효율적인 충진·마감 능력을 통해 지역 공급 역량을 보완하고 있습니다. 세포 및 유전자 치료 플랫폼의 보급이 진행됨에 따라, 특히 초저추출물을 실현하는 불소 수지 접촉층을 내면에 갖춘 첨단 일회용 백에 대한 수요가 더욱 높아지고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 중국과 인도의 국내 바이오의약품에 대한 정책 지원을 배경으로 2031년까지 연평균 성장률(CAGR) 11.36%로 확대되고 있습니다. 중국의 ICH 기준에 따른 규제 조화는 유럽 및 미국 규격에 부합하는 현지 배지 백 생산을 뒷받침하고 있습니다. 인도의 비용 경쟁력 있는 제조 모델은 전 세계 스폰서들의 위탁 생산을 유치하고 있는 반면, 한국은 정부의 인센티브를 활용하여 첨단 치료 클러스터를 구축하고 있습니다. 일본에서는 기존의 스테인리스 스틸 설비에서 유연성이 높은 일회용 플랫폼으로의 전환이 진행되고 있으나, 검증 관행은 여전히 보수적입니다. 아시아태평양의 세포배양 배지 백 시장 규모는 2028년까지 유럽을 넘어설 것으로 예측됩니다.
유럽에서는 독일, 영국, 프랑스의 바이오의약품 허브에 더해, 저탄소 소재를 장려하는 EU의 지속가능성 관련 규제의 뒷받침을 받아 견조한 성장을 유지하고 있습니다. 순환형 경제 정책은 재활용 가능한 필름 및 폐쇄형 회수 체계에 대한 연구 개발을 촉진하고 있습니다. 브렉시트로 인해 공급 물류 체계가 재편되고 있지만, EMA가 FDA 규정에 부합하는 추출물에 관한 지침을 채택함에 따라 기술 이전이 간소화되고 있습니다. 이탈리아와 스페인은 틈새 시장인 백신 생산 능력을 확대하고 있는 반면, 동유럽은 규모는 작지만 성장세가 두드러지는 시장으로 부상하고 있습니다. 유럽 전체적으로 조달 과정에서의 탄소 발자국 공개를 중시하고 있으며, 생애주기 평가(LCA)에 기반한 친환경 제품 채택을 촉진하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the cell culture media bags market size in 2026 is estimated at USD 1.71 billion, growing from 2025 value of USD 1.58 billion with 2031 projections showing USD 2.51 billion, growing at 8.05% CAGR over 2026-2031.
This report is Segmented by Design (2D Bags, 3D Bags and More), Material (EVA, LDPE and More), Capacity Volume (<5 L, 5 - 50 L and More), Application (Biopharmaceutical Production, Vaccine Manufacturing and More), End User (CDMOs / CROs, Pharmaceutical & Biotechnology Companies and More) and Geography (North America, Europe and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Cell Culture Media Bags Market Trends and Insights
Expansion of Biopharma and mAB Production Pipelines
Monoclonal antibody capacity additions such as Fujifilm Diosynth's USD 1.6 billion Denmark expansion underscore the scale of demand for large-volume cell culture media bags market solutions. Higher-titer processes lengthen culture duration and increase protein concentration, requiring durable bag films that resist extractable buildup. Antibody-drug conjugate manufacturing further elevates contamination control needs, reinforcing the shift to pre-sterilised single-use assemblies. Geographic diversification of clinical trials into China and India is creating regional sourcing opportunities that still comply with FDA and EMA expectations.
Rapid Adoption of Single-Use Bioprocessing Systems
Changeover times that drop from weeks to 48 hours and lower cleaning requirements make single-use systems highly attractive for multiproduct CDMOs. Life-cycle assessments reveal smaller overall environmental footprints compared with stainless steel, dispelling myths about disposables. Cell and gene therapy producers regard single use as mandatory to mitigate cross-contamination between autologous batches, lifting demand for bespoke bag geometries compatible with perfusion and intensified processes.
Contamination & Leachable Risk Versus Rigid Vessels
Discovery of cytotoxic compounds such as bDtBPP has placed fresh emphasis on rigorous extractables testing, prompting FDA guidance that redefines acceptable risk thresholds. Transition from USP (88) to USP (87) / (665) raises qualification costs, encouraging suppliers to develop fluoropolymer-lined bags despite higher price points.
Other drivers and restraints analyzed in the detailed report include:
- Rising Stem-Cell & Regenerative-Medicine Clinical Trials
- Capacity Build-Out of Vaccine CDMOs Post-COVID-19
- Bio-Hazardous Waste-Disposal Cost Escalation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
2-D films retained 52.58% of the cell culture media bags market in 2025, reflecting legacy dominance in seed-train and buffer-prep tasks. However, 3-D formats are expanding at a 10.05% CAGR, powered by strong uptake in intensified perfusion and commercial-scale viral-vector suites. The flexible cube geometry improves mixing and mass-transfer rates while conserving floor space, attributes validated through computational fluid dynamics studies. Hybrid multilayer versions that combine EVA core layers with fluoropolymer contact surfaces target high-potency biologics and cell therapy batches, commanding price premiums that elevate revenue growth.
Demand for 3-D bags also rides on integration with automated pallet tanks that simplify logistics between upstream and downstream steps. As mAB facilities standardize on 2,000 L single-use bioreactors, suppliers are aligning 3-D bag designs with g-force limitations of modern rocking platforms. The cell culture media bags market size for 3-D configurations is projected to reach USD 1.01 billion by 2031, underpinning expanded capital investment by extrusion firms. Innovations such as laser-etched port reinforcements and pre-installed sensors reduce operator touches and help CDMOs accelerate turnaround times.
EVA captured 35.06% revenue in 2025 because of its balance of clarity, weldability, and cost. Even so, fluorinated polymers such as PVDF are registering a 10.41% CAGR, outpacing the cell culture media bags industry average as stem-cell and gene therapy operators insist on ultra-clean contact layers. Regulatory flags over PFAS substance classes create future uncertainty, but interim demand remains high given limited non-fluorinated substitutes with comparable inertness.
Multi-layer structures that sandwich a thin PVDF surface between EVA support webs help manage cost while delivering leachable performance. Supplier R&D is also targeting bio-based tie layers that maintain gas-barrier traits yet improve end-of-life recyclability. The cell culture media bags market size for fluorinated films is set to surpass USD 0.6 billion by 2031 as mature facilities retrofit older suites to meet updated extractables limits. Conversely, PVC usage is tapering because of phthalate migration concerns, accelerating material mix shift toward high-performance alternatives.
Complete Report Scope:
- By Design
- 2-D Bags
- 3-D Bags
- Hybrid / Multilayer Bags
- By Material
- EVA
- LDPE
- PVC
- Polypropylene
- Fluorinated Polymers (e.g., PVDF)
- Others
- By Capacity Volume
- <5 L
- 5 - 50 L
- 50 - 500 L
- >500 L
- By Application
- Biopharmaceutical Production
- Cell & Gene Therapy Manufacturing
- Vaccine Manufacturing
- Stem-Cell & Academic Research
- Others
- By End User
- Pharmaceutical & Biotechnology Companies
- CDMOs / CROs
- Academic & Research Institutes
- Diagnostic Laboratories
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America secured 38.62% of global revenue in 2025 thanks to deep clinical pipelines, mature GMP infrastructure, and FDA regulatory leadership. Investments such as Pfizer's USD 200 million Massachusetts site and Fujifilm's USD 1.2 billion North Carolina plant reinforce regional scale advantages. Canada and Mexico augment regional supply through niche production and cost-efficient fill-finish capacity. High uptake of cell and gene therapy platforms further boosts sophisticated single-use bag demand, particularly those lined with fluoropolymer contact layers for ultra-low extractables.
Asia-Pacific is the fastest-growing region, advancing at an 11.36% CAGR to 2031 on the back of Chinese and Indian policy support for domestic biologics. China's regulatory harmonisation with ICH standards favours Western-compliant local media bag production. India's cost-competitive manufacturing model attracts contract work from global sponsors, while South Korea leverages government incentives to build advanced therapy clusters. Japan transitions legacy stainless-steel suites toward flexible single-use platforms, although validation practices remain conservative. The cell culture media bags market size attributable to Asia-Pacific is projected to overtake Europe by 2028.
Europe maintains solid growth fuelled by German, UK, and French biologics hubs plus EU sustainability mandates that reward low-carbon materials. Circular-economy policies are catalysing R&D into recyclable films and closed-loop take-back schemes. Brexit reshapes supply logistics, but EMA adoption of FDA-aligned extractables guidance simplifies technology transfer. Italy and Spain add capacity for niche vaccines, whereas Eastern Europe remains a smaller yet rising player. Collectively, Europe emphasises carbon footprint disclosure in procurement, spurring adoption of life-cycle-assessed bag portfolios.
- Thermo Fisher Scientific
- Sartorius
- Danaher Corp.
- Merck
- Corning
- Saint-Gobain Performance Plastics
- Lonza Group
- Entegris Inc.
- Fujifilm Irvine Scientific
- Parker Hannifin Corp. (SciLog)
- Meissner Filtration Products
- Shanghai LePure Biotech Co. Ltd.
- Technoflex SAS
- CellBios Healthcare & Lifesciences Pvt Ltd
- OriGen Biomedical
- Takara Bio
- FlexBiosys (Fukoku Co. Ltd.)
- Terumo
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion Of Biopharma And mAB Production Pipelines
- 4.2.2 Rapid Adoption Of Single-Use Bioprocessing Systems
- 4.2.3 Rising Stem-Cell & Regenerative-Medicine Clinical Trials
- 4.2.4 Capacity Build-Out Of Vaccine CDMOs Post-COVID-19
- 4.2.5 Shift Toward High-Density Perfusion Micro-Bioreactors
- 4.2.6 Scope-3 Decarbonisation Mandates Favouring Lightweight Polymer Bags
- 4.3 Market Restraints
- 4.3.1 Contamination & Leachable Risk Versus Rigid Vessels
- 4.3.2 Bio-Hazardous Waste-Disposal Cost Escalation
- 4.3.3 Volatility In Premium-Grade EVA & PE Resin Prices
- 4.3.4 Geopolitical Polymer-Supply Concentration
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technology Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value-USD)
- 5.1 By Design
- 5.1.1 2-D Bags
- 5.1.2 3-D Bags
- 5.1.3 Hybrid / Multilayer Bags
- 5.2 By Material
- 5.2.1 EVA
- 5.2.2 LDPE
- 5.2.3 PVC
- 5.2.4 Polypropylene
- 5.2.5 Fluorinated Polymers (e.g., PVDF)
- 5.2.6 Others
- 5.3 By Capacity Volume
- 5.3.1 <5 L
- 5.3.2 5 - 50 L
- 5.3.3 50 - 500 L
- 5.3.4 >500 L
- 5.4 By Application
- 5.4.1 Biopharmaceutical Production
- 5.4.2 Cell & Gene Therapy Manufacturing
- 5.4.3 Vaccine Manufacturing
- 5.4.4 Stem-Cell & Academic Research
- 5.4.5 Others
- 5.5 By End User
- 5.5.1 Pharmaceutical & Biotechnology Companies
- 5.5.2 CDMOs / CROs
- 5.5.3 Academic & Research Institutes
- 5.5.4 Diagnostic Laboratories
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Thermo Fisher Scientific Inc.
- 6.3.2 Sartorius AG
- 6.3.3 Danaher Corp.
- 6.3.4 Merck KGaA
- 6.3.5 Corning Incorporated
- 6.3.6 Saint-Gobain Performance Plastics
- 6.3.7 Lonza Group AG
- 6.3.8 Entegris Inc.
- 6.3.9 Fujifilm Irvine Scientific
- 6.3.10 Parker Hannifin Corp. (SciLog)
- 6.3.11 Meissner Filtration Products
- 6.3.12 Shanghai LePure Biotech Co. Ltd.
- 6.3.13 Technoflex SAS
- 6.3.14 CellBios Healthcare & Lifesciences Pvt Ltd
- 6.3.15 OriGen Biomedical
- 6.3.16 Takara Bio Inc.
- 6.3.17 FlexBiosys (Fukoku Co. Ltd.)
- 6.3.18 Terumo BCT
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment