

|
시장보고서
상품코드
2124757
미국의 거터 가드 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United States Gutter Guards - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
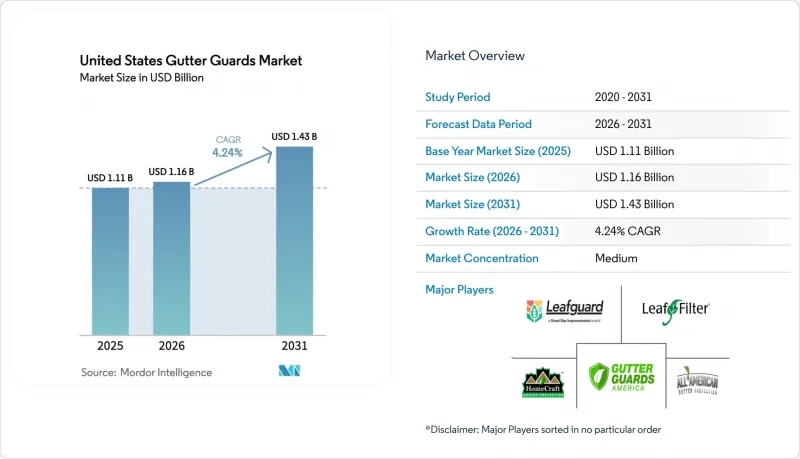
에 의하면, 미국의 거터 가드 시장 규모는 2025년에 11억 1,000만 달러로 평가되었고, 2026년 11억 6,000만 달러에서 2031년까지 14억 3,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.24%를 나타낼 전망입니다.
본 보고서는 제품 유형별(마이크로 메쉬 스크린, 표준 메쉬 및 스크린, 기타), 소재별(알루미늄, 스테인리스 스틸, 비닐/플라스틱, 발포재 및 구리를 포함한 기타), 최종 사용자별(주거용, 상업용, 산업·시설용), 지역별(북동부, 중서부, 남동부, 기타)로 분류되어 있습니다. 시장 예측은 달러 기준 금액으로 제시되어 있습니다.
미국의 거터 가드 시장 동향 및 인사이트
주택 개보수 및 지붕 재시공에 대한 지출 증가
하버드 대학교 주택 연구 공동 센터의 리모델링 활동 선행 지표(LIRA)에 따르면, 주택 개조 지출은 2026년 초에 5,240억 달러에 달할 것으로 예측됩니다. 이는 2024년 7%라는 성장 정점에서 2025년에는 추정 5%, 2026년에는 3%로 둔화되겠지만, 사상 최고치를 기록할 전망입니다. 저금리 주택담보대출에 따른 락인 효과로 인해 이사보다는 리모델링이 계속해서 선호되는 상황입니다. 따라서 자산 가치 향상과 내구성의 이점이 기대되는 지붕 공사 및 관련 외장 공사는 단기적인 투자 대상으로 유력한 선택지로 꼽히고 있습니다. 지붕 공사를 포함한 리모델링 공사 중, 새 지붕은 주택 소유자의 만족도가 가장 높은 것으로 보고되고 있는데, 이는 새로운 시스템에서 막힘이나 넘침을 방지하기 위해 시공업체가 거터 가드를 지붕 교체 공사와 세트로 제안함으로써, 해당 보호 장치의 추가 판매가 촉진되고 있음을 뒷받침합니다. 이러한 추세는 팬데믹 이후의 재평가에 따른 꾸준한 리모델링 활동과 일치하며, 이는 기존의 경기 순환 지표로 파악되던 것보다 더 대규모이고 지속 가능한 지출 기반이 존재함을 시사합니다. 미국의 거터 가드 시장은 시공업체가 현장에 비계와 작업 인력을 배치해 놓을 때 설치율이 향상됨에 따라 이러한 추세의 혜택을 받고 있습니다. 이로 인해 추가 설치에 소요되는 시간이 단축되어, 가드 추가 옵션의 계약 성사율 향상에 기여하고 있습니다. 그 결과, 지붕 교체는 마이크로 메쉬 제품의 보급을 확대하고, 전미 빗물받이 보호대 시장 전체에서 업그레이드 제품의 비중을 유지하는 데 있어 중요한 경로로 계속 작용하고 있습니다.
극심한 강우 및 허리케인 발생 빈도 증가
2025년에는 수십억 달러 규모의 격렬한 폭풍우로 인한 재해가 여러 건 발생했고, 주요 대도시권의 지붕 배수 능력을 시험에 들게 할 정도의 장기간에 걸친 폭우가 이어지면서 기상 변동성이 수요를 확대시키고 있습니다. 미국 내 드문 극한 강수량에 대한 설계치 예측에 따르면, 지구 온난화에 따라 강수 강도가 더욱 높아질 것으로 나타나고 있으며, 이는 기존 빗물받이 시스템에 과제를 안겨주는 한편, 폭우 시에도 물의 흐름을 보장하는 이물질 방지 가드의 가치를 높이고 있습니다. 물리학적 연구 결과에 따르면, 극단적인 강수량은 대기 중 수증기 양에 비례하여 증가하는 경향이 있으며, 분석 및 교육 자료에서는 기후 온난화로 인해 대기 중 수증기 양이 증가하여 단시간 강우가 격화될 것이라고 강조하고 있습니다. 2025년 대서양 허리케인 시즌에는 이름이 붙은 폭풍이 13개에 그쳤으나(연간 평균인 14.4개보다 낮았습니다), 누적 사이클론 에너지(ACE)는 132.4 단위를 기록했는데, 이는 1991년부터 2020년까지의 기준치를 9% 상회하는 수치이며, 특히 카테고리 5 허리케인(에린, 험버트, 멜리사)이 3개 발생했습니다. 콜로라도 주립대학교 열대기상프로젝트의 분석에 따르면, 이는 2005년의 4개에 이어 관측 사상 두 번째로 많은 기록입니다. 보험 업계의 대응으로, 플로리다주와 멕시코만 연안 주에서는 풍해 경감 크레딧 제도가 구체화되고 있습니다. 플로리다주 보험규제국의 공개 정보에 따르면,이 지역에서는 낙엽이나 쓰레기의 유입을 막는 빗물받이 시스템을 설치한 주택 소유자는 풍재 보상 보험료를 5-8% 인하받을 자격을 얻을 수 있으며, 10년간의 보험 계약 기간 동안 설치 비용의 15-20%를 상쇄하는 경제적 인센티브가 발생하고 있습니다.
높은 초기 설치 비용과 DIY 청소와의 비교
고품질의 마이크로 메쉬 시스템은 저가형 DIY용 가드나 비정기적인 전문 업체의 청소 서비스와 경쟁하고 있으며, 가격에 민감한 가구에게는 초기 비용이 장벽이 되고 있습니다. 대형 할인점에서는 업체용 패키지로 알루미늄이나 스테인리스 메쉬가 판매되고 있으며, 이러한 선택지는 예산을 중시하는 구매자가 내구성과 유지보수 비용 절감을 저울질할 때 가격 차이를 두드러지게 만드는 요인이 되고 있습니다. 건축 연수가 오래된 주택의 경우, 가드를 설치하기 전에 빗물받이 교체나 파시아 수리 등의 추가 비용이 발생하는 경우가 많아, 이로 인해 총비용이 증가하고 다른 노후화에 따른 개보수 공사와의 우선순위를 정해야 하는 상황에 직면하게 됩니다. 상업시설의 경우 지붕 선이 길고 접근 요건이 까다로워 작업 시간과 안전 대책이 늘어나며, 이로 인해 설치 비용이 예산 승인 논의에서 더욱 중요한 요소가 됩니다. 여과 및 집수 기능에 대한 명확한 성능 보증이나 독립적인 검증은 비용 대비 효과에 대한 의문을 해소하는 데 도움이 되지만, 투자 회수 전망은 여전히 단기적인 비용 절감보다는 유지보수 회피나 위험 감소에 의존하고 있습니다. 이러한 고려 사항으로 인해 단기적인 현금 흐름을 우선시하는 계층에서의 도입이 주춤할 가능성이 있으며, 프리미엄 제품의 채택이 확대되고 있음에도 불구하고 미국 거터 가드 시장에는 여전히 뿌리 깊은 역풍으로 작용하고 있습니다.
부문 분석
2025년, 표준 메쉬 및 스크린은 미국 거터 가드 시장 점유율의 41.23%를 차지했습니다. 이는 기본적인 이물질 유입 방지를 우선시하는 비용 중심의 프로젝트에서 시공업체들이 익숙해져 있고 가격 면에서도 합리적이라는 점이 반영된 결과입니다. 일체형 시스템은 신축 및 주택 전체 외장 리모델링 분야에서 지지를 넓혀가고 있습니다. 이는 사후 설치 공사의 복잡성을 줄여주고 평생 보증이 제공되기 때문이며, 단일 브랜드 솔루션을 원하는 소유주들에게 프리미엄 선택지로 자리매김하고 있습니다. 한편, 표면장력식 커버나 폼·브러시 인서트는 예산 중심의 프로젝트나 DIY 프로젝트에서 여전히 일정한 역할을 하고 있지만, 그 교체 주기나 성능상의 제약은 초기 비용이 저렴하다는 장점과 상쇄되고 있습니다. 지붕 시공업체나 리모델링 업체들이 비계가 이미 설치된 상황에서 가드 추가 판매를 표준화하고 있기 때문에 도입은 더욱 폭넓은 가격대로 확산되고 있으며, 이는 미국 거터 가드 시장에서 프리미엄 제품의 구성 비율을 더욱 높이는 데 기여하고 있습니다.
제품 유형별 성장을 차별화하는 요소는 성능 실적과 브랜드 포지셔닝입니다. 마이크로 메쉬 제품 공급업체들은 장기적인 막힘 방지에 대한 신뢰를 높이기 위해 내구성과 제3자 기관의 검증 결과를 강조하고 있습니다. 수상 내역이나 실험실 내 내구성 시험 결과를 포함한 제품의 신뢰성 정보는 그동안 구매를 미루거나 정기적인 청소에 의존해 왔던 주택 소유자들의 회의적인 시각을 완화하는 데 도움이 되고 있습니다. 또한, 건설업체와 리모델링 업체도 지붕 보증과의 충돌을 피할 수 있는 대안을 모색하고 있으며, 건설업체의 보증이 유효한 시장에서는 지붕 자재나 지붕 하부 구조를 손상시키지 않고 빗물받이나 파시아에 설치할 수 있는 설계를 선호합니다. 이 유통 채널은 지붕 공사 및 외장 공사 프로젝트에서 가드 제품을 교차 판매하는 전국 규모의 시공업체들에 의해 점차 확산되고 있으며, 나아가 사업 범위를 확대하여 제품과 시공을 단일 서비스 체제 하에 통합하는 민간 공급업체들에 의해 이러한 움직임이 뒷받침되고 있습니다. 이러한 변화로 인해 검증된 설계와 통합된 시공 네트워크에 대한 관심이 높아지고 있으며, 이러한 추세는 미국 거터 가드 시장의 제품 구성과 이익률에 지속적으로 영향을 미치고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the United States gutter guards market size was valued at USD 1.11 billion in 2025 and is estimated to grow from USD 1.16 billion in 2026 to reach USD 1.43 billion by 2031, at a CAGR of 4.24% during the forecast period (2026-2031).
This report is Segmented by Product Type (Micro-Mesh Screens, Standard Mesh and Screens, and More), Material (Aluminum, Stainless Steel, Vinyl or Plastic, Others Including Foam and Copper), End User (Residential, Commercial, Industrial, and Institutional), and Geography (Northeast, Midwest, South, and More). The Market Forecasts are Provided in Terms of Value in USD.
United States Gutter Guards Market Trends and Insights
Increasing Home-Improvement & Reroofing Spend
Home improvement expenditures are projected to reach USD 524 billion in early 2026, marking a record high despite a deceleration from 2024's 7% growth peak to an estimated 5% in 2025 and 3% in 2026, according to the Harvard Joint Center for Housing Studies' Leading Indicator of Remodeling Activity (LIRA). The lock-in effect around low-rate mortgages continues to favor remodeling over moving, which keeps roofing and related exterior projects on the shortlist for near-term investment, given their property value signaling and durability benefits. Within remodels that involve roofing, new roofs delivered the highest reported homeowner satisfaction, reinforcing the upsell path for guards as contractors bundle gutter protection with reroofing jobs to prevent clogs and overflow on new systems. This acceptance aligns with steady remodeling activity following pandemic-era re-benchmarking, which points to a larger and more durable base of spending than previously captured in cyclical indicators. The United States gutter guards market benefits from this pattern through increased attachment rates when installers have scaffolding and crews on site, reducing incremental install time and contributing to higher close rates on guard add-ons. As a result, reroofing remains a critical pathway to expand micro-mesh penetration and sustain an upgrade mix across the United States gutter guards market.
Rising Frequency of Extreme Rainfall & Hurricanes
Weather volatility is amplifying demand, as 2025 featured multiple billion-dollar severe storm disasters and sustained periods of heavy rainfall that tested roof drainage capacity across major metropolitan areas. Projections for rare extreme precipitation design values in the United States indicate higher intensity events under warming, which challenge legacy gutter systems and elevate the value of debris-resistant guards that preserve flow during downpours. Physical science indicates extreme precipitation tends to increase with atmospheric moisture content, with analyses and educational materials highlighting how a warmer climate can load more moisture and intensify short-duration rainfall. The 2025 Atlantic hurricane season, while producing only 13 named storms (below the 14.4 annual average), generated 132.4 units of Accumulated Cyclone Energy (ACE), 9% above the 1991-2020 baseline, and notably spawned three Category 5 hurricanes (Erin, Humberto, Melissa), the second-highest count on record behind 2005's four, per Colorado State University's Tropical Meteorology Project verification. Insurance industry responses are materializing through wind-mitigation credits in Florida and Gulf Coast states, where homeowners installing debris-blocking gutter systems can qualify for 5-8% premium reductions on windstorm coverage, creating a financial incentive that offsets 15-20% of installation costs over a 10-year policy horizon, per Florida Office of Insurance Regulation disclosures.
High Upfront Installed Cost Versus DIY Cleaning
Premium micro-mesh systems compete with low-cost DIY guards and intermittent professional cleanings, which makes the initial outlay a barrier for price-sensitive households. Big-box retailers offer aluminum and stainless mesh options in contractor-grade packs, and those options reinforce the visible price gap that budget-conscious buyers weigh against longevity and maintenance savings. Households in older homes often face added costs for gutter replacement or fascia repair before guards can be installed, which increases the all-in ticket and forces sequencing decisions with other age-related projects. In commercial properties, longer rooflines and access requirements can add labor hours and safety controls, which further push installed costs into budget approval discussions. Clear performance warranties and independent validation for filtration and water-capture roles help address value questions, yet the payback narrative still depends on maintenance avoidance and risk reduction rather than short-term savings. These considerations can slow conversion in cohorts that prioritize near-term cash flow, which creates a persistent headwind for the United States gutter guards market even as premium adoption grows.
Other drivers and restraints analyzed in the detailed report include:
- Aging United States Housing Stock Requiring Retrofits
- Smart Rain-Harvesting Integration with Gutter Guards
- Seasonal Labor Shortages in Skilled Installers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Standard mesh and screens commanded 41.23% of the United States gutter guards market share in 2025, reflecting contractor familiarity and price accessibility for cost-driven projects that prioritize basic debris control. Integrated one-piece systems are gaining traction in new builds and whole-home exterior upgrades because they reduce retrofit complexity and come with lifetime warranties, which positions them as a premium alternative for owners who want a single-brand solution. In parallel, surface-tension covers, and foam or brush inserts retain a role in budget-conscious and DIY projects, yet their replacement cycles and performance constraints are balanced against lower upfront cost expectations. As roofers and remodelers standardize guard upsells when scaffolding is already in place, adoption spreads across more price points, which further supports the premium mix within the United States gutter guards market.
Performance credentials and brand positioning are differentiating growth within product types, as micro-mesh suppliers market durability and third-party validations to bolster trust in long-term clog prevention. Product pedigrees that include awards and lab-tested resilience help reduce skepticism among homeowners who previously deferred purchase or relied on periodic cleanings. Builders and remodelers also look for options that avoid roof warranty conflicts, favoring designs that mount to gutters or fascia without disturbing shingles or roof decking in markets where builder warranties remain active. The channel is adapting with national installers that cross-sell guards in roofing and exterior envelope projects, reinforced by private providers that expand geographic reach and unify product and install under one service umbrella. These shifts concentrate visibility around proven designs and integrated installation networks, a pattern that continues to influence product mix and margins across the United States gutter guards market.
Complete Report Scope:
- By Product Type
- Micro-Mesh Screens
- Standard Mesh & Screens
- Reverse-Curve / Surface-Tension Covers
- Brush / Bristle Inserts
- Foam Inserts
- Integrated Seamless Gutter-Guard Systems
- By Material
- Aluminum
- Stainless Steel
- Vinyl / Plastic
- Others (Foam,Copper)
- By End User
- Residential
- Commercial
- Industrial & Institutional
- By Region
- Northeast
- Midwest
- Southeast
- Southwest
- West
List of Companies Covered in this Report:
- LeafGuard
- LeafFilter North, Inc.
- Gutter Guards America
- All American Gutter Protection
- HomeCraft Gutter Protection
- MasterShield (Major Marketing Group)
- Gutterglove Inc. / Raptor
- Amerimax Building Products
- FlexxPoint, Inc.
- GutterStuff
- Gutter Helmet (EMCO)
- Klean Gutter
- Waterlock Gutter Guards
- E-Z Gutter Guard
- GutterTopper
- CopperCraft (OMNIMAX)
- Spectra Gutter Systems
- Senox Corporation
- Cornerstone Building Brands
- Gibraltar Industries
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing home-improvement & reroofing spend
- 4.2.2 Rising frequency of extreme rainfall & hurricanes
- 4.2.3 Aging United States housing stock requiring retro-fits
- 4.2.4 Growing popularity of micro-mesh premium systems
- 4.2.5 Smart rain-harvesting integration with gutter guards
- 4.2.6 Reshoring of aluminum screen manufacturing capacity
- 4.3 Market Restraints
- 4.3.1 High upfront installed cost versus DIY cleaning
- 4.3.2 Seasonal labor shortages in skilled installers
- 4.3.3 Roof-warranty conflict concerns
- 4.3.4 Emerging self-cleaning "gutter-less" roof alternatives
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Bargaining Power of Buyers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
- 4.7 Insights into the Latest Trends and Innovations in the Market
- 4.8 Insights into Recent Developments (New Product Launches, Strategic Initiatives, Investments, Partnerships, JVs, Expansion, M&As, etc.) in the Market
5 Market Size & Growth Forecasts
- 5.1 By Product Type
- 5.1.1 Micro-Mesh Screens
- 5.1.2 Standard Mesh & Screens
- 5.1.3 Reverse-Curve / Surface-Tension Covers
- 5.1.4 Brush / Bristle Inserts
- 5.1.5 Foam Inserts
- 5.1.6 Integrated Seamless Gutter-Guard Systems
- 5.2 By Material
- 5.2.1 Aluminum
- 5.2.2 Stainless Steel
- 5.2.3 Vinyl / Plastic
- 5.2.4 Others (Foam,Copper)
- 5.3 By End User
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.3 Industrial & Institutional
- 5.4 By Region
- 5.4.1 Northeast
- 5.4.2 Midwest
- 5.4.3 Southeast
- 5.4.4 Southwest
- 5.4.5 West
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 LeafGuard
- 6.4.2 LeafFilter North, Inc.
- 6.4.3 Gutter Guards America
- 6.4.4 All American Gutter Protection
- 6.4.5 HomeCraft Gutter Protection
- 6.4.6 MasterShield (Major Marketing Group)
- 6.4.7 Gutterglove Inc. / Raptor
- 6.4.8 Amerimax Building Products
- 6.4.9 FlexxPoint, Inc.
- 6.4.10 GutterStuff
- 6.4.11 Gutter Helmet (EMCO)
- 6.4.12 Klean Gutter
- 6.4.13 Waterlock Gutter Guards
- 6.4.14 E-Z Gutter Guard
- 6.4.15 GutterTopper
- 6.4.16 CopperCraft (OMNIMAX)
- 6.4.17 Spectra Gutter Systems
- 6.4.18 Senox Corporation
- 6.4.19 Cornerstone Building Brands
- 6.4.20 Gibraltar Industries
7 Market Opportunities & Future Outlook
- 7.1 Heat-trace integrated guards for ice-dam prone zones
- 7.2 Subscription-based monitoring & cleaning-alert IoT add-ons


