

|
시장보고서
상품코드
2124784
의료 규제 업무 아웃소싱 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Healthcare Regulatory Affairs Outsourcing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
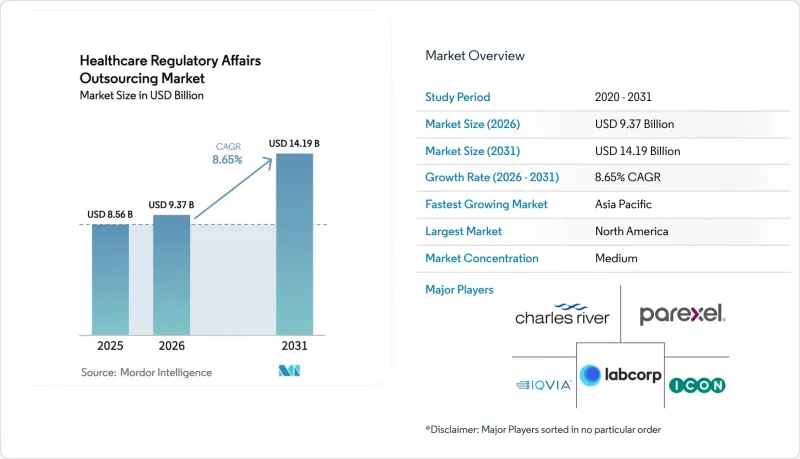
에 의하면, 의료 규제 업무 아웃소싱 시장 규모는 2025년 85억 6,000만 달러로 평가되었습니다. 2026년에는 93억 7,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 8.65%로 성장을 지속하여, 2031년에는 141억 9,000만 달러에 이를 것으로 예측됩니다.
본 보고서에서는 산업을 서비스별(규제 컨설팅, 기타), 제품 수명 주기 단계별(전임상 단계, 기타), 치료 분야별(종양학, 기타), 최종 사용자별(제약 회사, 기타), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류하고 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 의료 규제 업무 아웃소싱 시장 동향 및 인사이트
임상시험 건수 증가
ClinicalTrials.gov에는 2024년 12월 기준으로 48만 7,000건의 연구가 등록되었으며, 이는 2023년 대비 6.2% 증가한 수치로, 신규 임상시험의 거의 절반이 종양학 또는 희귀질환과 관련된 것이었습니다. 각 연구에서는 IND 신청, 프로토콜 수정, 안전성 보고서 등이 작성되지만, 후원사는 이를 외부에 위탁하는 것을 선호합니다. FDA의 ‘프로젝트 옵티머스(Project Optimus)’에서는 암 프로그램에 용량 최적화 시험을 포함하도록 의무화하고 있어, 이로 인해 문서 작성 부담이 증가하여 소규모 팀에게는 큰 부담이 되고 있습니다. 현재 2상 및 3상 프로토콜의 약 30%가 분산형 모델을 채택하고 있으며, 여기에는 전자 동의서 및 원격 모니터링이 결합되어 있습니다. 그러나 이러한 모델은 규제상의 모호성을 초래할 가능성이 있어, 전문 벤더가 더 적절하게 관리할 수 있는 분야입니다. 또한, 디지털 바이오마커 데이터를 신청 서류에 통합할 수 있는 작성자에 대한 수요도 증가하고 있습니다. 이러한 요인들이 복합적으로 작용하여 계약 규모를 확대하고, 의료 규제 업무 아웃소싱 시장을 강화하고 있습니다.
핵심 역량에 집중하는 생명과학 기업
가상 바이오테크 기업은 대개 최소한의 인력으로 운영되며, IND 신청 전 단계부터 시판 후 조사에 이르기까지 모든 규정 준수 업무를 아웃소싱하고 있습니다. 반면, 전통 있는 제약 기업들은 전략 수립은 사내에서 유지하면서, 지역에 따른 신청 서류 조정, 라벨 개정, 일련번호 정보 갱신과 같이 대량 처리가 필요한 업무를 아웃소싱하고 있습니다. 이러한 양극화로 인해 벤더는 고품질의 자문 업무와 상품화된 문서 작성 업무 모두를 지원해야 할 필요가 있습니다. 요금 체계는 승인 마일스톤에 연동된 성과 기반 가격 책정으로 전환되고 있으며, 첫 신청에서 승인을 실현할 수 있는 제공업체에게 보상을 주는 구조로 되어 있습니다. 투자자들이 자금 조달 라운드에 앞서 규제 대응 준비 상황을 면밀히 검토함에 따라, 초기 단계 기업들은 더 이른 시점에 컨설턴트를 기용하게 되었으며, 아웃소싱은 주기적인 것이 아니라 구조적인 선택으로 자리 잡아가고 있습니다.
데이터 보안 및 지적 재산권 유출 위험
스폰서는 기밀 시험 데이터나 제제 세부 정보를 제3자에게 제공해야 합니다. 그러나 GDPR(EU 개인정보보호규정)이나 중국의 ‘개인정보보호법’과 같은 국경을 초월한 규제로 인해 위반 시 막대한 벌금이 부과됩니다. 2024년에 여러 규제 당국에 대한 신청을 중단시킨 랜섬웨어 사건은 취약점을 여실히 드러냈으며, SOC 2 Type II 인증 및 연례 침투 테스트에 대한 수요를 높였습니다. 지적 재산권 유출은 더욱 교묘합니다. 특정 벤더가 동일한 치료 분야에서 경쟁하는 스폰서에게 서비스를 제공하는 경우, 전략적 인사이트가 의도치 않게 유출될 가능성이 있습니다. 현재 계약 협상에는 상세한 사이버 보안 대책, 데이터 소재지 관련 조항, 감사권 등이 포함되어 있어 아웃소싱 계약에 시간과 비용을 추가로 소요하게 하고, 해당 부문의 성장을 둔화시키고 있습니다. 제로 트러스트 아키텍처, 전용 클린룸, 엄격한 이해 상충 관리 방침에 조기에 투자하는 벤더는 수익과 고객의 신뢰를 지킬 수 있습니다.
부문별 분석
2025년에는 ‘규제 관련 문서의 작성 및 출판’이 37.81%로 가장 큰 점유율을 차지하며, ICH 서식 규정에 부합하는 임상시험 보고서, 임상시험 실시 계획서, eCTD 문서에 대한 지속적인 수요가 부각되었습니다. ‘제품 등록 및 임상시험 신청’은 스폰서가 여러 지역에 걸친 병행 신청을 아웃소싱하여 일정을 단축하려는 움직임에 힘입어, 2031년까지 연평균 성장률(CAGR) 11.66%를 나타낼 것으로 예측됩니다. 2025년 1월 발효된 FDA의 eCTD 4.0 의무화에 따라, 필요한 시스템이나 훈련을 받은 인력이 부족한 기업들 간의 아웃소싱이 활발해지고 있습니다. 가격이 가장 높은 분야는 CRISPR 유전자 편집 요법 등의 치료법과 관련된 규제 컨설팅 업무로, 이 부문에서는 당국의 선례가 부족하여 초기 과학적 자문 세션에 고위 전문가가 필요합니다. 법적 대리는 특허 및 독점권 협상에서 틈새 시장이지만 높은 수익률을 보이는 활동으로 지속되고 있습니다.
라벨 및 아트워크 관리는 규모는 작지만, 일련번호 부여 의무 및 다국어 포장 수요로 인해 꾸준히 성장하고 있습니다. 시판 후 및 라이프사이클 관리는 지속적인 안전성 모니터링을 의무화하는 FDA의 센티넬 이니셔티브와 EMA의 EudraVigilance 요건에 힘입어 연평균 성장률(CAGR) 12.42%로 급증하고 있습니다. 실시간 안전성 신호 감지 및 정기적인 안전성 업데이트 보고의 신속화를 제공하는 공급업체들이 장기 계약을 확보하고 있습니다. 구독형 규제 정보, 격차 평가, 모의 감사는 ‘기타 틈새 서비스’를 구성하며, 감사 주기나 새로운 지침이 발표될 때 확대됩니다. 이러한 서비스 동향의 시너지 효과로 인해 의료 규제 업무 아웃소싱 시장은 강력한 성장세를 유지하고 있습니다.
2025년에는 임상 단계 활동이 지출의 44.73%를 차지했으며, 여기에는 IND 신청, 프로토콜 수정, 안전성 정보 갱신이 포함됩니다. 승인 후 및 시판 후 업무는 규제 당국이 신속 승인을 위해 확인 시험을 의무화하고, 보다 엄격한 의약품 안전성 모니터링 기준을 부과함에 따라 2031년까지 연평균 성장률(CAGR) 12.42%를 나타낼 것으로 예측됩니다. FDA는 2024년에 15종의 항암제에 신속 승인을 부여했으나, 각각 시판 후 임상시험이 필요하기 때문에 외부 규제 지원에 대한 수요는 지속될 것입니다. 등록 단계의 프로젝트는 최초 승인 직전에 정점을 맞이하지만, 현재 규제 당국이 롤링 리뷰를 채택하고 있어 반복적인 소통이 필요해지고 있습니다. EMA(유럽의약품청)의 ‘규제 과학 전략’은 적응형 승인 채널을 중시하고 있으며, 신청자는 신청 서류 제출 후에도 지속적인 소통을 유지해야 합니다. 따라서 예측 기간 동안 승인 후 업무와 관련된 의료 규제 업무 아웃소싱 시장 규모는 기존 임상 단계 아웃소싱보다 더 빠르게 확대될 것으로 전망됩니다.
전임상 단계의 자문 서비스는 규모는 작지만, 스폰서가 초기 단계에서 규제 당국의 피드백을 중시하고, 향후 비용이 많이 드는 설계 변경을 피하려는 추세가 있어 증가하는 추세에 있습니다. 지속적인 실세계 증거(RWE)의 생성으로 인해 시판 후 업무와 임상 업무의 경계가 모호해지고 있으며, 클라이언트는 제품의 전체 라이프사이클에 걸쳐 지원할 수 있는 통합형 벤더를 선호하는 추세입니다.
지역별 분석
북미는 5,000개 이상의 활발한 생명공학 스타트업의 존재와 세계적 기준이 되는 규제 당국으로서 FDA의 위상에 힘입어 2025년 매출의 42.36%를 차지했습니다. 아시아태평양은 인도의 정책 개혁과 중국의 적극적인 신청 절차 디지털화로 인해 현지 공급업체의 진입 장벽이 낮아진 것을 반영하여, 연평균 성장률(CAGR) 13.06%를 나타낼 것으로 예측됩니다. 인도의 중앙의약품표준관리기구(CDSCO)는 2024년에 62건의 신약 신청을 승인했는데, 이는 전년 대비 28% 증가한 수치로 심사 효율성이 향상되었음을 보여줍니다. 중국은 같은 해 1,100건 이상의 의약품 등록을 처리했으며, 그중 80%가 국내 기업에 의한 것이었기 때문에 현지 컨설팅 수요를 더욱 촉진하고 있습니다.
중동 및 아프리카에서는 걸프협력회의(GCC) 회원국들이 의약품 가격 책정 및 등록 절차를 통일함으로써 신청 절차의 불일치가 줄어들고 있어 시장이 가속화되고 있습니다. 남미는 여전히 분열된 상태가 지속되고 있으며, 브라질의 ANVISA와 아르헨티나의 ANMAT의 심사 기간이 다르기 때문에 지역 기업들이 지배적인 지위를 유지하고 있습니다. FDA와 EU, 캐나다, 호주의 규제 당국 간의 상호 승인 협정에 따라 감사가 효율화되어, 표준화된 절차를 갖춘 세계 CRO에 유리하게 작용하고 있습니다. 이러한 지역별 차이가 의료 규제 업무 아웃소싱 시장에서 공급업체의 사업 확장 전략을 형성하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the healthcare regulatory affairs outsourcing market size is expected to grow from USD 8.56 billion in 2025 to USD 9.37 billion in 2026 and is forecast to reach USD 14.19 billion by 2031 at 8.65% CAGR over 2026-2031.
This report Segments the Industry Into by Services (Regulatory Consulting, and More), Product-Lifecycle Stage (Pre-Clinical, and More), Therapeutic Area (Oncology, and More), End User (Pharmaceutical Companies, and More), and Geography (North America, Europe, Asia-Pacific, Middle-East and Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Healthcare Regulatory Affairs Outsourcing Market Trends and Insights
Increasing Number of Clinical Trials
ClinicalTrials.gov listed 487,000 studies by December 2024, 6.2% higher than in 2023, and nearly half of the new trials involved oncology or rare diseases. Each study generates IND submissions, protocol amendments, and safety narratives that sponsors prefer to externalize. The FDA's Project Optimus requires oncology programs to include dose-optimization studies, adding layers of documentation that strain small teams. Decentralized models now encompass roughly 30% of Phase II and III protocols, which combine electronic consent and remote monitoring, inviting regulatory ambiguity that specialist vendors can better manage. Demand also rises for writers who can integrate digital biomarker data into dossiers. Together, these forces enlarge contract values and fortify the healthcare regulatory affairs outsourcing market.
Life-Science Companies Focusing on Core Competencies
Virtual biotechs often operate with lean staff, outsourcing every compliance task from pre-IND to post-market surveillance. Established pharmaceutical companies keep their strategies in-house but outsource high-volume activities, such as regional dossier adaptation, labeling revisions, and serialization updates. This bifurcation pushes vendors to support both premium advisory work and commoditized document assembly. Fee structures shift toward outcome-based pricing tied to approval milestones, rewarding providers able to deliver first-cycle approvals. As investors scrutinize regulatory readiness before funding rounds, early-stage companies engage consultants sooner, cementing outsourcing as a structural, not cyclical, choice.
Data-Security & IP-Leak Risks
Sponsors must transfer confidential study data and formulation details to third parties; however, cross-border rules, such as the GDPR and China's Personal Information Protection Law, impose heavy fines for breaches. Ransomware incidents that halted several regulatory submissions in 2024 highlighted vulnerability, prompting demand for SOC 2 Type II certifications and annual penetration tests. Intellectual property leakage is subtler: when one vendor serves competing sponsors in the same therapeutic class, strategic insights may unintentionally migrate. Contract negotiations now include detailed cyber controls, data residency clauses, and audit rights, adding time and cost to outsourcing deals and tempering segment growth. Vendors that invest early in zero-trust architectures, dedicated clean rooms, and strict conflict-management policies protect their revenue and client confidence.
Other drivers and restraints analyzed in the detailed report include:
- Growing Complexity of Global Regulatory Frameworks
- AI-Driven Regulatory-Intelligence Adoption
- Rapid Policy Shifts in Digital Therapeutics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Regulatory Writing & Publishing generated the largest share, at 37.81%, in 2025, underscoring the persistent demand for compliant clinical study reports, investigator brochures, and eCTD dossiers that meet ICH formatting rules. Product Registration & Clinical-Trial Applications are projected to grow at an 11.66% CAGR through 2031, as sponsors seek to compress timelines by outsourcing parallel filings across multiple regions. The FDA's eCTD 4.0 mandate, effective January 2025, has intensified outsourcing among firms lacking the necessary systems or trained staff. Pricing remains highest for Regulatory Consulting assignments tied to modalities like CRISPR-edited therapies, where agency precedent is scarce and early scientific advice sessions demand senior experts. Legal Representation continues as a niche but high-margin activity for patents and exclusivity negotiations.
Labeling & Artwork Management is modest in size but grows steadily due to serialization mandates and multilingual packaging needs. Post-market and Lifecycle Management surges at a 12.42% CAGR, driven by the FDA Sentinel Initiative and EMA EudraVigilance requirements, which mandate continuous safety monitoring. Vendors offering real-time safety-signal detection and expedited periodic safety update reports win long-term contracts. Subscription-based regulatory intelligence, gap assessments, and mock inspections form Other Niche Services that expand during audit cycles or when new guidance emerges. The cumulative effect of these service trends maintains strong momentum in the healthcare regulatory affairs outsourcing market.
Clinical-phase activities held 44.73% of spending in 2025, covering IND filings, protocol amendments, and safety updates. Post-approval and post-market work is forecast to grow at 12.42% CAGR to 2031 as regulators mandate confirmatory studies for accelerated approvals and impose stricter pharmacovigilance standards. The FDA granted accelerated approval to 15 oncology drugs in 2024, each requiring post-launch trials to sustain demand for external regulatory support. Registration-stage projects peak just before initial approval, but now involve iterative interactions as agencies adopt rolling reviews. EMA's Regulatory Science Strategy emphasizes adaptive pathways, compelling sponsors to maintain dialogue even after dossier submission. The healthcare regulatory affairs outsourcing market size for post-approval commitments is therefore projected to expand more rapidly than traditional clinical-phase outsourcing over the forecast period.
Pre-clinical advisory, though smaller, is trending upward because sponsors value agency feedback early, seeking to avoid costly redesigns later. Continuous real-world evidence generation blurs lines between post-market and clinical operations, prompting clients to prefer integrated vendors that can nurture products across their lifespan.
Complete Report Scope:
- By Services
- Regulatory Consulting
- Legal Representation
- Regulatory Writing & Publishing
- Product Registration & Clinical-Trial Applications
- Labeling & Artwork Management
- Post-Market / Lifecycle Management
- Other Niche Services
- By Product-Lifecycle Stage
- Pre-Clinical
- Clinical (Phase I-III)
- Registration
- Post-Approval / Post-Market
- By Therapeutic Area
- Oncology
- Infectious Diseases
- Cardio-Metabolic
- CNS & Neurology
- Immunology & Rare Diseases
- Other Therapeutic Area
- By End User
- Pharmaceutical Companies
- Biotechnology Companies
- Medical-Device Manufacturers
- Contract Research & Manufacturing Organisations
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 42.36% of the revenue in 2025, supported by more than 5,000 active biotech startups and the FDA's position as a global reference regulator. The Asia-Pacific region is forecast to grow at a 13.06% CAGR, reflecting India's policy reforms and China's aggressive digitalization of submissions, which lower entry barriers for localized vendors. India's Central Drugs Standard Control Organisation approved 62 new drug applications in 2024, representing a 28% increase, which signals improved review efficiency. China processed more than 1,100 drug registrations in the same year, 80% from domestic players, further catalyzing local consulting demand.
The Middle East & Africa are accelerating as Gulf Cooperation Council members harmonize drug pricing and registration processes, thereby lowering submission variability. South America remains fragmented, with Brazil's ANVISA timelines diverging from those of Argentina's ANMAT, allowing regional firms to maintain a dominant position. Mutual-recognition agreements between the FDA and regulators in the EU, Canada, and Australia streamline inspections, favoring global CROs equipped with standardized processes. These regional contrasts shape vendor expansion strategies in the healthcare regulatory affairs outsourcing market.
- Accell Clinical Research
- Arriello
- Charles River
- CTI Clinical Trial & Consulting
- Freyr Solutions
- Genpact
- ICON
- IQVIA
- LabCorp
- MedPace
- Parexel International
- PharSafer Associates
- ProductLife Group
- Promedica International
- SGS Life Sciences
- Syneos Health
- Thermo Fisher Scientific (PPD)
- Veristat
- WuXi App Tec
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Number of Clinical Trials
- 4.2.2 Life-Science Companies Focusing on Core Competencies
- 4.2.3 Growing Complexity of Global Regulatory Frameworks
- 4.2.4 Expansion of Virtual/Small-Molecule Biotech Start-Ups
- 4.2.5 AI-Driven Regulatory-Intelligence Adoption
- 4.2.6 Emergence of Low-Cost Regulatory Hubs in Developing Countries
- 4.3 Market Restraints
- 4.3.1 Data-Security & IP-Leak Risks
- 4.3.2 Lack of Global Process Standardisation
- 4.3.3 Escalating Cost of Specialised Regulatory Talent
- 4.3.4 Rapid Policy Shifts in Digital Therapeutics
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Services
- 5.1.1 Regulatory Consulting
- 5.1.2 Legal Representation
- 5.1.3 Regulatory Writing & Publishing
- 5.1.4 Product Registration & Clinical-Trial Applications
- 5.1.5 Labeling & Artwork Management
- 5.1.6 Post-Market / Lifecycle Management
- 5.1.7 Other Niche Services
- 5.2 By Product-Lifecycle Stage
- 5.2.1 Pre-Clinical
- 5.2.2 Clinical (Phase I-III)
- 5.2.3 Registration
- 5.2.4 Post-Approval / Post-Market
- 5.3 By Therapeutic Area
- 5.3.1 Oncology
- 5.3.2 Infectious Diseases
- 5.3.3 Cardio-Metabolic
- 5.3.4 CNS & Neurology
- 5.3.5 Immunology & Rare Diseases
- 5.3.6 Other Therapeutic Area
- 5.4 By End User
- 5.4.1 Pharmaceutical Companies
- 5.4.2 Biotechnology Companies
- 5.4.3 Medical-Device Manufacturers
- 5.4.4 Contract Research & Manufacturing Organisations
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Accell Clinical Research
- 6.3.2 Arriello
- 6.3.3 Charles River Laboratories
- 6.3.4 CTI Clinical Trial & Consulting
- 6.3.5 Freyr Solutions
- 6.3.6 Genpact
- 6.3.7 ICON plc
- 6.3.8 IQVIA
- 6.3.9 Labcorp
- 6.3.10 Medpace
- 6.3.11 Parexel International Corporation
- 6.3.12 PharSafer Associates
- 6.3.13 ProductLife Group
- 6.3.14 Promedica International
- 6.3.15 SGS Life Sciences
- 6.3.16 Syneos Health
- 6.3.17 Thermo Fisher Scientific (PPD)
- 6.3.18 Veristat
- 6.3.19 WuXi AppTec
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


