|
시장보고서
상품코드
2124786
디지털 헬스 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Digital Health - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
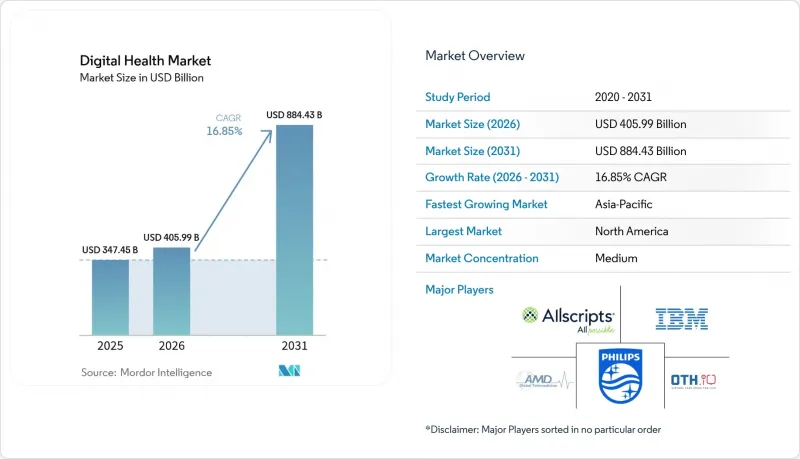
에 의하면, 디지털 헬스 시장 규모는 2025년 3,474억 5,000만 달러로 평가되었습니다. 2026년에는 4,059억 9,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 16.85%로 성장을 지속하여, 2031년에는 8,844억 3,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 구성 요소(하드웨어, 소프트웨어, 서비스), 기술(원격의료, m헬스, 기타), 최종 사용자(의료 제공자, 지불자, 환자·소비자), 지역별로 분류되어 있습니다. 본 보고서에서는 상기 각 부문 시장 규모(달러)를 제시하고 있습니다.
세계의 디지털 헬스 시장 동향 및 인사이트
디지털 헬스의 보급 확대
의료 시스템은 사후 대응형 서비스 제공에서 원격 모니터링, 전자 차트, AI를 활용한 진단을 일상 진료에 접목한 예방적이고 상시 이용 가능한 케어 모델로 전환되고 있습니다. 팬데믹 기간 동안의 긴급성으로 인해 투자가 가속화되었지만, 경영진이 디지털 인프라를 ‘선택 사항’이 아닌 ‘필수 사항’으로 인식하게 되면서 예산은 안정적으로 유지되고 있습니다. 더 많은 의료 기관이 공유 데이터 플랫폼에 연결됨에 따라 네트워크 효과가 나타나며, 추가되는 각 노드의 유용성이 높아집니다. 이러한 선순환을 통해 병원은 상호 운용 가능한 솔루션 도입을 촉진하고, 임상의는 환자가 생성한 데이터를 치료 계획에 반영하도록 유도되며, 대면 서비스와 온라인 서비스 간의 피드백 루프가 강화됩니다. 디지털 헬스 시장이 확대됨에 따라 소비자용 웰니스 앱이 디지털 상호작용을 더욱 일상화시키고, 환자의 디지털 리터러시 기반을 마련하며, 이는 정식 의료 현장으로도 파급되고 있습니다.
AI, IoT, 빅데이터 통합의 진전
현재 인공지능은 영상 진단 선별, 의료 코딩, 가상 기록 작성 등 병원의 핵심 업무를 지원하고 있습니다. 고정밀 IoT 센서는 지속적인 데이터 스트림을 클라우드 분석 엔진으로 전송하여, 병상에서 증상이 나타나기 몇 시간 전에 급성 사건을 예측할 수 있게 해줍니다. 벤더들의 로드맵에서는 합성 데이터 생성, 자동 품질 보증, 멀티모달 추론이 강조되고 있으며, 환경 인텔리전스가 모든 상황에서 환자와 함께할 미래를 예감하게 합니다. 관리 부문 리더는 단기적인 도입 비용을 감수하고 있습니다. 생산성 향상, 보험금 청구 기각 건수 감소, 재입원 벌금 감면 등의 형태로 투자 대비 효과가 나타나기 때문입니다. 데이터 세트가 확대됨에 따라 예측 알고리즘의 정확도는 더욱 높아지고, 디지털 분야의 선두 주자와 후발 주자 간의 성과 격차를 벌리는 자기 강화형 개선 루프가 형성됩니다.
사이버 보안 및 개인정보 보호에 대한 우려
병원 네트워크를 겨냥한 랜섬웨어 공격으로 기밀성이 높은 환자 파일이 유출되는 한편, 가상 진료 이용 건수가 사상 최고치를 기록하는 상황에서 사회의 신뢰는 훼손되고 있습니다. HIPAA 및 GDPR(EU 개인정보보호규정)에 따른 규제적 제재로 인해 정보 유출 대응 비용이 급증하고 이익률이 압박받는 상황에서도, 이사회는 보안 투자를 우선시하도록 압박받고 있습니다. 도입 팀은 강력한 암호화와 의료진의 편의성 사이의 절충점을 찾는 데 고심하고 있습니다. 엄격한 로그인 프로토콜은 업무 흐름을 지연시킬 가능성이 있기 때문입니다. 보험사들은 현재 배상 책임 보험을 인수하기 전에 사이버 보안 대응 능력 인증을 요구하고 있으며, 회복탄력성은 더 이상 차별화 요소가 아니라 시장에서 필수 요건이 되었습니다. 신속한 위협 감지 및 제로 트러스트 아키텍처를 보장할 수 있는 공급업체는 조달 과정에서 우위를 점하고 있으며, 사이버 보안 대응이 디지털 헬스 시장 전반에 걸쳐 기본적인 요건이 되어가고 있음이 부각되고 있습니다.
부문별 분석
2025년, 디지털 헬스 시장 매출의 38.62%를 서비스가 차지했습니다. 이는 의료 시스템 경영진이 복잡한 솔루션 도입 및 규제 준수 관리를 외부 파트너에 의존했기 때문입니다. 대부분의 경우, 도입, 변경 관리, 사이버 보안이 통합된 서비스가 제공되어, 조직이 사내 IT 팀에 과도한 부담을 주지 않고도 원격 중환자실(ICU) 프로그램이나 만성 질환용 앱을 출시할 수 있도록 지원하고 있습니다. 전문 데이터 엔지니어나 정보학자가 부족하여 자체 도입이 지연되고 있는 시장에서는 수요가 계속해서 견조합니다. 그러나 관심은 소프트웨어로 옮겨가고 있으며, 2031년까지의 연평균 성장률(CAGR)은 17.74%로 가장 높은 성장세를 보이고 있습니다. 진료 기록 작성 자동화, 치료 격차 알림 표시, 다중 모드 데이터 통합을 수행하는 클라우드 네이티브 플랫폼은 하드웨어 중심 모델보다 신속하게 확장할 수 있으므로, 중규모 병원도 대학 병원과 경쟁할 수 있게 됩니다.
이러한 변화로 인해 대규모 일괄 라이선스 계약보다 구독형 가격 책정 및 지속적인 기능 출시가 선호되고 있습니다. 각 벤더사는 기존 시스템에 원활하게 통합될 수 있는 모듈형 API를 중시하고 있어, 시스템을 전면 교체하는 데 대한 우려를 덜어주고 있습니다. 알고리즘이 성숙해짐에 따라 사용자 경험이 향상되고, 임상의의 숙련 기간도 단축됩니다. 이러한 이점은 갱신율 향상 및 사용자 1인당 평균 수익(ARPU) 증가로 이어져 소프트웨어의 성장 궤도를 강화하는 동시에, 디지털 헬스 시장에서의 장기적인 구조적 변화를 시사하고 있습니다.
지역별 분석
북미는 관대한 보험사의 환급 제도, 전자 건강 기록(EHR) 도입 기반, 활발한 혁신 파이프라인에 힘입어 2025년 지출의 43.21%를 차지했습니다. FDA의 ‘획기적인 의료기기 프로그램(Breakthrough Device Program)’에서는 1,041건이 지정되었으며, 2024년 9월까지 128건에 대한 시판 승인이 내려졌는데, 이를 통해 미국은 임상 검증 및 투자자 신호 전달 측면에서 기준 시장으로서의 입지를 공고히 하며, 디지털 헬스 시장에서 중심적인 역할을 더욱 강화하고 있습니다. 캐나다와 미국 간의 국경 간 원격의료 협정으로 전문의에 대한 접근성이 개선되는 한편, 멕시코에서는 사회보장제도의 확대에 따라 도시와 농촌 간의 자원 격차를 해소하기 위해 모바일 트리아지 도구가 도입되고 있습니다.
아시아태평양은 각국 정부가 원격진료를 국민 건강보험 전략에 임베디드하고, 휴대전화 보급이 막대한 잠재 사용자층을 창출함에 따라 2031년까지 18.02%라는 가장 높은 연평균 성장률(CAGR)을 나타낼 전망입니다. 2023년, 모바일 경제의 가치는 지역 GDP에서 8,800억 달러에 달했습니다. 인도의 ‘아유슈만 바라트 디지털 미션’은 개인의 건강 기록을 국민 ID와 연동하고 있습니다. 인도네시아의 JKN 제도는 외딴 섬들을 가상 클리닉으로 커버하고 있습니다. 또한, 일본은 요양 인력 부족을 해소하기 위해 AI가 탑재된 재택 요양 로봇에 대한 지원을 실시했습니다. 현지 언어로 된 인터페이스와 경량 데이터 프로토콜 덕분에 처음 이용하는 사용자들 사이에서 보급이 가속화되고 있으며, 이 지역은 디지털 헬스 시장의 새로운 핵심으로 부상하고 있습니다.
유럽, 남미, 중동 및 아프리카에서는 정책 입안자들이 혁신과 개인정보 보호의 균형을 모색하는 가운데, 시장이 한 자릿수 중반의 성장률로 확대되고 있습니다. 독일의 DiGA 프레임워크에서는 인증된 앱에 대한 비용 상환이 이루어지고 있으며, 프랑스에서는 전국 규모의 전자 처방전 서비스가 전개되고 있고, 사우디아라비아의 ‘비전 2030’에서는 원격 ICU(중환자실)에 대한 자금이 편성되어 있습니다. 규제의 불균일성이 다국적 기업의 진출을 지연시키고 있지만, 선도 기업들은 국경을 초월한 정신건강 플랫폼과 희귀질환 등록 제도에서 성장 기회를 포착하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the digital health market size is expected to grow from USD 347.45 billion in 2025 to USD 405.99 billion in 2026 and is forecast to reach USD 884.43 billion by 2031 at 16.85% CAGR over 2026-2031.
This report is Segmented by Component (Hardware, Software, and Services), Technology (Telehealth, Mhealth, and More), End User (Healthcare Providers, Payers, and Patients & Consumers) and Geography. The Report Offers the Value (in USD) for the Above Segments.
Global Digital Health Market Trends and Insights
Increasing adoption of digital healthcare
Health systems are moving from reactive service delivery to preventive, always-on care models that embed remote monitoring, electronic health records, and AI-assisted diagnostics in routine practice. Pandemic-era urgency jump-started investment, but budgets have held steady because chief executives now treat digital infrastructure as essential rather than optional. Network effects surface when more institutions connect to shared data platforms, raising the utility of each additional node. This virtuous cycle encourages hospitals to procure interoperable solutions and nudges clinicians to incorporate patient-generated data into care plans, tightening the feedback loop between in-person and virtual services. As the digital health market expands, direct-to-consumer wellness apps further normalize digital interactions, creating a foundation of patient familiarity that spills over into formal medical settings.
Rise in AI, IoT & big-data integration
Artificial intelligence now underpins core hospital operations such as imaging triage, medical coding, and virtual scribing. High-fidelity IoT sensors feed continuous data streams into cloud analytics engines capable of forecasting acute events hours before they manifest at the bedside. Vendor road maps highlight synthetic-data generation, autopilot quality assurance, and multimodal reasoning, signalling a future where ambient intelligence follows patients across settings. Administrative leaders accept short-run implementation costs because returns show up in productivity gains, fewer claim denials, and lower readmission penalties. As datasets scale, predictive algorithms grow more accurate, creating a self-reinforcing improvement loop that widens the performance gap between digital leaders and laggards.
Cybersecurity & privacy concerns
Ransomware attacks on hospital networks expose sensitive patient files and erode public trust just as virtual care volumes hit new highs. Regulatory penalties under HIPAA and GDPR inflate breach-response costs, nudging boards to prioritize security spending even when margins tighten. Implementation teams juggle the trade-off between bullet-proof encryption and clinician usability, because stricter log-in protocols can slow workflows. Insurers now request cyber-readiness certifications before underwriting liability policies, making resilience a market requirement rather than a differentiator. Vendors who can guarantee rapid threat detection and zero-trust architectures gain an edge in procurement cycles, underscoring how cybersecurity readiness is becoming a foundational expectation across the digital health market.
Other drivers and restraints analyzed in the detailed report include:
- Growing mHealth penetration & smartphone usage
- Expansion of telehealth for aging & rural populations
- Interoperability & data-silo challenges
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services accounted for 38.62% of digital health market revenue in 2025 as health-system executives relied on external partners to deploy complex solutions and manage regulatory compliance. Engagements often bundle implementation, change-management, and cybersecurity, helping organizations launch tele-ICU programs or chronic-disease apps without overloading internal IT teams. Demand stays robust in markets where shortages of specialized data engineers and informaticians slow do-it-yourself rollouts. Yet the spotlight is shifting to software, which registers the fastest 17.74% CAGR to 2031. Cloud-native platforms that automate charting, surface care-gap alerts, and synthesize multimodal data scale faster than hardware-centric models, letting mid-size hospitals compete with academic centers.
The shift favors subscription pricing and continuous feature releases instead of large, one-time license deals. Vendors emphasize modular APIs that plug into existing systems, reducing rip-and-replace anxiety. As algorithms mature, user experience improves, shortening clinician onboarding curves. These benefits translate into higher renewal rates and rising average revenue per user, reinforcing the software growth arc and signaling a long-term structural shift in the digital health market.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By Technology
- Telehealth
- mHealth
- Health Analytics
- Digital Health Systems
- By End User
- Healthcare Providers
- Payers
- Patients & Consumers
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America controlled 43.21% of 2025 spending, backed by generous payer reimbursement schedules, an installed base of electronic health records, and an active innovation pipeline. The FDA's Breakthrough Devices Program provided 1,041 designations, with 128 commercial clears by September 2024, cementing the United States as the reference market for clinical validation and investor signalling, reinforcing its central role in the digital health market. Cross-border telehealth compacts between Canada and the United States improve specialist access, while Mexico's social-security expansion integrates mobile triage tools to manage urban-rural resource gaps.
Asia-Pacific posts the fastest 18.02% CAGR through 2031 as governments fold telemedicine into universal-coverage strategies and handset adoption unlocks massive addressable user pools. Mobile economy value reached USD 880 billion in regional GDP during 2023. India's Ayushman Bharat Digital Mission links personal health records to national IDs; Indonesia's JKN scheme covers remote islands with virtual clinics; and Japan subsidizes AI-based home-care robots to offset nursing shortages. Local language interfaces and lightweight data protocols accelerate adoption among first-time users, positioning the region as a rising anchor of the digital health market.
Europe, South America, and the Middle East & Africa advance at mid-single-digit rates as policymakers negotiate the balance between innovation and privacy. Germany's DiGA framework reimburses certified apps, France deploys nationwide e-prescription services, and Saudi Arabia's Vision 2030 earmarks tele-ICU funds. Regulatory heterogeneity slows multinational rollouts, yet early movers find growth pockets in cross-border mental-health platforms and rare-disease registries.
- AdvancedMD
- Allscripts
- AT&T
- Athenahealth
- Oracle Corp. (Cerner)
- AMD Global Telemedicine
- Cisco Systems
- iHealth Labs
- IBM
- Koninklijke Philips
- Mckesson
- OTH.IO
- Teladoc Health
- Amwell
- Apple
- Google Health
- Qualcomm
- GE Healthcare
- Siemens Healthineers
- Epic Systems
- Medtronic
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing adoption of digital healthcare
- 4.2.2 Rise in AI, IoT & Big Data integration
- 4.2.3 Growing mHealth penetration & smartphone usage
- 4.2.4 Expansion of telehealth for aging & rural populations
- 4.2.5 Regulatory sandboxes accelerating digital therapeutics approval
- 4.2.6 Generative-AI clinician copilots boosting productivity
- 4.3 Market Restraints
- 4.3.1 Cybersecurity & privacy concerns
- 4.3.2 Interoperability & data-silo challenges
- 4.3.3 Algorithmic bias & clinician trust deficit
- 4.3.4 Digital divide limiting rural & elderly access
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Technology
- 5.2.1 Telehealth
- 5.2.2 mHealth
- 5.2.3 Health Analytics
- 5.2.4 Digital Health Systems
- 5.3 By End User
- 5.3.1 Healthcare Providers
- 5.3.2 Payers
- 5.3.3 Patients & Consumers
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 AdvancedMD Inc.
- 6.3.2 Allscripts Healthcare Solutions Inc.
- 6.3.3 AT&T
- 6.3.4 athenahealth Inc.
- 6.3.5 Oracle Corp. (Cerner)
- 6.3.6 AMD Global Telemedicine Inc.
- 6.3.7 Cisco Systems
- 6.3.8 iHealth Labs Inc.
- 6.3.9 IBM
- 6.3.10 Koninklijke Philips N.V.
- 6.3.11 McKesson Corporation
- 6.3.12 OTH.IO
- 6.3.13 Teladoc Health
- 6.3.14 Amwell
- 6.3.15 Apple Inc.
- 6.3.16 Google Health
- 6.3.17 Qualcomm Life
- 6.3.18 GE HealthCare
- 6.3.19 Siemens Healthineers
- 6.3.20 Epic Systems
- 6.3.21 Medtronic plc
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-need assessment