

|
시장보고서
상품코드
2124795
수술 후 통증 관리 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Post-Operative Pain Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
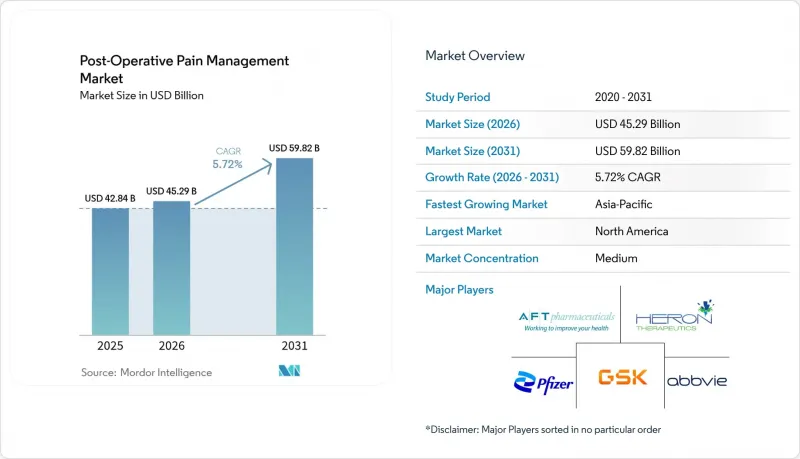
에 의하면, 수술 후 통증 관리 시장 규모는 2025년 428억 4,000만 달러로 평가되었습니다. 2026년 452억 9,000만 달러에서 2031년에는 598억 2,000만 달러로 확대되고 2026-2031년에 걸쳐 CAGR 5.72%를 기록할 전망입니다.
본 보고서는 약물 분류별(오피오이드, COX-2 억제제, 기타), 투여 경로별(주사제, 경구, 기타), 수술 유형별(정형외과, 심혈관·흉부, 기타), 유통 채널별(병원 약국, 기타),지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 수술 후 통증 관리 시장 동향 및 인사이트
수술 건수 증가
선택적 수술은 팬데믹 이전 수준으로 회복되었으며, 계속해서 증가 추세를 보이고 있습니다. 특히, 정형외과 사례 수의 대부분을 차지하는 고관절 및 무릎 관절 치환술에서 이러한 경향이 두드러집니다. 이러한 고빈도 수술이 당일 수술로 전환됨에 따라, 당일 퇴원이 가능하도록 오피오이드 사용을 최소화한 치료법에 대한 수요가 증가하고 있습니다. 아시아태평양 각국의 보건부는 2급 및 3급 도시에서 수술실 수용 능력을 확대하고 있으며, 이러한 움직임으로 인해 수백만 명의 신규 환자가 표준화된 다중 모드 프로토콜의 대상이 됨에 따라 수술 후 통증 관리 시장이 확대되고 있습니다. 동시에 전 세계 비정부 기구들은 저소득 지역의 미치료 수술 사례가 누적되어 있음을 지적하며, 인프라가 정비됨에 따라 표면화될 강력한 잠재 수요를 시사하고 있습니다. 이러한 누적된 영향으로 인해, 성숙한 유럽 및 미국 시장의 가격 하락을 상쇄할 수 있는 지속적인 수술 건수 증가의 호재가 만들어지고 있습니다.
다중 요법 및 비오피오이드 요법으로의 전환
지침 제정 기관과 보험사는 현재 다중 요법을 1차 치료법으로 지정하고 있으며, 대부분의 입원 및 외래 치료 채널에서 오피오이드 단독 요법을 대체하고 있습니다. CMS(미국 의료보험센터)의 환급 제외 규정에 따라 고가의 비오피오이드 계열 약물에 대한 병원 예산 페널티가 철폐됨에 따라, 미국의 대규모 의료 시스템 전반에서 약물 목록의 급속한 전환이 진행되고 있습니다. 유럽에서는 보다 신중한 태도가 보이지만, 독일의 건강보험조합에서는 유사한 모델을 시범적으로 도입하고 있으며, 향후 유럽 전역으로 확산될 것으로 예측됩니다. 병원에서는 1회 투여로 통각 수용과 염증 조절을 결합한 부피바카인-멜록시캄 매트릭스 제제와 같은 이중 작용기전의 제제가 주목받고 있으며, 이를 통해 간호 업무의 부담과 재고 관리의 복잡성이 경감되고 있습니다. 이러한 변화들이 맞물리면서 실제 임상 현장에의 도입이 가속화되고 있으며, 수술 후 통증 관리 시장의 수익 기반이 더욱 견고해지고 있습니다.
오피오이드 의존증의 위기와 규제 강화
급성기 오피오이드 처방을 3일분으로 제한하는 CDC 지침은 현재 미국 대부분의 주에서 시행되고 있으며, 전자 모니터링 프로그램을 통해 업계 내 기준에서 벗어난 사례가 지적되고 있습니다. 영국 규제 당국은 급성기 수술 후 서방형 제제의 사용을 금지하고 있으며, 다른 영연방 국가들의 규제 당국도 이 선례를 검토하고 있습니다. 이러한 규제로 인해 오피오이드 처방량은 감소하지만, 간접적으로 비오피오이드계 대체 약물에 대한 수요를 확대시켜 수술 후 통증 관리 시장 전체의 수익 감소를 완화하고 있습니다.
부문별 분석
국소 마취제는 2025년에 10억 달러의 매출을 기록했고 연평균 성장률(CAGR) 8.25%를 나타낼 것으로 예측되며, 오피오이드로부터 수술 후 통증 관리 시장 점유율을 서서히 빼앗고 있습니다. 오피오이드는 2025년에도 매출의 45.55%를 차지했으며, 규제상의 역풍이 거세지는 가운데서도 그 확고한 입지가 부각되고 있습니다. 2024년, 파실라(Pasira)사는 ‘엑스파렐(Exparel)’의 분기 매출이 1억 4,500만 달러였다고 보고하여, 지속적인 채택이 진행되고 있음을 입증했습니다. 가바펜티노이드, 케타민, 덱스메데토미진은 여전히 주 치료법이라기보다는 보조 요법으로 자리 잡고 있지만, 부피바카인-멜록시캄과 같은 복합 제제는 그 가치 제안을 재정의하고 있습니다.
병원에서는 부작용 프로파일의 개선으로 인해 보험 급여와 관련된 환자 만족도 지표가 향상되므로 국소 마취제가 환영받고 있습니다. 차세대 저장형 제제 기술은 혈장 농도 곡선을 더욱 완만하게 만들 가능성이 있어, 이를 통해 오피오이드에 대한 선호도가 더욱 높아질 수 있습니다. NSAIDs는 여전히 핵심 약제로 자리 잡고 있지만, 안전성 측면에서 투여량이 적게 유지되고 있어, 수술 후 통증 관리 시장 전체에서 마취제 시장 점유율이 확대될 여지가 남아 있습니다.
외용제와 경피 흡수제는 연평균 성장률(CAGR) 9.75%로 가장 빠른 성장세를 보였으나, 2025년 시점에서는 주사제가 여전히 수술 후 통증 관리 시장 규모에서 가장 큰 점유율을 차지하고 있었습니다. 재택 요양에서는 경구 투여가 필수적이지만, 신속 회복 프로그램에서 오피오이드 유발성 장마비에 대한 우려로 인해 경구용 비오피오이드 병용 요법에 대한 관심이 높아지고 있습니다. 척수강내 카테터는 흉부 및 복부 치료 현장에서 계속 사용되고 있지만, 그 운용에는 전문 인력이 필요하며, 소규모 의료기관에서는 이러한 인력이 부족한 경우가 많습니다.
병원에서는 감염 위험과 간호 시간을 줄이기 위해 라인리스 진통 관리로의 전환이 진행되고 있습니다. FDA 지침에서는 급성기 적응증에 대해 외용제가 유효하다고 명시되어 있어, 신청 서류 제출이 가속화되고 있습니다. 정맥주사 조제실의 인력 부족이 심화되는 가운데, 관리자들은 약사의 확인 없이 간호사가 직접 적용할 수 있는 외용 키트를 승인하고 있어, 수술 후 통증 관리 시장 전체에서 도입에 대한 실무상의 장벽이 제거되고 있습니다.
지역별 분석
북미는 2025년 매출의 38.23%를 차지했습니다. 이는 CMS(미국 의료보험의료서비스센터)의 보상 제도 변경으로 인해 병원 측의 비용에 대한 우려가 해소되고, ASC(외래수술센터(ASC)) 인프라가 급속히 정비되었기 때문입니다. 미국은 AI 기반 의약품 적정 사용 관리 도구의 도입 실적이 가장 많아, 수술 후 통증 관리 시장에서의 리더십을 더욱 공고히 하고 있습니다. 캐나다는 미국의 동향을 주시하고 있으나, 주 차원의 예산 협상으로 인해 국가 차원의 정책 결정이 지연되고 있습니다.
아시아태평양은 중국의 적극적인 수술 능력 확대와 인도의 민간 병원 체인에 의한 프로토콜 차별화를 통해 연평균 성장률(CAGR) 7.42%를 기록하며 성장의 원동력이 되고 있습니다. 중국의 2·3급 도시에서는 전문의의 감독을 최소화하는 표준화된 진통제 번들이 채택되고 있으며, 서방형 마취제나 외용 보조제가 선호되고 있습니다. 일본에서는 고령화로 인해 정형외과 수술 건수가 급증하고 있는 반면, 호주에서는 영국의 오피오이드 규제를 모방할지 여부를 검토 중이며, 이러한 결정은 치료 방식의 구성을 재편할 가능성이 있습니다.
유럽에서는 신중한 움직임이 보입니다. MHRA(영국 의약품 및 의료제품 규제청)의 금지 조치로 인해 영국은 즉시 방출형 오피오이드와 비오피오이드계 보조제로의 전환을 강요받고 있으며, 단가는 하락하고 있지만 비오피오이드계 약제의 처방량은 증가하고 있습니다. 독일에서는 지급 제외 조치가 시범적으로 도입되었으나, 전국적인 확대는 연방 정부와 주 정부의 합의에 달려 있습니다. 프랑스와 스페인은 고가 서방형 제품의 승인에 앞서 추가적인 임상 데이터를 기다리고 있어, 수술 후 통증 관리 시장 전체와 비교했을 때 해당 지역의 성장은 완만한 수준에 그치고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the post-Operative pain management market size is projected to expand from USD 42.84 billion in 2025 and USD 45.29 billion in 2026 to USD 59.82 billion by 2031, registering a CAGR of 5.72% between 2026 to 2031.
This report is Segmented by Drug Class (Opioids, COX-2 Inhibitors, and More), Route of Administration (Injectable, Oral, and More), Surgery Type (Orthopedic, Cardiovascular & Thoracic, and More), Distribution Channel (Hospital Pharmacies, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Post-Operative Pain Management Market Trends and Insights
Growing Number of Surgical Procedures
Elective surgeries have rebounded to pre-pandemic baselines and continue to climb, especially in hip and knee replacement programs that dominate orthopedic caseloads. Ambulatory migration of these high-volume procedures intensifies demand for opioid-sparing regimens that enable same-day discharge. Asia-Pacific health ministries are scaling theater capacity in tier-2 and tier-3 cities, a move that enlarges the Post-Operative Pain Management market by exposing millions of new patients to standardized multimodal protocols. At the same time, global non-government organizations highlight the backlog of untreated surgical cases in low-income regions, indicating strong latent demand that will surface as infrastructure matures. The cumulative effect is a durable volume tailwind that offsets price erosion in mature Western markets.
Shift Toward Multimodal & Non-Opioid Protocols
Guideline bodies and payers now designate multimodal therapy as first-line care, replacing opioid monotherapy in most inpatient and outpatient pathways. CMS reimbursement carve-outs eliminate hospital budget penalties for premium non-opioid drugs, unleashing rapid formulary conversion throughout large U.S. systems. Europe proceeds more cautiously but German sickness funds are piloting similar models, signaling eventual continental uptake. Hospitals gravitate toward dual-mechanism formulations such as bupivacaine-meloxicam matrices that combine nociceptive and inflammatory control in one dose, reducing nursing workload and inventory complexity. Together, these shifts accelerate real-world adoption curves, deepening the revenue base of the Post-Operative Pain Management market.
Opioid Addiction Crisis & Tightening Regulations
The CDC guideline restricting acute opioid prescriptions to 3-day courses is now enforced in most U.S. states, while electronic monitoring programs flag deviations from peer norms. UK regulators barred modified-release formulations for acute postoperative use, a precedent other Commonwealth regulators are evaluating. Although these rules reduce opioid unit volume, they implicitly enlarge demand for non-opioid alternatives, cushioning revenue loss across the broader Post-Operative Pain Management market.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of Long-Acting Regional/Nerve-Block Anesthetics
- Expansion of Ambulatory Surgery Centers (ASCs)
- Hospital Cost-Containment Pressures on Premium IV Formulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Local anesthetics generated USD x billion in 2025 and are forecast to grow at an 8.25% CAGR, capturing incremental Post-Operative Pain Management market share from opioids. Opioids still retained 45.55% of revenue in 2025, underlining their entrenched role despite mounting regulatory headwinds. In 2024, Pacira reported quarterly Exparel sales of USD 145 million, validating continuous uptake. Gabapentinoids, ketamine, and dexmedetomidine remain adjuncts rather than primaries, but combo products like bupivacaine-meloxicam are redefining value propositions.
Hospitals welcome local anesthetics because side-effect profiles improve patient satisfaction metrics tied to reimbursement. Next-wave depot technologies show promise for smoother plasma curves, which could further elevate preference over opioids. NSAIDs persist as backbone agents, yet safety considerations keep their dosage conservative, preserving headroom for anesthetic expansion within the overall Post-Operative Pain Management market.
Topical and transdermal formats posted the fastest trajectory at 9.75% CAGR, although injectables still held the largest slice of Post-Operative Pain Management market size in 2025. Oral routes remain indispensable for home recovery, but concerns over opioid-induced ileus in enhanced recovery programs foster interest in oral non-opioid combinations. Intrathecal catheters continue in thoracic and abdominal contexts but demand specialized staffing that smaller centers often lack.
Hospitals are moving to line-free pain control to reduce infection risk and nursing time. The FDA guidance explicitly lists topical agents as viable for acute indications, accelerating dossier submissions. As staffing shortages hit IV compounding rooms, administrators green-light topical kits that nurses can apply without pharmacy verification, lifting practical barriers to adoption across the Post-Operative Pain Management market.
Complete Report Scope:
- By Drug Class
- Opioids
- NSAIDs
- COX-2 Inhibitors
- Local Anesthetics
- Adjuvant Analgesics
- By Route of Administration
- Injectable
- Oral
- Topical / Transdermal
- Intrathecal / Epidural
- Inhalational
- By Surgery Type
- Orthopedic
- Cardiovascular & Thoracic
- Abdominal & Gastrointestinal
- Obstetrics & Gynecology
- Ophthalmic & ENT
- Others
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America delivered 38.23% of 2025 revenue as CMS reimbursement changes neutralized hospital cost objections and ASC infrastructure matured quickly. The United States posts the widest installed base of AI-driven stewardship tools, further consolidating its leadership in the Post-Operative Pain Management market. Canada observes the U.S. rollout but provincial budget negotiations slow a national policy decision.
Asia-Pacific is the growth engine at 7.42% CAGR due to aggressive surgical capacity expansion in China and protocol differentiation by private Indian hospital chains. Tier-2 and tier-3 Chinese cities adopt standardized analgesic bundles that require minimal specialist oversight, favoring depot anesthetics and topical adjuncts. Japan's aging demographic spikes orthopedic volume, while Australia weighs mirroring the UK opioid restrictions, decisions that could reshape delivery mix.
Europe moves cautiously. The MHRA ban forces the UK to pivot toward immediate-release opioids and non-opioid adjuncts, trimming unit value but lifting non-opioid volume. Germany pilots payment carve-outs yet national rollout hinges on federal-state consensus. France and Spain await more real-world data before approving premium depot products, keeping regional growth moderate relative to the broader Post-Operative Pain Management market.
- Abbvie
- AFT Pharmaceuticals
- Alembic Pharmaceuticals
- Baxter
- Bayer
- Boston Scientific
- Cipla
- Eli Lilly and Company
- Endo International
- GlaxoSmithKline
- Heron Therapeutics
- Hikma Pharmaceuticals
- Hyloris Pharmaceuticals
- Innocoll
- Johnson & Johnson
- Mallinckrodt plc
- Medtronic
- Neumentum Inc.
- Novartis
- Pacira BioSciences Inc.
- Pfizer
- Teva Pharmaceutical Industries
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Number of Surgical Procedures
- 4.2.2 Shift Toward Multimodal & Non-Opioid Protocols
- 4.2.3 Adoption of Long-Acting Regional/Nerve-Block Anesthetics
- 4.2.4 Expansion of Ambulatory Surgery Centers (ASCs)
- 4.2.5 AI-Driven Personalized Opioid Stewardship Algorithms
- 4.2.6 Legislated Separate Reimbursement for Non-Opioid Analgesics
- 4.3 Market Restraints
- 4.3.1 Opioid Addiction Crisis & Tightening Regulations
- 4.3.2 Hospital Cost-Containment Pressures on Premium IV Formulations
- 4.3.3 MHRA Ban on Modified-Release Opioids for Acute Post-Op Pain
- 4.3.4 Pharmacist & Technician Workforce Shortages
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Drug Class
- 5.1.1 Opioids
- 5.1.2 NSAIDs
- 5.1.3 COX-2 Inhibitors
- 5.1.4 Local Anesthetics
- 5.1.5 Adjuvant Analgesics
- 5.2 By Route of Administration
- 5.2.1 Injectable
- 5.2.2 Oral
- 5.2.3 Topical / Transdermal
- 5.2.4 Intrathecal / Epidural
- 5.2.5 Inhalational
- 5.3 By Surgery Type
- 5.3.1 Orthopedic
- 5.3.2 Cardiovascular & Thoracic
- 5.3.3 Abdominal & Gastrointestinal
- 5.3.4 Obstetrics & Gynecology
- 5.3.5 Ophthalmic & ENT
- 5.3.6 Others
- 5.4 By Distribution Channel
- 5.4.1 Hospital Pharmacies
- 5.4.2 Retail Pharmacies
- 5.4.3 Online Pharmacies
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 AbbVie (Allergan)
- 6.3.2 AFT Pharmaceuticals
- 6.3.3 Alembic Pharmaceuticals
- 6.3.4 Baxter International
- 6.3.5 Bayer AG
- 6.3.6 Boston Scientific
- 6.3.7 Cipla Inc.
- 6.3.8 Eli Lilly & Co.
- 6.3.9 Endo International
- 6.3.10 GSK plc
- 6.3.11 Heron Therapeutics
- 6.3.12 Hikma Pharmaceuticals
- 6.3.13 Hyloris Pharmaceuticals
- 6.3.14 Innocoll
- 6.3.15 Johnson & Johnson (Janssen)
- 6.3.16 Mallinckrodt plc
- 6.3.17 Medtronic plc
- 6.3.18 Neumentum Inc.
- 6.3.19 Novartis AG
- 6.3.20 Pacira BioSciences Inc.
- 6.3.21 Pfizer Inc.
- 6.3.22 Teva Pharmaceutical Industries
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


