|
시장보고서
상품코드
2124803
자동 머신러닝 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Automated Machine Learning - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
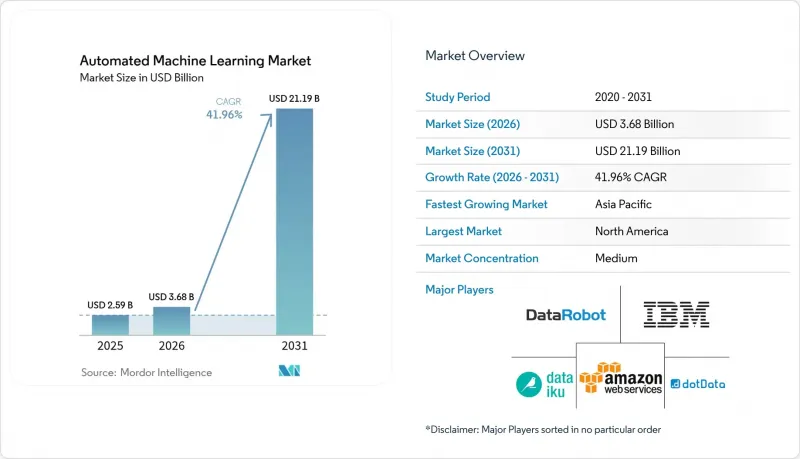
에 의하면, 자동 머신러닝 시장 규모는 2025년에 25억 9,000만 달러로 평가되었습니다. 2026년 36억 8,000만 달러에서 2031년까지 211억 9,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 41.96%를 나타낼 전망입니다.
본 보고서에서는 산업을 솔루션(On-Premise 및 클라우드), 자동화 유형(데이터 처리, 특징량 엔지니어링, 모델링, 시각화), 조직 규모(대기업 및 중소기업(SME)), 최종 사용자(은행, 금융서비스 및 보험(BFSI), 소매 및 전자상거래, 기타), 지역별로 분류하고 있습니다. 시장 규모 및 전망은 상기 모든 부문에 대해 금액(달러) 기준으로 제시되어 있습니다.
세계의 자동 머신러닝 시장 동향 및 인사이트
효율적인 부정 감지 모델에 대한 수요 증가
금융 기관들은 정적인 규칙 세트에서 실시간 거래 흐름을 통해 학습하는 AutoML 기반의 부정 감지 시스템으로 전환하고 있으며, 이를 통해 오감지를 줄이고 회수율을 높이고 있습니다. 보험사들은 자동화된 모델이 구조화 및 비구조화 데이터를 분석하여 의심스러운 보험금 청구를 식별함으로써 2032년까지 800억-1,600억 달러의 비용 절감을 기대하고 있습니다. 내장된 자연어 처리 기능을 통해 플랫폼은 콜센터 통화 기록과 소셜 미디어 신호를 분석하여, 인수 담당자에게 위험 판단을 위한 상세한 맥락을 제공합니다. 금융 규제 당국이 공시 기준을 강화하고 있는 가운데, 각 예측에 설명 가능한 지표를 연계한 대시보드를 제공하는 벤더들은 프리미엄 가격을 책정하고 있습니다. 이러한 시너지 효과로 인해 2026년까지의 예측 연평균 성장률(CAGR)은 8.2% 상승세를 유지할 것으로 전망됩니다.
지능형 비즈니스 프로세스에 대한 수요 증가
기업들은 규칙 기반 로봇에서 적응형 최적화로 전환하기 위해 제조, 소매, 의료 분야의 각 워크플로우에 AutoML을 통합하고 있습니다. 센서를 활용한 예측 유지보수를 통해 예기치 못한 가동 중단 시간을 최대 30% 줄이고, 반도체 제조 라인 전체의 설비 종합 효율(OEE)을 향상시키고 있습니다. 소매업체들은 수요 계획 및 동적 가격 책정에 AutoML을 적용하고 있으며, AI가 생성한 인사이트를 머천다이징 엔진에 활용한 파일럿 프로젝트에서 매출이 22.7% 증가한 것으로 나타났습니다. Oracle의 ‘Clinical Digital Assistant’는 의료 분야에서 그 이점을 여실히 보여주고 있으며, 의사의 문서 작성 시간을 최대 40% 단축하여 환자 치료에 할애할 시간을 확보하고 있습니다. 분석, 워크플로우 오케스트레이션, 로우코드 모델링 도구의 융합을 통해 2020년대 중반까지의 성장에 7.1%를 기여할 것으로 전망됩니다.
기업 내 도입 지연과 문화적 격차
기존 프로세스, 위험 회피적인 경영진, 일자리 상실에 대한 직원들의 우려가 AutoML 도입을 지연시켜 시장 성장세를 4.8% 끌어내리고 있습니다. 많은 아시아 은행에서는 노후화된 핵심 시스템으로 인해 데이터 통합이 복잡해져, 여전히 수작업에 의한 자금 세탁 방지 심사에 의존하고 있습니다. 남아프리카의 중소 제조 기업들은 AI 프로젝트의 주요 제약 요인으로 불명확한 프레임워크와 경영진의 지원 부족을 꼽고 있으며, 이로 인해 도입 주기가 당초 예상보다 길어지고 있습니다. 변혁을 성공시키기 위해서는 교육, 변경 관리 프로그램, AI 성과를 직원의 성과 평가 지표와 연계하는 등 목표가 명확한 인센티브를 조합하는 것이 중요합니다.
부문별 분석
2025년에는 클라우드 플랫폼이 매출의 63.42%를 차지했으며, 이 부문은 2031년까지 연평균 성장률(CAGR) 43.72%를 기록할 전망인데, 이러한 추세는 공유 인프라의 비용적 우위를 뒷받침합니다. 각 하이퍼스케일러 기업이 전용 가속기나 서버리스 훈련 파이프라인을 통합함에 따라, 클라우드 도입에 따른 자동화된 머신러닝 시장 규모는 확대될 것으로 예측됩니다. 지속적인 기능 출시, 엔터프라이즈급 보안 인증, 종량제 과금 방식은 하드웨어 관리보다 민첩성을 중시하는 조직에게 매력적입니다. AWS의 모델 마켓인 ‘Bedrock’에는 100개 이상의 기초 모델과 작업 특화형 모델이 게재되어 있어, 고객은 GPU를 소유하지 않고도 알고리즘을 평가할 수 있으므로 실험 주기가 단축됩니다.
금융, 국방, 공공 부문에서는 데이터 거주지 요건으로 인해 외부 호스팅이 금지되어 있어 On-Premise 배포가 여전히 지속되고 있습니다. 그러나 기밀 컴퓨팅 기술을 통해 퍼블릭 클라우드 환경에서 안전한 처리가 가능해짐에 따라 그 점유율은 점차 줄어들고 있습니다. 지연 시간 목표를 달성하기 위해, 훈련은 클라우드에서 수행하고 추론은 엣지 디바이스에서 실행하는 하이브리드 패턴이 등장하고 있습니다. 엣지 네이티브 서비스를 통해 공장이나 소매점에서의 오프라인 운영이 가능해져, 연결이 끊긴 경우에도 사업 연속성이 확보됩니다.
모델링 자동화는 2025년 매출의 40.35%를 차지했으나, 특징량 엔지니어링의 연평균 성장률(CAGR) 43.11%는 데이터 중심 AI로의 전환을 시사하고 있습니다. 구조화된 데이터 프로젝트의 경우, 견고한 변수 구축이 없으면 실패하는 경우가 많기 때문에 특징량 자동화 분야에서 자동화된 머신러닝 시장 점유율은 확대되고 있습니다. 대규모 언어 모델(LLM)은 현재 원시 필드를 도메인 관련 특징으로 매핑하는 것을 지원하며, 이전에는 전문 지식이 필요했던 시맨틱 결합 및 텍스트 임베딩을 자동화하고 있습니다.
시각화 및 데이터 처리 자동화는 평이한 언어의 질문을 SQL 쿼리나 대화형 차트로 변환함으로써 더 광범위한 도입을 촉진하고 있습니다. 진화 알고리즘과 LLM 프롬프트를 결합한 연구를 통해 벤치마크 데이터셋에서 예측 정확도를 향상시키면서 계산 시간을 단축하는 데 성공했습니다. 도메인 특정 온톨로지가 특징량 파이프라인에 통합되어 수동 개입 없이도 감사 요건을 충족할 수 있기 때문에 의료 및 금융 분야의 사용자가 가장 큰 혜택을 보고 있습니다.
지역별 분석
북미는 밀집된 클라우드 인프라 구축, 성숙한 벤처 캐피탈 생태계, 은행 및 기술 분야의 높은 도입률을 배경으로 2025년 전 세계 매출의 45.38%를 차지했습니다. 규제 대상 산업이 핵심 워크로드를 FedRAMP 준수 리전으로 이전함에 따라, Oracle의 클라우드 인프라 매출은 2025 회계연도에 52% 증가했습니다. 벤처 투자자들은 2024년에 200건 이상의 AutoML 관련 자금 조달 라운드를 성사시켜, 제품 혁신을 가속화하는 활기찬 스타트업 파이프라인을 육성하고 있습니다.
아시아태평양은 각국 정부가 국가 AI 전략을 전개하는 가운데, 2031년 연평균 성장률(CAGR)이 44.63%로 가장 강력한 성장 궤도를 기록하고 있습니다. 일본의 AI 경제는 스마트 시티 시범 사업, 중공업 분야의 예측 유지보수 프로그램, 현지 언어 지원 대화형 에이전트에 힘입어 2027년까지 45억 달러에서 73억 달러로 확대될 것으로 예측됩니다. 중국은 44개 핵심 기술 중 37개 기술 분야에서 특허 출원 건수를 선도하며, 연구와 상용화 양면에서 강호로서의 입지를 공고히 하고 있습니다. 동남아시아의 제조업체들은 인건비 급등과 공급망 변동을 상쇄하기 위해 수율 최적화에 AutoML을 도입하고 있습니다.
유럽의 상황은 복잡합니다. GDPR(EU 개인정보보호규정) 및 향후 시행될 AI 법에 따라 엄격한 거버넌스가 도입되어 판매 주기가 장기화되겠지만, 궁극적으로는 투명성 관리 기능이 내장된 플랫폼에 유리하게 작용할 것입니다. 이 지역의 AI 도입률은 2024년까지 2배인 13%에 달했으나, 많은 기업이 기술적 구축을 외부에 위탁하고 있어 매니지드 AutoML 서비스에 호재가 되고 있습니다. 각국의 경제 부흥 기금에서는 자동화된 모델링 엔진이 필요한 의료 데이터 분야를 포함한 디지털 전환 프로젝트에 수십억 유로가 배정되고 있습니다.
중동에서는 경제 다각화를 도모하기 위해 주목받는 투자가 진행되고 있습니다. 사우디아라비아는 ‘비전 2030’의 일환으로 AI와 디지털 인프라에 1,000억 달러를 배정하고 있으며, 계획 중인 6기가와트 규모의 데이터센터 회랑에도 추가 자금이 투입되고 있습니다. 아랍에미리트는 ‘AI 전략 2031’을 통해 연방 정부 서비스 비용을 50% 절감하는 것을 목표로 하고 있으며, 이를 통해 시민 서비스를 자동화하는 AutoML 플랫폼의 도입이 촉진되고 있습니다. 남미에서는 브라질의 국가 AI 전략이 포르투갈어 모델 개발 및 HPC 업그레이드에 자금을 지원하고 있으며, 그 혜택을 누리고 있습니다. 아프리카는 신흥 시장으로, 조사 대상 기관의 40%가 AI 시범 운영을 진행 중이며, 현지 연산 자원이 여전히 부족한 상황에서 클라우드 호스팅형 AutoML이 도입 장벽을 낮추고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the automated machine learning market size was valued at USD 2.59 billion in 2025 and estimated to grow from USD 3.68 billion in 2026 to reach USD 21.19 billion by 2031, at a CAGR of 41.96% during the forecast period (2026-2031).
This report Segments the Industry Into Solution (On-Premise and Cloud), Automation Type (Data Processing, Feature Engineering, Modeling, and Visualization), Organization Size (Large Enterprises and Small and Medium Enterprises [SMEs]), End User (BFSI, Retail and E-Commerce, and More) and Geography. The Market Sizes and Forecasts are Provided in Terms of Value (USD) for all the Above Segments.
Global Automated Machine Learning Market Trends and Insights
Rising Demand for Efficient Fraud-Detection Models
Financial institutions are moving from static rule sets to AutoML-based fraud systems that learn from real-time transaction flows, cutting false positives and improving recovery rates. Insurers expect savings of USD 80-160 billion by 2032 as automated models mine structured and unstructured data for suspicious claims. Built-in natural-language processing allows platforms to digest call-centre transcripts and social-media signals, giving underwriters granular context for risk decisions. Vendors that deliver dashboards linking explanatory metrics to each prediction command price premiums because finance regulators are tightening disclosure standards. The net effect sustains an 8.2% uplift on forecast CAGR through 2026.
Increasing Need for Intelligent Business Processes
Enterprises are embedding AutoML inside manufacturing, retail, and healthcare workflows to move beyond rule-based robotics toward adaptive optimisation. Sensor-driven predictive maintenance trims unplanned downtime by up to 30% and improves overall equipment effectiveness across semiconductor fabrication lines. Retailers apply AutoML to demand planning and dynamic pricing, with pilots showing 22.7% revenue lifts when AI-generated insights feed merchandising engines. Oracle's Clinical Digital Assistant illustrates healthcare gains, reducing physician documentation time by as much as 40% and freeing capacity for patient care. The convergence of analytics, workflow orchestration, and low-code modelling tools propels a 7.1% contribution to growth through mid-decade.
Slow Enterprise Adoption and Culture Gap
Legacy processes, risk-averse leadership, and workforce apprehension about job displacement slow AutoML rollouts, reducing market momentum by 4.8%. Many Asian banks still rely on manual anti-money-laundering reviews because their aged core systems complicate data integration. Small manufacturing firms in South Africa cite unclear frameworks and limited managerial sponsorship as primary impediments to AI projects, pushing deployment cycles beyond initial forecasts. Successful transformations combine training, change-management programs, and targeted incentives that align AI outcomes with employee performance metrics.
Other drivers and restraints analyzed in the detailed report include:
- Cloud-First ML Strategy of Enterprises
- Shortage of Skilled Data-Science Labour
- Data-Security and Privacy Concerns in Cloud Workflows
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud platforms generated 63.42% of revenue in 2025, and the segment is on track for 43.72% CAGR through 2031, a trajectory that validates the cost advantages of shared infrastructure. The automated machine learning market size for cloud deployments is projected to widen as hyperscalers integrate dedicated accelerators and serverless training pipelines. Continuous feature releases, enterprise-grade security certifications, and usage-based billing appeal to organisations seeking agility over hardware control. Bedrock, AWS's model marketplace, lists more than 100 foundational and task-specific models, letting clients evaluate algorithms without owning GPUs, which compresses experimentation cycles.
On-premises deployments persist in finance, defence, and public sectors where data-residency mandates prohibit external hosting. Their share, however, is eroding as confidential-computing techniques allow secure processing in public-cloud environments. Hybrid patterns have emerged in which training occurs in the cloud while inference runs on edge devices to meet latency targets. Edge-native offerings enable offline operation for factories and retail outlets, ensuring business continuity when connectivity drops.
Modeling automation retained 40.35% of 2025 revenue yet feature engineering's 43.11% CAGR signals a shift toward data-centric AI. The automated machine learning market share for feature automation is expanding because structured-data projects often fail without robust variable construction. Large language models now assist in mapping raw fields to domain-ready features, automating semantic joins and text embeddings that previously demanded specialist knowledge.
Visualization and data-processing automation support wider adoption by translating plain-language questions into SQL queries and interactive charts. Research combining evolutionary algorithms with LLM prompts has cut computation time while improving predictive lift on benchmark datasets. Healthcare and finance users benefit most, as domain-specific ontologies are embedded into feature pipelines, satisfying auditing requirements without manual intervention.
Complete Report Scope:
- By Solution
- On-premise
- Cloud
- By Automation Type
- Data Processing
- Feature Engineering
- Modeling
- Visualization
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By End-user
- BFSI
- Retail and E-commerce
- Healthcare
- Manufacturing
- Other End-users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- South America
- Argentina
- Brazil
- Rest of South America
- North America
Geography Analysis
North America generated 45.38% of global revenue in 2025 on the back of dense cloud-infrastructure footprints, a mature venture-capital ecosystem, and high adoption in banking and technology sectors. Oracle's cloud-infrastructure revenue rose 52% in fiscal 2025 as regulated industries moved core workloads to its FedRAMP-compliant regions. Venture investors closed more than 200 AutoML-related funding rounds in 2024, feeding a vibrant start-up pipeline that accelerates product innovation.
Asia Pacific records the strongest trajectory with 44.63% CAGR through 2031 as governments deploy national AI strategies. Japan's AI economy is projected to expand from USD 4.5 billion to USD 7.3 billion by 2027, driven by smart-city pilots, predictive maintenance programs in heavy industry, and local-language conversational agents. China leads in patent publications for 37 of 44 critical technologies, affirming its status as a powerhouse for both research and commercial implementation. Southeast Asian manufacturers adopt AutoML for yield optimisation to offset rising labour costs and supply-chain volatility.
Europe presents a mixed environment. The GDPR and forthcoming AI Act introduce strict governance that elongates sales cycles but ultimately favours platforms with embedded transparency controls. The region's AI adoption doubled to 13% by 2024, yet many firms outsource technical builds, creating fertile ground for managed AutoML services. National recovery funds earmark billions of euros for digital-transformation projects, including health-data spaces that require automated modelling engines.
The Middle East pursues headline investments to diversify economies. Saudi Arabia has earmarked USD 100 billion for AI and digital infrastructure under Vision 2030, with further capital allocated to a planned 6-gigawatt data-centre corridor. The United Arab Emirates expects its AI Strategy 2031 to cut federal-service costs by 50%, driving procurement of AutoML platforms that automate citizen services. South America benefits from Brazil's national AI strategy, which funds Portuguese-language models and HPC upgrades. Africa is an emerging frontier; 40% of surveyed institutions are piloting AI, and cloud-hosted AutoML lowers the barrier where local compute resources remain scarce.
- Amazon Web Services, Inc.
- Alphabet Inc.
- Microsoft Corporation
- International Business Machines Corporation
- DataRobot, Inc.
- H2O.ai, Inc.
- Dataiku, Inc.
- SAS Institute Inc.
- dotData, Inc.
- Aible, Inc.
- Oracle Corporation
- SAP SE
- Alteryx, Inc.
- RapidMiner, Inc.
- KNIME AG
- BigML, Inc.
- TIBCO Software Inc.
- Databricks, Inc.
- Hewlett Packard Enterprise Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for efficient fraud-detection models
- 4.2.2 Increasing need for intelligent business processes
- 4.2.3 Cloud-first ML strategy of enterprises
- 4.2.4 Shortage of skilled data-science labour
- 4.2.5 Edge-native AutoML for on-device inference (under-reported)
- 4.2.6 Regulatory push for model explainability (under-reported)
- 4.3 Market Restraints
- 4.3.1 Slow enterprise adoption and culture gap
- 4.3.2 Data-security and privacy concerns in cloud workflows
- 4.3.3 Algorithmic bias compliance costs (under-reported)
- 4.3.4 Limited AutoML accuracy on long-horizon time-series (under-reported)
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Key Macroeconomic Trends
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Solution
- 5.1.1 On-premise
- 5.1.2 Cloud
- 5.2 By Automation Type
- 5.2.1 Data Processing
- 5.2.2 Feature Engineering
- 5.2.3 Modeling
- 5.2.4 Visualization
- 5.3 By Organization Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium Enterprises (SMEs)
- 5.4 By End-user
- 5.4.1 BFSI
- 5.4.2 Retail and E-commerce
- 5.4.3 Healthcare
- 5.4.4 Manufacturing
- 5.4.5 Other End-users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 South Korea
- 5.5.3.4 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 United Arab Emirates
- 5.5.4.2 Saudi Arabia
- 5.5.4.3 South Africa
- 5.5.4.4 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Argentina
- 5.5.5.2 Brazil
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Amazon Web Services, Inc.
- 6.4.2 Alphabet Inc.
- 6.4.3 Microsoft Corporation
- 6.4.4 International Business Machines Corporation
- 6.4.5 DataRobot, Inc.
- 6.4.6 H2O.ai, Inc.
- 6.4.7 Dataiku, Inc.
- 6.4.8 SAS Institute Inc.
- 6.4.9 dotData, Inc.
- 6.4.10 Aible, Inc.
- 6.4.11 Oracle Corporation
- 6.4.12 SAP SE
- 6.4.13 Alteryx, Inc.
- 6.4.14 RapidMiner, Inc.
- 6.4.15 KNIME AG
- 6.4.16 BigML, Inc.
- 6.4.17 TIBCO Software Inc.
- 6.4.18 Databricks, Inc.
- 6.4.19 Hewlett Packard Enterprise Company
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment