|
시장보고서
상품코드
2124822
CAR T 세포 치료 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)CAR T-Cell Therapy - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
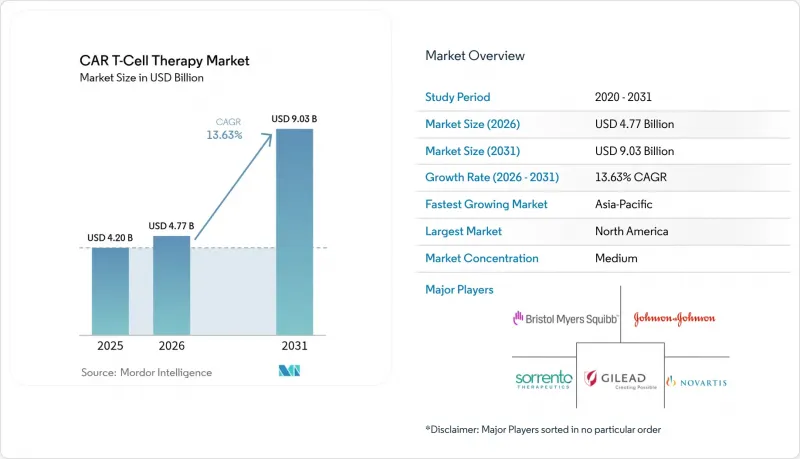
에 의하면, 세계의 CAR T 세포 치료 시장 규모는 2025년에 42억 달러로 평가되었습니다. 2026년 47억 7,000만 달러에서 2031년까지 90억 3,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 13.63%를 나타낼 전망입니다.
본 보고서는 표적 항원(CD19, BCMA, CD22, GD2, 기타), 제품(승인 완료)(Abecma, Breyanzi, 기타), 세포 기원(자가 유래 및 동종 유래), 적응증(백혈병, 림프종, 기타), 최종 사용자(병원, 암 치료 센터, 기타), 지역(북미, 유럽, 아시아태평양, 기타)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 CAR T 세포 치료 시장 동향 및 인사이트
LBCL 2차 치료에 대한 FDA 승인으로 인한 초기 치료 단계에서의 채택 가속화
3상 TRANSFORM 임상시험 데이터에 따르면, LBCL 2차 치료에서 브레얀지는 3년 무사건 생존율이 45.8%였던 반면, 화학요법은 19.1%에 그쳤습니다. 이에 따라 종양 전문의들은 치료 단계를 앞당겨 CAR T 세포 요법을 도입하고 있습니다. 조기 치료로 자리매김함에 따라 신체 상태가 양호한 환자층이 확대되고, 치료 효과의 지속성이 향상되며, 구제 요법의 사용이 감소합니다. 이에 따라 경쟁사들은 2차 치료를 대상으로 임상시험을 재설계하고 있으며, 적응증 확대를 둘러싼 경쟁이 격화되고 있습니다. 보험사 측도 재발률 감소에 따른 장기적인 비용 절감 효과를 평가하기 시작했으며, 이는 보험 급여의 진입 장벽을 낮출 가능성이 있습니다. 이러한 요소들이 맞물려 CAR T 세포 치료 시장의 두 자릿수 성장을 뒷받침하고 있습니다.
EU 내 분산형 현장 제조가 ‘정맥 주입 시작부터 정맥 주입 완료’까지의 시간을 대폭 단축
Euplagia-1 임상시험에서는 재발성 CLL/SLL 환자를 대상으로 7일간의 현장 제조 공정을 적용한 결과, 전체 반응률 92%, 완전 반응률 75%라는 성적이 나타났습니다(Blood 저널). 신속한 제조는 진행 속도가 빠른 암의 치료 중단을 줄이고, 막대한 설비 투자가 필요 없이 의료 기관의 수용 능력을 향상시킵니다. 갈라파고스(Galapagos)와 같은 개발 기업 및 학술 컨소시엄은 기존 병원에 통합할 수 있는 모듈식 클린룸의 확장을 추진하고 있으며, 이 모델은 이미 지불자 측의 비용 절감에 기여하고 있습니다(CGT Live). 규제 당국이 진료 현장의 품질 관리에 관한 지침을 마련하는 가운데, 견고한 디지털 추적 시스템을 갖춘 기업들은 조기에 시설과의 제휴를 확보하여 시장 침투를 가속화하고 있습니다.
CAR T 세포 치료 개발에 드는 높은 비용
자가 유래 배치에는 200시간 이상의 노동 시간이 소요되고, 정가가 50만 달러를 초과하기 때문에 그 도입은 고소득 국가로 제한되어 있습니다(Oncoscience). 라틴아메리카, 중동, 동유럽 일부 지역에서는 보험 환급 제도가 파편화되어 있어, 치료 대상이 되는 많은 환자들이 치료를 받지 못하고 있습니다. 이러한 경제적 부담으로 인해 이중 특이성 항체와 같은 경쟁 치료법에 시장이 개방되면서, 제조업체들은 자동화된 밀폐 시스템 도입을 서둘러야만 하며, 그렇지 않을 경우 시장에서 뒤처질 위험에 직면해 있습니다. 외래 치료의 실현 가능성과 부작용 발생 기간이 짧음을 입증한 프로그램이야말로 지불 기관에 비용 대비 효과를 설득하는 데 가장 적합하지만, 이러한 제약은 CAR T 세포 치료 시장에 여전히 중대한 과제로 남아 있습니다.
부문별 분석
CD19 플랫폼은 2025년 매출의 46.05%를 차지했으며, 이는 미만성 대세포형 B세포 림프종 및 소아 급성 림프구성 백혈병(ALL)에 대한 선구적인 승인을 반영한 것입니다. CAR T 세포 치료 시장 내 이 부문의 경우, 현재 5년을 초과하는 장기 추적 데이터가 있어 의료진의 신뢰를 뒷받침하고 있습니다. Abecma의 조기 치료 적응증 승인을 발판으로 한 BCMA 표적 플랫폼은 2031년까지 연평균 성장률(CAGR) 14.02%로 성장하고 있으며, 이는 현재 항원 분류 중 가장 빠른 성장률입니다. 항원 회피에 대응하기 위해, CD19와 CD20 또는 CD22를 조합한 이중 표적 프로그램이 중기 임상시험 단계에 접어들었습니다. 각 개발사는 만성 림프구성 백혈병 및 맨틀세포 림프종 재발 사례에 대한 적용 가능성을 발견하고 있으며, 이는 CAR T 세포 치료 시장 확대로 이어질 것으로 기대됩니다.
차세대 항원 전략은 혈액암 분야를 넘어선 확장을 목표로 하고 있습니다. GD2 프로그램은 신경모세포종 분야에서 입지를 다지고 있는 반면, HER2를 표적으로 한 프로그램은 위암 코호트에서 진전을 보이고 있습니다. 중국의 의료기관에서는 CLDN18.2를 대상으로 한 20건 이상의 임상시험이 시작되었으며, 이는 중국 내 위암 유병률이 높음을 반영하고 있습니다. 다중 특이성 설계가 지속성 측면에서 우위를 보이게 된다면, CD19 시장 점유율은 하락할 가능성이 있지만, 확고한 도입 실적과 제조 노하우를 바탕으로 당분간은 우위적인 지위를 유지할 것으로 전망됩니다.
2025년 매출의 91.25%를 자가 유래 제품이 차지했으며, 현재 CAR T 세포 치료 시장 규모를 지탱하는 핵심으로서의 역할을 확고히 하고 있습니다. 이 개별화된 워크플로는 기존 규제 프레임워크에 부합하며, 5개의 시판 승인 브랜드를 보유하고 있습니다. 정맥 주입까지 2-4주가 소요된다는 점과 제품 품질에 편차가 있다는 점은 고악성 림프종 치료에 있어 장벽이 되고 있습니다. 연평균 성장률(CAGR) 15.22%가 예상되는 동종 이식 프로젝트는 배치 생산, 낮은 제조 원가, 즉시 투여와 같은 특징을 갖추고 있어 자금 조달에 어려움을 겪는 지불 주체들로부터 환영받고 있습니다.
Allogene, Precision BioSciences, Caribou 각사는 유전자 편집 도구를 사용하여 기증자 세포를 숙주의 면역 체계로부터 은폐하고, 자가 이식과 동등한 지속성을 실현하는 것을 목표로 하고 있습니다. 초기 데이터에 따르면, 혈구 감소증의 기간이 단축되고 외래 치료의 실현 가능성이 높아지고 있는 것으로 시사됩니다. 대규모 2상 임상시험 결과에서 이러한 경향이 재현된다면, 향후 10년 후반에는 CAR T세포 치료 시장이 기성 모델로 기울어질 가능성이 있습니다. 자가 유래 치료 분야의 기존 기업들은 동종 이식용 플랫폼에 대한 라이선싱을 통해 위험을 분산시키고 있으며, 이는 시장이 갑작스럽게 대체되는 것이 아니라 점차 수렴해 나갈 것임을 시사합니다.
지역별 분석
북미는 2025년 전 세계 매출의 52.10%를 차지했으며, 이는 FDA의 조기 승인, 311곳의 인증 치료 시설, 그리고 종합적인 민간 보험 보상을 반영한 결과입니다. 2025년에 발효된 새로운 CPT 시술 코드에 따라 청구 절차가 효율화되어, 학술 거점 이외의 곳에서의 도입이 가속화될 것으로 예상됩니다(Oncology News Central). 치료 접근성에는 여전히 편차가 있으며, 현재 미국에서는 임상적으로 적격한 환자 5명 중 1명만이 치료를 받고 있어, 이동식 아페레시스 장치 및 원격 모니터링 서비스를 위한 미개척 시장이 형성되고 있습니다. 국내에 벡터 제조 공장을 보유하고 신속한 출시 시험을 실시할 수 있는 제조업체는 바이러스 벡터 공급 병목 현상이 지속되는 상황에서도 보다 안정적인 공급을 확보하고 있습니다.
아시아태평양은 가장 빠르게 성장하는 부문이 될 것으로 예측되며, 2031년까지 연평균 성장률(CAGR) 15.55%로 확대될 것으로 전망됩니다. 이는 중국이 등록된 CAR T 임상시험 건수에서 미국을 추월하여 2024년 1월 기준 300건 이상에 달한 것이 배경이 되고 있습니다. 일본과 한국은 제조를 전략적 헬스케어 자산으로 국내에 정착시키는 것을 목표로 신속 심사 체계를 도입하고 있습니다. 이러한 동향으로 인해 해당 지역은 CAR T 세포 치료 시장의 향후 성장에서 핵심적인 위치를 차지하고 있습니다.
유럽은 분산형 제조 분야에서 두드러진 혁신적 우위를 점하고 있으며, 상당한 시장 점유율을 차지하고 있습니다. 벨기에와 스페인에서 실시된 7일간의 포인트 오브 케어(PoC) 시범 사업은 기술적 실현 가능성과 경제적 효율성을 입증했으며, 유럽연합(EU)을 신속한 제공 모델의 ‘리빙 랩’으로 자리매김하고 있습니다. 2025년에 실시된 통합 HTA(의료기술평가) 규정에 따라 상환 제도의 조화가 이루어질 가능성이 있지만, 국가별 가격 협상이 여전히 보급을 저해하고 있습니다. 모듈식 클린룸과 성과 연동형 가격 책정을 결합한 제조업체가 가격에 민감한 의료 시스템에 진입하는 데 가장 성공할 가능성이 높을 것으로 보입니다. 전반적으로, 지리적 분산은 수익원을 안정화시키고 전체 CAR T 세포 치료 시장에서 지역별 정책 리스크를 완화합니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the global CAR t-Cell therapy market size was valued at USD 4.20 billion in 2025 and estimated to grow from USD 4.77 billion in 2026 to reach USD 9.03 billion by 2031, at a CAGR of 13.63% during the forecast period (2026-2031).
This report is Segmented by Target Antigen (CD19, BCMA, CD22, GD2, and More), Type (Abecma, Breyanzi, and More), Cell Source (Autologous and Allogenic), Application (Leukemia, Lymphoma, and More), End User (Hospitals, Cancer Care Treatment Centers, and More), and Geography (North America, Europe, Asia-Pacific and More). The Market Forecasts are Provided in Terms of Value (USD).
Global CAR T-Cell Therapy Market Trends and Insights
Second-line LBCL FDA Approvals Accelerating Early-Line Uptake
Phase 3 TRANSFORM data show Breyanzi delivering a 45.8% three-year event-free survival versus 19.1% for chemo in second-line LBCL, prompting oncologists to move CAR T earlier in the care cascade . Earlier-line positioning expands the pool of fitter patients, raising response durability and reducing salvage-therapy use. Competitors are therefore re-designing trials to target second-line settings, intensifying label-expansion races. Payers are beginning to weigh long-term cost offsets from reduced relapse, which may ease reimbursement hurdles. Collectively, these elements reinforce double-digit growth in the car t-cell therapy market.
Decentralised EU Point-of-Care Manufacturing Slashes Vein-to-Vein Time
The Euplagia-1 trial showed 92% overall and 75% complete response rates using a seven-day, on-site process in relapsed CLL/SLL Blood. Rapid manufacture cuts attrition in fast-progressing cancers and lifts centre capacity without large capital layouts. Developers such as Galapagos and academic consortia are scaling modular clean-rooms that can be grafted onto existing hospitals, a model already shaving costs for payers CGT Live. As regulators craft guidance on point-of-care quality control, firms with robust digital tracking are securing early site partnerships, speeding market penetration.
High Cost of Developing CAR T-Cell Therapy
Autologous batches require more than 200 labor hours and command list prices exceeding USD 500,000, thereby limiting uptake to high-income systems Oncoscience. Fragmented reimbursement in Latin America, the Middle East and parts of Eastern Europe leaves many eligible patients untreated. The economic burden has opened space for competing modalities such as bispecific antibodies, pressuring manufacturers to adopt automated closed systems or risk marginalisation. Programmes demonstrating outpatient feasibility and short adverse-event windows are best placed to convince payers of cost-effectiveness, but the constraint remains material for the car t-cell therapy market.
Other drivers and restraints analyzed in the detailed report include:
- Growing Burden of Cancer Worldwide
- Allogeneic "Off-the-Shelf" Pipelines Lowering Cost-of-Goods
- Vector GMP Capacity Bottlenecks Raise Lead-Times
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
CD19 platforms generated 46.05% of revenue in 2025, reflecting first-mover approvals across diffuse large B-cell lymphoma and paediatric ALL. Within this slice of the car t-cell therapy market, long-term datasets now exceed five years, underpinning physician confidence. BCMA constructs, boosted by Abecma's earlier-line label, are compounding at 14.02% through 2031, the quickest among current antigen classes. Dual-target programs that combine CD19 with CD20 or CD22 are entering mid-stage trials to combat antigen escape. Developers see potential to tap relapsed settings in chronic lymphocytic leukaemia and mantle-cell lymphoma, broadening the car t-cell therapy market.
Next-wave antigen strategies aim to move beyond haematology. GD2 programs are gaining ground in neuroblastoma, while HER2 constructs progress in gastric cancer cohorts. Chinese centres have opened over 20 trials on CLDN18.2, reflecting local gastric cancer prevalence. Should multi-specific designs show persistence advantages, CD19's share could erode, yet its entrenched installed base and manufacturing know-how support near-term dominance.
Autologous inventories delivered 91.25% of 2025 sales, cementing their role as the backbone of the car t-cell therapy market size at present. The personalised workflow fits existing regulatory frameworks and boasts five commercially approved brands. Nevertheless, vein-to-vein times of 2-4 weeks and variable product quality present obstacles in high-grade lymphomas. Allogeneic projects, projected to log a 15.22% CAGR, offer batch production, lower cost-of-goods and immediate dosing, attributes welcomed by cash-strapped payers.
Allogene, Precision BioSciences and Caribou are employing gene-editing tools to cloak donor cells from host immunity, aiming to match autologous durability. Early data suggest shorter cytopenia periods, improving outpatient viability. If large Phase 2 outcomes replicate this profile, the car t-cell therapy market could tilt toward off-the-shelf models later in the decade. Autologous incumbents are hedging by licensing allogeneic platforms, signalling market convergence rather than sudden displacement.
Complete Report Scope:
- By Target Antigen
- CD19
- BCMA
- CD22
- GD2
- HER2
- PSMA
- Multi-Target / Tandem
- Others
- By Cell Source
- Autologous
- Allogeneic
- By Product (Approved)
- Abecma
- Breyanzi
- Kymriah
- Tecartus
- Yescarta
- Others
- By Indication
- Leukemia (ALL, CLL)
- Lymphoma (DLBCL & Other B-Cell)
- Multiple Myeloma
- Auto-Immune Disorders
- Others
- By End-User
- Hospitals
- Cancer Care Treatment Centres
- Academic & Research Institutes
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia- Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 52.10% of 2025 global revenue, reflecting early FDA approvals, 311 accredited treatment sites and robust private insurance coverage. New CPT procedure codes, effective in 2025, should streamline billing and accelerate adoption outside academic hubs Oncology News Central. Nevertheless, access remains uneven; only 1 in 5 clinically eligible US patients currently receives therapy, creating white-space for mobile apheresis units and tele-monitoring services. Manufacturers with domestic vector plants and rapid-release testing enjoy smoother supply in light of persistent viral-vector bottlenecks.
Asia-Pacific is forecast to be the fastest-growing segment, advancing at 15.55% CAGR through 2031 as China surpasses the United States in registered CAR-T trials, tallying more than 300 by January 2024. Japan and South Korea are issuing expedited review pathways, aiming to domesticate manufacturing as a strategic healthcare asset. These developments place the region at the core of future expansion within the car t-cell therapy market.
Europe holds meaningful share with a distinct innovation edge in decentralised manufacturing. Seven-day point-of-care pilots in Belgium and Spain have proven technical feasibility and economic efficiency, positioning the bloc as a living lab for rapid delivery models Blood. Unified HTA rules slated for 2025 may harmonise reimbursement, yet country-level price negotiations still fragment uptake. Producers that couple modular clean-rooms with outcome-based pricing are most likely to penetrate price-sensitive systems. Collectively, geographic diversification cushions revenue streams and tempers region-specific policy risk across the car t-cell therapy market.
- Novartis
- Gilead Sciences
- Bristol-Myers Squibb
- Johnson & Johnson / Legend Biotech
- 2seventy bio Inc.
- Allogene Therapeutics
- Autolus Therapeutics plc
- Caribou Biosciences Inc.
- TCR2 Therapeutics Inc.
- Precision BioSciences Inc.
- Sorrento Therapeutics
- Sangamo Therapeutics
- Celyad Oncology SA
- Servier Laboratories
- Miltenyi Biotec B.V. & Co.
- Acro Biosystems
- JW Therapeutics
- Fosun Kite Biotechnology Co.
- Beigene Ltd.
- Gracell Biotechnologies Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Second-line LBCL FDA Approvals Accelerating Early-Line Uptake
- 4.2.2 Decentralised EU Point-of-Care Manufacturing Slashes Vein-to-Vein Time
- 4.2.3 Growing Burden of Cancer Worldwide
- 4.2.4 Allogeneic "Off-the-Shelf" Pipelines Lowering Cost-of-Goods
- 4.2.5 Increasing Invesment and Research and Development to Develop CAR T-Cell Therapy
- 4.2.6 Medicare NTAP Expansion to Community Oncology Centres Broadens Access
- 4.3 Market Restraints
- 4.3.1 High Cost of Developing CAR T-Cell Therapy
- 4.3.2 Vector GMP Capacity Bottlenecks Raise Lead-Times
- 4.3.3 Limited Patient Eligibility
- 4.3.4 Potential for Severe Side Effects
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Target Antigen
- 5.1.1 CD19
- 5.1.2 BCMA
- 5.1.3 CD22
- 5.1.4 GD2
- 5.1.5 HER2
- 5.1.6 PSMA
- 5.1.7 Multi-Target / Tandem
- 5.1.8 Others
- 5.2 By Cell Source
- 5.2.1 Autologous
- 5.2.2 Allogeneic
- 5.3 By Product (Approved)
- 5.3.1 Abecma
- 5.3.2 Breyanzi
- 5.3.3 Kymriah
- 5.3.4 Tecartus
- 5.3.5 Yescarta
- 5.3.6 Others
- 5.4 By Indication
- 5.4.1 Leukemia (ALL, CLL)
- 5.4.2 Lymphoma (DLBCL & Other B-Cell)
- 5.4.3 Multiple Myeloma
- 5.4.4 Auto-Immune Disorders
- 5.4.5 Others
- 5.5 By End-User
- 5.5.1 Hospitals
- 5.5.2 Cancer Care Treatment Centres
- 5.5.3 Academic & Research Institutes
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia- Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Novartis AG
- 6.3.2 Gilead Sciences Inc. (Kite Pharma)
- 6.3.3 Bristol-Myers Squibb Co.
- 6.3.4 Johnson & Johnson / Legend Biotech
- 6.3.5 2seventy bio Inc.
- 6.3.6 Allogene Therapeutics Inc.
- 6.3.7 Autolus Therapeutics plc
- 6.3.8 Caribou Biosciences Inc.
- 6.3.9 TCR2 Therapeutics Inc.
- 6.3.10 Precision BioSciences Inc.
- 6.3.11 Sorrento Therapeutics Inc.
- 6.3.12 Sangamo Therapeutics Inc.
- 6.3.13 Celyad Oncology SA
- 6.3.14 Servier Laboratories
- 6.3.15 Miltenyi Biotec B.V. & Co.
- 6.3.16 ACROBiosystems
- 6.3.17 JW Therapeutics
- 6.3.18 Fosun Kite Biotechnology Co.
- 6.3.19 Beigene Ltd.
- 6.3.20 Gracell Biotechnologies Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment