|
시장보고서
상품코드
2124878
유도 만능 줄기세포(iPS 세포) : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Induced Pluripotent Stem Cells - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
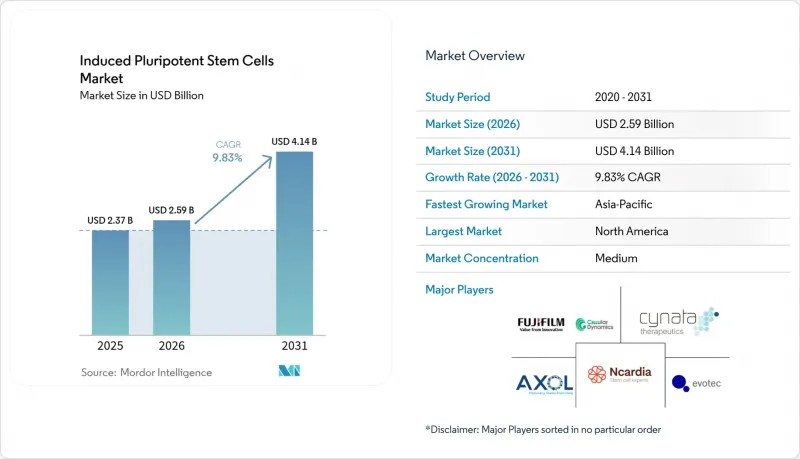
에 의하면, 유도 만능 줄기세포(iPS 세포) 시장 규모는 2025년 23억 7,000만 달러로 평가되었습니다. 2026년 25억 9,000만 달러에서 2031년까지 41억 4,000만 달러로 확대되고 2026-2031년까지 연평균 복합 성장률(CAGR)은 9.83%를 나타낼 전망입니다.
본 보고서는 유래 세포종(심근세포, 뉴런, 간세포, 섬유아세포, 각질세포, 기타), 용도(신약 개발, 질환 모델링, 독성 시험, 재생의학, 세포 치료, 기타), 최종 사용자(학술 연구 기관, 기타),지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계의 유도 만능 줄기세포(iPS 세포) 시장 동향 및 인사이트
iPS 세포를 활용한 신약 개발 및 독성 시험 수요 급증
제약 기업들은 동물 모델에서 벗어나 인간 특유의 독성을 검출할 수 있는 iPS 세포 유래 심근세포 및 간세포로 전환하고 있으며, 이를 통해 2상 임상시험의 실패율을 최대 35% 포인트까지 줄이고 있습니다. FUJIFILM Cellular Dynamics는 iCell 간세포를 통해 설치류를 대상으로 한 스크리닝을 통과한 8가지 화합물에서 잠재적인 간독성을 검출할 수 있음을 보여주었습니다. 이에 따라 2024년에는 FDA 심사관이 임상시험용 의약품 신청 서류에 포함된 iPSC 데이터를 승인하기에 이르렀습니다. 다케다 제약은 2025년까지 자사 파이프라인의 초기 단계에 있는 화합물의 40%에 이러한 분석법을 통합하여, 전임상 개발 기간을 6개월 단축하는 동시에 화합물 1건당 약 3,000만 달러의 비용 절감을 실현했습니다. 찰스 리버(Charles River)나 유로핀스(Eurofins)와 같은 계약 연구 기관(CRO)은 현재 iPSC를 이용한 종합적인 독성 패널에 대해 화합물 1건당 4,500달러를 청구하고 있는데, 이는 2023년 요금의 절반 이하로, 소규모 바이오테크 기업들 사이에서 도입이 확산되고 있습니다. 미국의 ‘21세기 치료법(21st Century Cures Act)’이나 EU의 ‘3R 원칙’에 따른 규제 당국의 수용도가 높아지고 있는 점도 이 기법의 추가적인 정착을 뒷받침하고 있습니다.
iPS 세포 유래 세포 치료제의 임상 파이프라인 확대
2025년 중반 시점에서 전 세계적으로 17개의 iPSC 기반 치료법이 1상 또는 2상 임상시험 단계에 있었습니다. 그 선두를 달리고 있는 것은 블루록 테라퓨틱스(BlueLock Therapeutics)사의 파킨슨병 치료제 ‘베므다네프로셀(Vemdaneprosel)’로, 12개월 시점에서 통합 파킨슨병 평가 척도(UPDRS)에서 40%의 개선 효과를 보였습니다. 하트시드(HeartSeed)사의 심장 패치 ‘HS-001’은 중대한 이상반응 없이 좌심실 박출률을 15% 향상시켰으며, 일반 시판 승인 일정보다 3년을 단축할 수 있는 일본의 조건부 승인 절차를 통해 진전을 보이고 있습니다. 페이트 테라퓨틱스(Fate Therapeutics)의 기성 CAR-NK 세포 ‘FT596’은 B세포 림프종에서 60%의 완전 반응을 달성하여 자가 CAR-T 요법의 벤치마크를 15포인트 상회했습니다. 센추리 테라퓨틱스(Century Therapeutics)는 고형암을 대상으로 한 감마-델타 T 세포 ‘CNTY-101’에 대해 FDA 승인을 획득하여, 대상 암 치료의 기반을 확대했습니다. 이러한 성과들은 종합적으로 유도 만능 줄기세포 시장에 대한 투자자들의 신뢰를 뒷받침하고 있습니다.
대규모 GMP 생산에 따른 높은 비용과 공정의 복잡성
ISO 13485 인증 시설, 30일간의 분화 배양, 전체 유전체 릴리스 검사를 통해 배치당 비용은 최대 15만 달러에 달하며, 많은 대학 출신 스핀아웃 기업들이 가격 면에서 시장에서 배제되고 있습니다. 배지 비용은 1리터당 2,000달러를 초과하는 경우가 많으며, 수율 편차가 50%에 달하기도 하여 신뢰할 수 있는 원가 계산을 어렵게 하고 있습니다. 각 CDMO 기업은 1상 임상시험용 시료에 대해 최대 500만 달러를 청구하고 있으며, 이는 시드 단계의 벤처 기업에게 큰 장벽이 되고 있습니다. 동결보존으로 인한 30%의 손실로 인해 제조업체는 생산 로트를 과도하게 설정할 수밖에 없어, 재고 관련 제반 비용을 부풀리고 있습니다. 자동화를 통해 인건비를 80% 절감할 수 있지만, 500리터 규모의 GMP 시설을 구축하려면 여전히 1,000만 달러 이상의 자본이 필요하며, 이로 인해 유도 만능 줄기세포 시장의 확장 속도가 지연되고 있습니다.
부문별 분석
2025년, 심근 세포는 유도 만능 줄기세포 시장 점유율의 28.02%를 차지했습니다. 이는 심독성 스크리닝 분야의 제약 용도와 Heartseed의 HS-001 패치와 같은 재생의학 임상시험에 힘입은 결과입니다. 심실 패치 임상시험의 병행된 진전으로 인해 빠르면 2027년에도 치료 분야에서 수익원이 열릴 가능성이 있습니다.
신경세포는 예측 연평균 성장률(CAGR) 10.06%로 여전히 가장 빠르게 성장하는 하위 부문입니다. 파킨슨병 및 ALS 모델에 대한 제약업계의 관심과, 환자 유래 세포주의 규모 확대를 추진하는 학술 컨소시엄의 노력이 맞물려 지속적인 수요를 뒷받침하고 있습니다. BlueRock의 2상 시험 데이터와 Axol의 50계통 동종 패널은 연구용 시약을 넘어선 상업적 가능성을 입증하고 있습니다. 신경퇴행성 질환의 부담이 증가하고 있다는 점은 유도 만능 줄기세포(iPS 세포) 시장에서 뉴런 분야가 장기적으로 기여할 것임을 뒷받침합니다.
지역별 분석
북미는 2025년 매출의 38.91%를 차지했으며, 이는 FDA의 명확한 지침, NIH 및 CIRM의 지원 프로그램, 탄탄한 벤처 캐피탈 생태계를 반영하고 있습니다. 캐나다의 STEMCELL Technologies는 전 세계 학술 사용자 중 70%에게 배양 배지를 공급하고 있으며, 이로 인해 해당 지역이 중요한 공급원으로서의 입지를 강화하고 있습니다. 멕시코에 신설된 Lonza 시설은 수탁 제조가 비용 경쟁력이 있는 지역으로 이동하고 있음을 보여줍니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 11.67%를 나타낼 것으로 예측되며, 이는 모든 지역 중 가장 높은 성장률입니다. 일본의 조건부 승인 절차는 시장 출시까지의 기간을 최대 5년 단축시켜 세계 기업들이 제휴를 맺거나 임상시험을 이전하도록 유도하고 있습니다. 중국에서는 12억 달러 규모의 성(省) 차원 기금과 우시(Wuxi)사의 바이오리액터 증설로 인해 유도 만능 줄기세포 시장에서 최대 규모의 단일 신규 제조 거점이 형성되고 있습니다. 인도, 한국, 호주는 정부의 보조금 조정 및 중개 임상시험을 통해 시너지를 내며 성장세를 가속화하고 있습니다.
임상시험 건수 면에서는 독일, 프랑스, 영국이 주도적인 위치를 차지하고 있으며, 2024년에 통일된 MHRA 지침에 따라 국경 간 신청 절차가 효율화되었습니다. 이스라엘과 브라질은 각각 중동 및 아프리카와 남미 지역의 도입을 주도하고 있으며, 이 두 지역을 합친 시장 기여도는 8%에 달하고, 유도 만능 줄기세포 시장의 전 세계적 확산을 보여주고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the induced pluripotent stem cells market size is projected to expand from USD 2.37 billion in 2025 and USD 2.59 billion in 2026 to USD 4.14 billion by 2031, registering a CAGR of 9.83% between 2026 to 2031.
This report is Segmented by Derived Cell Type (Cardiomyocytes, Neurons, Hepatocytes, Fibroblasts, Keratinocytes, Others), Application (Drug Discovery, Disease Modeling, Toxicity Testing, Regenerative Medicine, Cell Therapy, and More), End User (Academic Institutes, and More), and Geography (North America, Europe, Asia-Pacific, MEA, South America). Market Forecasts are in Value (USD).
Global Induced Pluripotent Stem Cells Market Trends and Insights
Surge in iPSC-Enabled Drug Discovery and Toxicity Testing Demand
Pharmaceutical sponsors are switching from animal models to iPSC-derived cardiomyocytes and hepatocytes that flag human-specific toxicities, cutting Phase II failure rates by up to 35 percentage points. FUJIFILM Cellular Dynamics showed that iCell hepatocytes detected hidden liver liabilities in eight compounds that had cleared rodent screens, leading FDA reviewers to accept iPSC data in investigational new drug files in 2024. Takeda integrated these assays into 40% of its early pipeline by 2025, trimming preclinical timelines by six months and saving roughly USD 30 million per asset. Contract research organizations such as Charles River and Eurofins now charge USD 4,500 per compound for full iPSC toxicity panels, less than half the 2023 rate, broadening adoption among small biotechs. Growing regulatory acceptance under the U.S. 21st Century Cures Act and the EU's 3Rs principles further institutionalizes the practice.
Expanding Clinical Pipeline of iPSC-Derived Cell Therapies
Seventeen iPSC-based therapeutics were in Phase I or II worldwide by mid-2025, led by BlueRock Therapeutics' bemdaneprocel for Parkinson's disease, which delivered a 40% improvement on the Unified Parkinson's Disease Rating Scale at twelve months. Heartseed's HS-001 cardiac patch posted a 15% rise in left ventricular ejection fraction without serious adverse events, advancing toward Japan's conditional approval pathway that can cut three years from a typical launch schedule. Fate Therapeutics' FT596 off-the-shelf CAR-NK cells achieved 60% complete responses in B-cell lymphoma, outperforming autologous CAR-T benchmarks by 15 points. Century Therapeutics secured FDA clearance for CNTY-101 gamma-delta T cells for solid tumors, expanding the addressable oncology base. Collectively, these milestones sustain investor confidence in the induced pluripotent stem cells market.
High Cost and Process Complexity for Large-Scale GMP Production
ISO 13485 facilities, 30-day differentiation runs, and whole-genome release testing push batch costs to as high as USD 150,000, pricing many academic spin-outs out of the market. Media costs often exceed USD 2,000 per liter, and yield variability can reach 50%, hampering the reliable cost of goods. CDMOs charge up to USD 5 million for Phase I clinical material, a hurdle for seed-stage ventures. Cryopreservation losses of 30% force manufacturers to oversize production runs, inflating inventory overhead. Although automation cuts labor by 80%, setting up a 500-liter GMP suite still requires more than USD 10 million in capital, delaying scale-out in the induced pluripotent stem cells market.
Other drivers and restraints analyzed in the detailed report include:
- Robust Public and Private Funding Across U.S., EU, and Japan
- Advances in Non-Integrating Reprogramming and CRISPR Editing
- Fragmented Global Regulatory and Standardization Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cardiomyocytes accounted for 28.02% of the induced pluripotent stem cells market share in 2025, supported by pharmaceutical use in cardiotoxicity screening and by regenerative medicine trials such as Heartseed's HS-001 patch. Parallel progress in ventricular-patch trials could open therapeutic revenue streams as early as 2027.
Neurons remain the fastest-growing sub-segment at a forecast 10.06% CAGR. Pharmaceutical interest in Parkinson's and ALS models, combined with academic consortia scaling patient-derived lines, underpins sustained demand. BlueRock's Phase II data and Axol's 50-line isogenic panel validate commercial potential beyond research reagents. Growing neurodegenerative disease burden reinforces the long-run contribution of neurons to the induced pluripotent stem cells market.
Complete Report Scope:
- By Derived Cell Type
- Cardiomyocytes
- Neurons
- Hepatocytes
- Fibroblasts
- Keratinocytes
- Other Cell Types
- By Application
- Drug Discovery and Development
- Disease Modeling
- Toxicity Testing
- Regenerative Medicine
- Cell Therapy
- Tissue Engineering
- Other Applications
- By End User
- Academic and Research Institutes
- Pharmaceutical and Biotechnology Companies
- Contract Research Organizations
- Hospitals and Specialty Clinics
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America contributed 38.91% of 2025 turnover, reflecting FDA clarity, NIH and CIRM grant programs, and a dense venture-capital ecosystem. Canada's STEMCELL Technologies supplies culture media to 70% of academic users worldwide, reinforcing the region's critical input position. Mexico's new Lonza facility signals movement of contract manufacturing into cost-advantaged locales.
Asia-Pacific is projected to grow at 11.67% CAGR through 2031, the fastest among all regions. Japan's conditional approval pathway shortens launch timelines by up to five years, drawing global companies to partner or relocate trials. China's USD 1.2 billion provincial funds and WuXi bioreactor build-out create the largest single new manufacturing corridor for the induced pluripotent stem cells market. India, South Korea, and Australia collectively add momentum through coordinated government grants and translational trials.
Germany, France, and the United Kingdom dominate clinical trial counts, while harmonized MHRA guidance in 2024 streamlined cross-border submissions. Israel and Brazil spearhead Middle East & Africa and South America adoption respectively, lifting those combined regions to an 8% contribution and illustrating global diffusion of the induced pluripotent stem cells market.
- Applied StemCell Inc.
- Axol Bioscience
- BlueRock Therapeutics
- Cellino Biotech
- Century Therapeutics Inc.
- Cynata Therapeutics Ltd.
- Evotec
- Fate Therapeutics Inc.
- FUJIFILM Cellular Dynamics Inc.
- Hitachi
- Lonza Group
- Merck
- Ncardia BV
- Pluristyx Inc.
- REPROCELL Inc.
- Stem Cell Technologies
- Takara Bio
- Thermo Fisher Scientific
- Ushio Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge In IPCS-Enabled Drug Discovery & Toxicity Testing Demand
- 4.2.2 Expanding Clinical Pipeline of Ipsc-Derived Cell Therapies
- 4.2.3 Robust Public & Private Funding Across U.S., EU & Japan
- 4.2.4 Advances In Non-Integrating Reprogramming & CRISPR Editing
- 4.2.5 Adoption of Closed-System Automated GMP Bioreactors
- 4.2.6 Emerging Industrial Uses (Cultured Meat, iPS-Platelets)
- 4.3 Market Restraints
- 4.3.1 High Cost & Process-Complexity for Large-Scale GMP Production
- 4.3.2 Fragmented Global Regulatory & Standardization Requirements
- 4.3.3 Genetic Instability / Tumorigenicity Safety Concerns
- 4.3.4 Concentrated Patent Ownership Driving Royalty Pressure
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Derived Cell Type
- 5.1.1 Cardiomyocytes
- 5.1.2 Neurons
- 5.1.3 Hepatocytes
- 5.1.4 Fibroblasts
- 5.1.5 Keratinocytes
- 5.1.6 Other Cell Types
- 5.2 By Application
- 5.2.1 Drug Discovery and Development
- 5.2.2 Disease Modeling
- 5.2.3 Toxicity Testing
- 5.2.4 Regenerative Medicine
- 5.2.5 Cell Therapy
- 5.2.6 Tissue Engineering
- 5.2.7 Other Applications
- 5.3 By End User
- 5.3.1 Academic and Research Institutes
- 5.3.2 Pharmaceutical and Biotechnology Companies
- 5.3.3 Contract Research Organizations
- 5.3.4 Hospitals and Specialty Clinics
- 5.3.5 Other End Users
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 Applied StemCell Inc.
- 6.3.2 Axol Bioscience Ltd.
- 6.3.3 BlueRock Therapeutics
- 6.3.4 Cellino Biotech
- 6.3.5 Century Therapeutics Inc.
- 6.3.6 Cynata Therapeutics Ltd.
- 6.3.7 Evotec SE
- 6.3.8 Fate Therapeutics Inc.
- 6.3.9 FUJIFILM Cellular Dynamics Inc.
- 6.3.10 Hitachi Ltd.
- 6.3.11 Lonza Group AG
- 6.3.12 Merck KGaA
- 6.3.13 Ncardia BV
- 6.3.14 Pluristyx Inc.
- 6.3.15 REPROCELL Inc.
- 6.3.16 Stemcell Technologies Inc.
- 6.3.17 Takara Bio Inc.
- 6.3.18 Thermo Fisher Scientific Inc.
- 6.3.19 Ushio Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment