|
시장보고서
상품코드
2124884
치과용 3D 프린팅 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Dental 3D Printing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
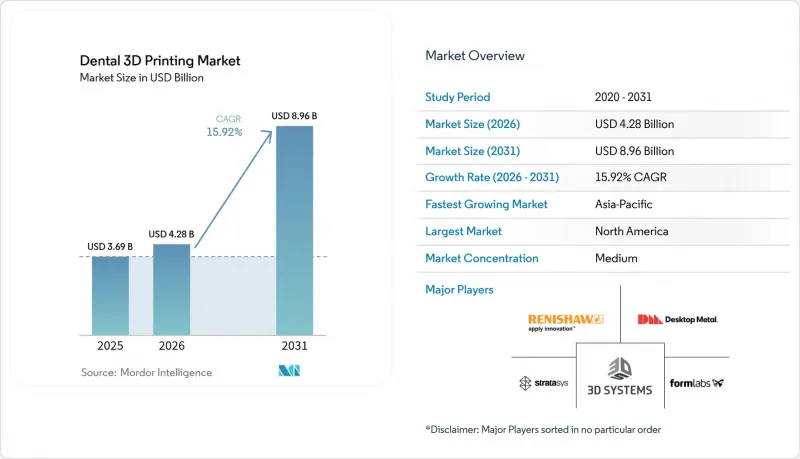
에 의하면, 치과용 3D 프린팅 시장 규모는 2025년 36억 9,000만 달러로 평가되었습니다. 2026년에는 42억 8,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 15.92%로 성장을 지속하여, 2031년에는 89억 6,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 제품 유형(장비, 재료, 서비스), 프린팅 기술(스테레오리소그래피, 선택적 레이저 소결법, PolyJet·머티리얼 제팅,디지털 라이트 프로세싱(DLP), 용융 적층 성형(FDM)), 소재 유형(수지, 금속, 플라스틱·폴리머 필라멘트, 세라믹), 용도(치과 임플란트, 보철 치과, 치아 교정, 외과용 가이드·모델),최종 사용자(치과 기공소, 치과 병원, 학술 연구 기관), 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 분류되어 있습니다. 시장 전망은 금액(달러)으로 표시되어 있습니다.
세계의 치과용 3D 프린팅 시장 동향 및 인사이트
심미 치과 및 심미 수복에 대한 수요 증가
심미 치과 치료는 더 이상 사치품이 아니라 당연한 것으로 여겨지게 되었습니다. 특히, 경력 성공을 아름다운 미소와 연결 짓는 밀레니얼 세대와 Z 세대 사이에서 이러한 경향이 두드러집니다. 현재 DLP용 레진에는 16가지 색상의 비타(Vita) 컬러 라이브러리와 조절 가능한 반투명도가 탑재되어 있어, 치과 기공소에서는 한 번의 프린팅으로 상아질의 헤일로 효과를 재현할 수 있을 뿐만 아니라, 마무리 작업에 드는 수고를 대폭 줄일 수 있습니다. 4유닛의 전치부 브리지의 경우, 레진 비용은 8-12달러,장비 가동 시간은 90분인 반면, 지르코니아 블랭크의 경우 40-60달러, 밀링 시간은 4시간이 소요됩니다. 2025년에 210만 건의 ‘#베니어’ 게시물이 등록되는 등, 소셜 미디어에서의 노출이 진료실 내 수요를 지속적으로 견인했습니다. ISO 20795-1 규격은 현재 적층 가공용 의치용 폴리머를 명시적으로 대상으로 하고 있어, 새로운 심미 재료에 대한 규제 장벽이 완화되고 있습니다. ‘당일 베니어’를 홍보하는 치과에서는 여전히 실험실에서 제작된 도자기에 의존하는 타 업체에 비해 사례 수락률이 15-20% 더 높은 것으로 보고되고 있습니다.
클리어 얼라이너와 맞춤형 보철물의 보급 확대
클리어 얼라이너를 이용한 치료는 2025년에 1,500만 건 이상으로 시작되어으며, 건당 20-40개의 프린팅된 스테이징 모델이 필요할 것으로 예측됩니다. 대량 맞춤화는 부분 틀니로도 확대되고 있으며, 유한 요소법을 이용한 모델링을 통해 클라스프의 힘을 최적화하고 법랑질의 마모를 줄이고 있습니다. 가격 탄력성이 신흥 시장에서의 보급을 뒷받침하고 있으며, 인도의 한 클리닉에서는 유연성이 뛰어난 프린팅 의치를 80-120달러에 판매하고 있어 아크릴 제품보다 35% 저렴합니다. FDA의 2024년 포인트 오브 케어(Point of Care) 지침에 따라, 교정 치과의사는 진료실 내에서 리테이너를 프린트할 수 있게 되어, 납기일이 10일에서 당일로 단축되었습니다. 환자별로 최적화된 에머전스 프로파일을 갖춘 임플란트 크라운은 조직 염증을 18-22% 감소시켜 적층 가공 기술의 임상적 우위를 입증하고 있습니다.
막대한 설비 투자 및 유지비
체어사이드 풀 세트 구성에는 3만 5,000-5만 달러의 비용이 소요되며, 여기에는 스캐너, 프린터, 포스트큐어 장치, 세척 스테이션, CAD 라이선스가 포함됩니다. 소모품 비용으로 연간 1,800-2,500달러가 추가로 소요되며, 수지 탱크 및 LCD 교체 비용도 경비를 증가시킵니다. 신용 비용이 높은 가격에 민감한 시장에서는 리스 옵션이 여전히 제한적입니다. 환율 변동에 따라 달러로 책정된 리스 요금은 현지 통화로 환산 시 최대 25%까지 상승할 수 있습니다.월40건 이하의 시술을 처리하는 클리닉의 경우, 투자 회수에는 2년 이상이 소요됩니다. EU에서 유해 폐기물로 분류되는 수지 폐기물의 처분에는 분기당 150-200유로의 비용이 발생하여, 이익률을 더욱 압박하고 있습니다.
부문별 분석
치과용 3D 프린팅 시장에서 서비스 부문은 가장 빠르게 성장하는 부문으로 부상하고 있으며, 치과 병원이 장비 구매보다 사례별 요금 체계를 선호하는 경향에 힘입어 연평균 성장률(CAGR) 16.61%로 확대되고 있습니다. 인쇄되는 크라운이나 얼라이너 모델 하나당 수지, 용제, 빌드 트레이가 소모되기 때문에 2025년 매출의 54.02%는 재료가 차지했습니다. 대규모 실험실 간에는 장비 수요가 여전히 견조하지만, 아웃소싱 모델을 통해 개인 개업 치과에서도 20만 달러를 하드웨어에 지출하지 않고도 티타늄 선택적 레이저 용융(SLM)을 이용할 수 있게 되었습니다. 이러한 변화는 자산을 최소화한 운영을 지향하는 의료 산업 전반의 동향과 부합합니다. 아웃소싱 사업자는 규모의 경제를 활용하여 레진을 대량 구매를 통해 할인된 가격에 조달하고, 야간에는 여러 대의 프린터를 가동하여 가동률을 80% 이상으로 유지하고 있습니다. 이러한 변화로 인해 치과의사를 오프사이트 프린터에 직접 연결해 주는 클라우드 기반 설계 포털의 소프트웨어 구독 수요도 증가하여, 행정 업무의 번거로움이 줄어들고 있습니다. 규제의 미묘한 차이가 도입 현황에 영향을 미치고 있습니다. 일본의 시설 등록 규정은 클리닉이 외부 서비스 센터를 이용하도록 유도하는 반면, 미국 FDA의 ‘포인트 오브 케어(Point of Care)’ 면제 규정은 일부 클리닉이 다시 ‘자체 제작’ 워크플로로 돌아가도록 작용하여, 도입 현황은 지역별로 편차를 보이고 있습니다.
스테레오 리소그래피는 초기 우위와 폭넓은 수지 제품군 덕분에 2025년 전 세계 생산량의 34.27%를 차지했습니다. 한편, 디지털 라이트 프로세싱(DLP)은 5초 만에 층을 경화시키고 50마이크론 이하의 해상도를 제공하여 마무리 연마 작업을 최소화할 수 있다는 점에서 클리닉으로부터 높은 평가를 받고 있으며, 연평균 성장률(CAGR) 17.65%를 기록할 전망입니다. DLP의 조형 속도는 시간당 30-40mm로, 실험실에서 최대 1,000아치를 생산하는 얼라이너 모델의 야간 일괄 처리에서 필수적인 기술이 되고 있습니다. PolyJet은 여전히 프리미엄 틈새 시장이며, 다중 재료 의치 분야에서 높은 평가를 받고 있지만, 1리터당 400달러에 달하는 제트 비용과 지지재 폐기량이 많다는 점이 제약으로 작용하고 있습니다. Fused Deposition Modeling(FDM)은 교정용 모델 분야에서 여전히 사용되고 있지만, DLP의 단가가 3,000-4,000달러로 수렴함에 따라 치과용 3D 프린팅 시장에서의 점유율은 축소되고 있습니다. ISO 프로토콜에서는 수지의 기계적 특성이 중시되고 있으며, 이것이 FDM에 대한 추가적인 압박 요인이 되고 있습니다.
지역별 분석
북미는 구강 내 스캐너 보급률이 68%에 달하고, 프린팅 및 밀링을 통한 수복물을 동등한 기준으로 보상하는 CDT 청구 코드의 지원에 힘입어 2025년 전 세계 매출의 37.18%를 차지했습니다. 2025년 한 해에만 14종의 새로운 치과용 수지가 FDA 승인을 획득했고, 승인 주기가 8개월로 단축되어 재료 선택의 폭이 넓어졌습니다. 캐나다에서는 2024년에 공적 보험 적용 범위가 확대되면서, 비용 효율을 중시하는 가철식 보철물에 대한 수요가 증가하고 있습니다. 니어쇼어링의 진전에 따라 미국의 치과 기공소는 멕시코에 시설을 개설하고, 시간당 12-18달러의 CAD(컴퓨터 지원 설계) 인력을 활용하면서도 24시간 이내의 납기를 유지하고 있습니다. 경쟁이 격화되면서 수지 제품의 매출 총이익률은 40%까지 압박받고 있습니다.
유럽에서는 MDR(의료기기 규정)을 둘러싼 마찰이 있음에도 불구하고, 표준화된 규정이 현재 27개 시장에 적용됨에 따라 견조한 성장세를 보이고 있습니다. 영국의 국민보건서비스(NHS)는 3곳의 중앙 집중형 프린트 허브를 시범 도입하여 의치 대기 시간을 14일에서 5일로 단축했습니다. 남유럽에서는 의료 서비스가 부족한 지역의 클리닉에 대해 설비 비용의 절반을 보조함으로써, 2025년까지 이 수준에 도달했습니다. ISO 작업반은 2027년까지 의치용 폴리머의 최종 규격을 제정할 전망이며, 이를 통해 유럽 대륙에서의 도입이 더욱 원활해질 것으로 보입니다.
아시아태평양은 성장세가 가장 두드러진 지역으로, 연평균 성장률(CAGR) 18.51%를 나타낼 것으로 예측됩니다. 중국의 구강 보건 행동 계획에서는 2030년까지 충치 치료 보장률을 80%로 높이는 것을 목표로 하고 있으며, 국내 OEM 업체들은 유럽 및 미국의 경쟁사보다 30-40% 저렴한 가격으로 제품을 제공합니다. 일본에서는 무치악 고령자들이 임플란트 오버덴처 수요를 주도하고 있으며, 금속 3D 프린팅 기술로 인해 프레임워크 비용이 절반으로 줄었습니다. 인도의 기업 체인은 실험실을 일원화하여 각 실험실이 50-100개의 클리닉에 서비스를 제공하고 있으며, ‘아유슈만 바라트’ 의치 급여 제도를 활용하고 있습니다. 규제의 다양성은 여전히 존재하며, 아세안(ASEAN)에서는 여전히 10가지 유형의 승인이 필요하여 시장 출시까지의 기간이 1년 연장되고 있습니다.
중동 및 아프리카와 남미는 새로운 성장 기회를 내포하고 있습니다. GCC는 치과 관광 유치를 위해 최첨단 디지털 실험실에 자금을 투자하고 있습니다. 브라질은 18%의 수입 관세를 통해 국내 산업을 보호하고 있지만, 국내 수지 생산을 통해 비용 절감의 혜택을 누리고 있습니다. 남아프리카의 민간 클리닉은 수익성이 높은 심미 치과 시술을 위해 프린터에 투자하고 있지만, 지방의 공공시설에서는 도입이 더딘 실정입니다. 인력 부족(사하라 이남 아프리카 전역에서 CAD 교육을 받은 기술자는 500명 미만)으로 인해 하드웨어가 갖춰져 있어도 생산 능력이 제한되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the dental 3D printing market size is expected to grow from USD 3.69 billion in 2025 to USD 4.28 billion in 2026 and is forecast to reach USD 8.96 billion by 2031 at 15.92% CAGR over 2026-2031.
This report is Segmented by Product Type (Equipment, Materials, Services), Printing Technology (Stereolithography, SLS, Polyjet, DLP, FDM), Material Type (Resin, Metal, Polymer, Ceramic), Application (Implants, Prosthodontics, Orthodontics, Surgical Guides), End User (Labs, Clinics, Academia), and Geography (North America, Europe, Asia-Pacific, MEA, South America). Market Forecasts are in Value (USD).
Global Dental 3D Printing Market Trends and Insights
Rising Demand for Cosmetic Dentistry & Aesthetic Restorations
Cosmetic procedures have moved from luxury to expectation, especially among millennials and Gen Z cohorts who link career success to smile aesthetics. DLP resins now ship with 16-shade Vita libraries and tunable translucency, letting labs replicate dentin halos in a single print run while slashing finishing labor. A four-unit anterior bridge costs USD 8-12 in resin and 90 minutes of machine time, versus USD 40-60 for zirconia blanks and 4 hours of milling. Social media exposure, exemplified by 2.1 million #veneers posts in 2025, continues to drive chairside demand. ISO 20795-1 now explicitly covers additive denture polymers, smoothing regulatory paths for new cosmetic materials. Practices that advertise same-day veneers report 15-20% higher case acceptance rates than peers who still rely on lab-based porcelain.
Increasing Adoption of Clear Aligners & Customized Prosthetics
Clear-aligner treatment started at over 15 million in 2025, each requiring 20-40 printed staging models. Mass customization is also spreading to partial dentures, where finite-element modeling tailors clasp forces and reduces enamel wear. Price elasticity drives uptake in emerging markets: Indian clinics sell a flexible-printed denture for USD 80-120, undercutting acrylic by 35%. The FDA's 2024 point-of-care guidance allows orthodontists to print retainers on-site, compressing delivery from 10 days to same-day. Implant crowns with patient-specific emergence profiles show 18-22% lower tissue inflammation, underscoring the additive's clinical edge.
High Capital Investment & Maintenance
A full chairside setup costs USD 35,000-50,000 and includes a scanner, printer, post-cure, wash station, and CAD licenses. Consumables add USD 1,800-2,500 annually, and resin-tank and LCD replacements compound expenses. Leasing options remain scarce in price-sensitive markets where credit costs are high; foreign-exchange swings lift USD-denominated leases by up to 25% in local currency. Return on investment extends beyond 2 years for offices handling fewer than 40 cases per month. Disposal of resin waste, classified as hazardous in the EU, costs EUR 150-200 per quarter, further eroding margins.
Other drivers and restraints analyzed in the detailed report include:
- Cost Reduction & Accuracy Improvements in Dental 3D Printers
- Chairside Intra-Oral-Scanner Integration Enabling Same-Day Restorations
- Regulatory Variability for Material Certification
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services are emerging as the fastest-growing slice of the Dental 3D Printing market, advancing at a 16.61% CAGR as practices favor per-case fees over capital purchases. Materials still generated 54.02% of 2025 revenue because every printed crown or aligner model consumes resin, solvent, and build trays. Equipment demand remains healthy among large labs, yet the outsourcing model allows solo offices to access selective laser melting of titanium without spending USD 200,000 on hardware. This pivot aligns with broader healthcare trends toward asset-light operations. Bureau operators leverage scale benefits, buying resin at bulk discounts and running multi-printer farms overnight to keep utilization above 80%. The shift also lifts software subscriptions for cloud-based design portals that link dentists directly to off-site printers, reducing administrative friction. Regulatory nuance shapes uptake; Japan's facility-registration rules push clinics toward external service centers, while the FDA's point-of-care exemption in the United States nudges some offices back to do-it-yourself workflows, creating a patchwork adoption map.
Stereolithography accounted for 34.27% of global volume in 2025, thanks to an early lead and a broad resin catalog. Digital Light Processing, however, will record a 17.65% CAGR as clinics prize its 5-second layer cure and sub-50-micron resolution, which minimizes post-finish polishing. DLP's build rates of 30-40 mm per hour make it indispensable for overnight aligner-model batches where labs output up to 1,000 arches. PolyJet remains a premium niche, prized for multi-material dentures but limited by USD 400-per-liter jets and high support-material waste. Fused Deposition Modeling lingers in orthodontic models, yet its Dental 3D Printing market share is shrinking as DLP unit prices converge toward USD 3,000-4,000. ISO protocols favor resins' mechanical properties, further pressuring FDM.
Complete Report Scope:
- By Product Type
- Equipment
- Materials
- Services
- By Printing Technology
- Stereolithography
- Selective Laser Sintering
- PolyJet / Material Jetting
- Digital Light Processing
- Fused Deposition Modelling
- By Material Type
- Resin
- Metal
- Plastic / Polymer Filament
- Ceramic
- By Application
- Dental Implants
- Prosthodontics
- Orthodontics
- Surgical Guides & Models
- By End User
- Dental Laboratories
- Dental Clinics
- Academic & Research Institutes
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America contributed 37.18% of global 2025 revenue, supported by 68% intra-oral-scanner penetration and CDT billing codes that reimburse printed and milled restorations at parity. Fourteen new dental resins secured FDA clearance in 2025 alone, slashing approval cycles to eight months and widening material choice. Canada's 2024 public-insurance expansion adds restorative demand for cost-sensitive removable prosthetics. Near-shoring sees U.S. labs opening facilities in Mexico to tap USD 12-18/hour CAD labor while maintaining 24-hour turnaround. Competitive intensity is high, squeezing resin gross margins to 40%.
Europe shows robust growth despite MDR friction, as standardized rules now span 27 markets. The NHS in England trialed three centralized printing hubs that cut denture queues from 14 to 5 days. Southern Europe is expected to catch up by 2025, with subsidies covering half of the equipment costs for practices in underserved areas. ISO working groups expect final denture-polymer standards by 2027, likely to further streamline continental rollouts.
Asia-Pacific is the fastest-growing region, forecast to grow at an 18.51% CAGR. China's oral-health action plan targets 80% caries-treatment coverage by 2030, and domestic OEMs undercut Western rivals by 30-40% on price. Japan's edentulous seniors drive implant overdenture demand, where metal printing halves framework costs. Indian corporate chains centralize labs to serve 50-100 clinics each, leveraging Ayushman Bharat's denture benefits. Regulatory diversity persists; ASEAN states still require ten distinct approvals, elongating launches by a year.
The Middle East & Africa and South America offer emerging upside. GCC nations fund state-of-the-art digital labs to lure dental tourists. Brazil protects local industry through 18% import tariffs, but gains cost relief from domestic resin production. South African private clinics invest in printers for high-margin cosmetic procedures, but rural public facilities lag behind. Workforce shortages-fewer than 500 CAD-trained technicians across sub-Saharan Africa-limit capacity even when hardware is present.
- 3D Systems
- Align Technology
- Carbon Inc.
- Dentsply Sirona
- Desktop Metal
- EOS GmbH
- EnvisionTEC
- Formlabs Inc.
- Ivoclar Vivadent
- Kulzer
- Prodways Group
- Renishaw plc
- Roland DG Corporation
- SLM Solutions Group AG
- SprintRay
- Stratasys
- Straumann Group
- Voxeljet AG
- Zortrax S.A
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Cosmetic Dentistry & Aesthetic Restorations
- 4.2.2 Increasing Adoption of Clear Aligners & Customised Prosthetics
- 4.2.3 Cost Reduction & Accuracy Improvements in Dental 3D Printers
- 4.2.4 Chairside Intra-Oral-Scanner Integration Enabling Same-Day Restorations
- 4.2.5 Eco-Friendly Bio-Resorbable Resins Demand
- 4.2.6 Increasing Incidence of Dental Caries & Edentulism
- 4.3 Market Restraints
- 4.3.1 High Capital Investment & Maintenance
- 4.3.2 Regulatory Variability for Material Certification
- 4.3.3 IP Concerns Around Intra-Oral Scan Data/Files
- 4.3.4 Shortage Of Trained Digital Dental Technicians
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Product Type
- 5.1.1 Equipment
- 5.1.2 Materials
- 5.1.3 Services
- 5.2 By Printing Technology
- 5.2.1 Stereolithography
- 5.2.2 Selective Laser Sintering
- 5.2.3 PolyJet / Material Jetting
- 5.2.4 Digital Light Processing
- 5.2.5 Fused Deposition Modelling
- 5.3 By Material Type
- 5.3.1 Resin
- 5.3.2 Metal
- 5.3.3 Plastic / Polymer Filament
- 5.3.4 Ceramic
- 5.4 By Application
- 5.4.1 Dental Implants
- 5.4.2 Prosthodontics
- 5.4.3 Orthodontics
- 5.4.4 Surgical Guides & Models
- 5.5 By End User
- 5.5.1 Dental Laboratories
- 5.5.2 Dental Clinics
- 5.5.3 Academic & Research Institutes
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 3D Systems Corporation
- 6.3.2 Align Technology Inc.
- 6.3.3 Carbon Inc.
- 6.3.4 Dentsply Sirona Inc.
- 6.3.5
Desktop Metal
- 6.3.6 EOS GmbH
- 6.3.7 EnvisionTEC
- 6.3.8 Formlabs Inc.
- 6.3.9 Ivoclar Vivadent AG
- 6.3.10 Kulzer GmbH
- 6.3.11 Prodways Group
- 6.3.12 Renishaw plc
- 6.3.13 Roland DG Corporation
- 6.3.14 SLM Solutions Group AG
- 6.3.15 SprintRay Inc.
- 6.3.16 Stratasys Ltd.
- 6.3.17 Straumann Group
- 6.3.18 Voxeljet AG
- 6.3.19 Zortrax S.A
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment