

|
시장보고서
상품코드
2124897
백신 위탁생산 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Vaccine Contract Manufacturing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 백신 위탁생산 시장 규모는 43억 3,000만 달러로 추정되고 2025년 39억 달러에서 확대해, 2031년에는 73억 1,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 11.05%로 성장할 것으로 전망됩니다.
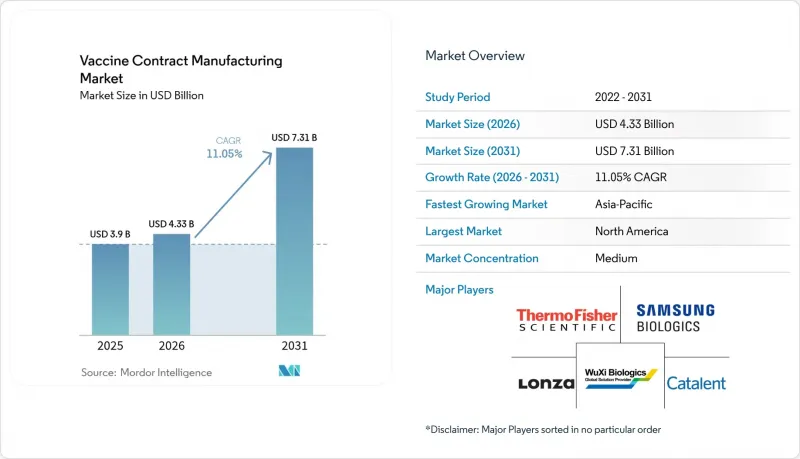
본 보고서는 백신 유형(불활성화 백신, 약독화 생백신, RNA 백신, 기타), 공정(다운스트림 공정{분석·품질 관리(QC) 검사 등} 및 업스트림 공정{세균 발현 시스템, 포유류 발현 시스템 등}), 사업 규모(전임상 단계, 임상 단계, 기타),최종 사용자(인간, 수의학), 지역(북미, 유럽, 아시아태평양, 기타)별로 분류되어 있습니다. 시장 규모와 전망은 금액(달러)으로 표시되어 있습니다.
세계의 백신 위탁생산 시장 동향 및 인사이트
일회용 및 모듈식 시설의 발전
일회용 바이오리액터 및 조립식 클린룸의 도입으로 그린필드 건설 기간이 7년에서 2년 미만으로 단축되어, 스폰서는 수요 급증에 맞추어 설비 투자를 조정할 수 있게 되었습니다. 바커 케미(Wacker Chemie)사의 1억 200만 유로(1억 1,900만 달러) 규모의 모듈식 mRNA 제조 공장은 표준화된 블록을장기간에 걸친 재설계 없이도 여러 관할 구역에 도입할 수 있음을 보여주고 있으며, 이를 통해 백신 위탁생산 시장은 병원체의 변화에 유연하게 대응할 수 있게 됩니다. 자본 부담이 적은 개발사는 후기 단계의 생산 능력을 활용할 수 있게 되었으며, 한편 규제 당국은 현재 모듈식 시설을 기존 시설과 동등하게 간주하고 있어 검증 주기가 단축되고 전 세계적인 승인 절차가 원활해지고 있습니다.
정부의 예방접종 이니셔티브 및 자금 풀
공공 조달 기관은 현재 구매 예산과 국내 생산 능력 목표를 연계하고 있습니다. Gavi의 12억 달러 규모의 ‘아프리카 백신 제조 가속화 프로그램’은 보조금 지급을 국내 생산량과 연계하고 있으며,미국의 ‘프로젝트 넥스트젠(Project NextGen)’은 50억 달러 규모의 차세대 코로나19 관련 지출을 국내 파트너 기업에 배정하고 있어, 이를 통해 백신 위탁생산 시장에 수년에 걸친 생산량 가시성이 확보되고 있습니다.
바이오로직스 등급 원료 비용의 급등
2023년 말까지 실험용 자재 공급업체의 절반 이상이 카탈로그 가격을 인상했으며, 특히 크로마토그래피용 수지의 가격 상승률은 일반 원자재보다 높았습니다. 이로 인해 고정 가격의 마스터 서비스 계약으로 고정되어 있던 CDMO의 이익률이 압박을 받았습니다. 지질 원료 공급업체가 제한적이어서 RNA 백신의 원가 변동이 심화되었으며, 소규모 제조 시설에서는 헤지(위험 회피)를 위한 충분한 규모를 확보하지 못했습니다.
부문별 분석
백신 위탁생산 시장은 여전히 불활성화 백신이 주도하고 있으며, 수십 년에 걸친 안전성 데이터와 공공 프로그램을 통한 확고한 수요 덕분에 2025년에는 33.02%의 점유율을 확보했습니다. 그러나 RNA 백신은 적응성이 높은 서열 설계와 전임상시험 기간 단축에 힘입어 연평균 성장률(CAGR) 18.07%라는 가장 강력한 성장세를 기록하고 있습니다. 약독화 생백신은 지속적인 점막 면역이 필수적인 소아용 부문에서 여전히 중요한 역할을 하고 있지만, 규제 당국이 신규 병원체에 대해서는 비복제형 벡터를 권장하고 있어 성장 속도는 둔화되고 있습니다.
각 CDMO 기업은 스테인리스 스틸 생산 라인과 일회용 생산 라인을 병행하여 운영하고 있으며, 이를 통해 재무 기반이 탄탄한 고객사는 교차 오염의 위험 없이 RNA 백신의 생산량을 확대하는 동시에 기존 생산량을 안정적으로 유지할 수 있게 되었습니다. 아쥬반트 대응 아단위 백신은 낮은 항원 부하로 항체가를 향상시키는 새로운 사포닌 및 톨 유사 수용체 작용제의 지원에 힘입어, 고령자 및 면역 결핍자층에서 지지를 넓혀가고 있습니다. 톡소이드의 생산량은 정체를 보이고 있으며, 집단 면역이 확립된 시장의 부스터 접종 캠페인으로 한정되어 있지만, 안정적인 기본 가동률을 추구하는 제조업체에게는 여전히 중요한 위치를 차지하고 있습니다. 기술 구성의 다양화에 따라 백신 위탁생산 시장에서는 가동 중단 시간을 최소화하면서 불활성화 백신과 유전자 공학 플랫폼 사이를 유연하게 전환할 수 있는 설비 투자 유연성이 높은 생산 라인에 대한 투자가 진행되고 있습니다.
2025년 매출의 57.62%를 다운스트림 공정이 차지했으며, 정제 및 충전·마무리 공정은 백신 위탁생산 시장에서 가장 수익성이 높은 부문으로 자리 잡았습니다. 코로나19 이후 순도 규격이 엄격해짐에 따라, 각 CDMO 기업들은 전환 시간을 단축하는 대용량 크로마토그래피 스키드나 일회용 심층 필터의 도입을 피할 수 없게 되었습니다. 대조적으로, 업스트림 공정에서는 피드배치(fed-batch) 방식의 강화와 미생물 연속 배양 모드의 도입으로 규모가 확대되고 있어, 제조 원가는 절감되는 반면 다운스트림 공정의 병목 현상에 대한 부담은 증가하고 있습니다.
2026년부터 2031년에 걸쳐, 다가 단백질용 곤충 세포 시스템의 개선에 힘입어 업스트림 공정 활동은 연평균 성장률(CAGR) 14.82%로 확대될 것으로 예측됩니다. 스테인리스 시스템의 유휴화를 방지하기 위해 각 공장에서는 일회용 생산 바이오리액터에 공급하는 하이브리드형 스테인리스 시드 트레인을 채택하여 속도와 감가상각비의 균형을 맞추고 있습니다. 분석을 통한 품질 관리는 각 공정에 통합되어 있으며, 현재는 공정 내 릴리스(in-process release)를 위해 아트라인 분광법이 도입되어 있습니다. 규제 당국이 주사기의 무결성 및 입자 검사를 최종적인 위험 방지 조치로 간주하고 있기 때문에 충전 및 마무리 서비스에는 고액의 수수료가 부과되고 있습니다. 베터(Vetter)사가 15억 유로를 투자하여 2개 거점에 건설을 추진하고 있는 사례는 백신 위탁생산 시장에서 무균 생산 능력을 둘러싼 방어적인 경쟁 우위를 여실히 보여주고 있습니다.
지역별 분석
북미는 대규모 정부 인센티브와 그린필드 바이오프로세스 시설에 대한 신속한 인허가 절차를 배경으로, 2025년 백신 위탁생산 시장 매출의 46.21%를 차지했습니다. 머크(Merck)의 10억 달러 규모 더럼 시설은 3D 프린팅 부품과 생성형 AI를 활용한 검사를 통합하여 사이클 타임 지표의 새로운 벤치마크를 확립하고 있습니다. 캐나다는 지역 생산 기반을 강화하고 있으며, 2025년까지 가동을 시작한 모더나의 1억 회분 생산 능력을 갖춘 라발 공장은 공급의 국내 회귀 노력을 강조하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 11.68%를 기록하며 가장 빠르게 성장하는 지역입니다. 중국에서는 2023년 바이오의약품 매출이 6,506억 위안(人民元)에 달했으며, 인도는 수십 년에 걸친 유니세프(UNICEF)에 대한 조달 실적을 바탕으로 한 양산 효율성을 활용하고 있습니다. 삼성바이오로직스와의 14억 달러 규모의 장기 계약은 한국의 품질 관리 체계에 대한 다국적 기업의 신뢰를 보여주는 반면, 인도네시아와 태국은 그린필드 RNA 제조 시설을 유치하기 위해 세제 혜택 조치를 도입하고 있습니다. 대학들이 화학 엔지니어를 GMP 연수에 파견함으로써 해당 지역의 기술 기반이 확대되고 있으며, 검증 및 문서화 분야에서 기존에 존재하던 격차가 점차 줄어들고 있습니다.
유럽은 일관된 EMA 지침과 국경을 초월한 로트 릴리스 승인을 바탕으로 여전히 전략적 핵심 축으로 자리 잡고 있습니다. 독일이 Gavi에 6억 유로를 기부하겠다고 약속한 것은 산업 정책이 세계 보건 목표와 부합함을 보여주는 것이며, EU 내 공장은 유니세프 입찰에서 계속해서 중심적인 위치를 차지하고 있습니다. 동유럽 국가들은 EU의 품질 기준을 채택하면서도 낮은 인건비를 내세워, 통관 지연을 피하면서 비용 차익을 추구하는 2차 CDMO를 유치하고 있습니다. 중동 및 아프리카와 남미는 현재 시장 점유율이 작지만, ‘아프리카 백신 제조 가속화 프로그램(African Vaccine Manufacturing Accelerator)’과 같은 야심 찬 건설 프로그램이 전개되고 있습니다. 이러한 노력은 기술 이전 협정이 성숙해짐에 따라 2030년까지 백신 위탁생산 시장의 지역 분포를 변화시킬 가능성이 있습니다. 특히 초저온 창고의 경우 인프라 격차가 여전히 존재하지만, 자금원은 해당 지역의 질병 부담 우선순위에 부합하는 설비 업그레이드에 투입되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the vaccine contract manufacturing market size in 2026 is estimated at USD 4.33 billion, growing from 2025 value of USD 3.90 billion with 2031 projections showing USD 7.31 billion, growing at 11.05% CAGR over 2026-2031.
This report is Segmented by Vaccine Type (Inactivated, Live-Attenuated, RNA, and More), Process (Downstream {Analytical & QC, and More} and Upstream {Bacterial, Mammalian, and More), Scale of Operations (Preclinical, Clinical, and More), End User (Human and Veterinary), and Geography (North America, Europe, Asia-Pacific, and More). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Vaccine Contract Manufacturing Market Trends and Insights
Advancements In Single-Use and Modular Facilities
Single-use bioreactors and prefabricated cleanrooms cut green-field build times from seven years to under two, letting sponsors align capital outlay with demand surges. Wacker Chemie's EUR 102 million (USD 119 million) modular mRNA plant shows how standardized blocks can be lifted into multiple jurisdictions without lengthy redesigns, giving the vaccine contract manufacturing market elasticity for pathogen shifts. Capital-light developers gain access to late-phase capacity, while regulators now treat modular suites as equivalent to traditional spaces, trimming validation cycles and smoothing global dossier filings.
Government Immunization Initiatives and Funding Pools
Public buyers now couple purchase budgets with local-capacity targets. Gavi's USD 1.2 billion African Vaccine Manufacturing Accelerator ties grant disbursement to in-country output, and the U.S. Project NextGen steers USD 5 billion of next-generation COVID-19 spending to domestic partners, giving the vaccine contract manufacturing market multi-year volume visibility.
Escalating Biologics-Grade Raw-Material Costs
More than half of lab suppliers raised catalog prices by end-2023, with chromatography resin inflation outpacing general inputs. This eroded CDMO margins locked into fixed-price master service agreements. Limited lipid vendors intensified cost swings for RNA vaccines, and smaller plants lacked hedging scale.
Other drivers and restraints analyzed in the detailed report include:
- Expansion Of Global Pediatric Vaccine Schedules
- CDMO Platform Bundling For mRNA And Viral-Vector Tech
- Cold-Chain Gaps in Emerging Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The vaccine contract manufacturing market continues to be led by inactivated products, which secured a 33.02% share in 2025 due to decades-long safety data and established demand from public programs. However, RNA vaccines are posting the strongest expansion at 18.07% CAGR, propelled by adaptable sequence design and shorter pre-clinical timelines. Live-attenuated candidates still serve pediatric clusters where durable mucosal immunity is essential, but growth remains slower as regulators favor non-replicating vectors for new pathogens.
CDMOs run parallel stainless and single-use lines, allowing high-balance-sheet clients to keep legacy volume steady while ramping RNA batches without cross-contamination risk. Adjuvant-ready subunit shots gain traction for elderly and immunocompromised cohorts, supported by new saponin and toll-like receptor agonists that boost titers at lower antigen load. Toxoid volumes plateau, limited to booster campaigns in markets with established herd immunity, yet remain critical for manufacturers seeking steady baseline utilization. The diverging technology mix pushes the vaccine contract manufacturing market to invest in capex-flexible suites that can shift between inactivated and genetic platforms with minimal downtime.
Downstream steps captured 57.62% of 2025 revenue, making purification and fill-finish the most lucrative node in the vaccine contract manufacturing market. Purity specs tightened post-COVID-19, compelling CDMOs to install high-capacity chromatography skids and single-use depth filters that cut changeover hours. In contrast, upstream runs are scaling through fed-batch intensification and microbial continuous modes, trimming the cost of goods but driving more load into downstream bottlenecks.
Between 2026 and 2031, upstream activities are projected to grow at 14.82% CAGR, spurred by improved insect-cell systems for multivalent proteins. To prevent idle stainless systems, plants adopt hybrid seeds-stainless seed trains feeding single-use production bioreactors, balancing speed and depreciation costs. Analytical quality control weaves through each node, now embracing at-line spectroscopy for in-process release. Fill-finish services fetch premium fees because regulators see syringe integrity and particulate inspection as final risk barriers. Vetter's EUR 1.5 billion dual-site build illustrates the defensive moat around sterile capacity in the vaccine contract manufacturing market.
Complete Report Scope:
- By Vaccine Type
- Inactivated Vaccines
- Live-attenuated Vaccines
- RNA Vaccines
- Subunit Vaccines
- Toxoid-based Vaccines
- By Process
- Downstream
- Analytical & QC Studies
- Fill & Finish
- Packaging
- Other Downstream Processes
- Upstream
- Bacterial Expression Systems
- Baculovirus / Insect Expression Systems
- Mammalian Expression Systems
- Yeast Expression Systems
- Other Upstream Processes
- Downstream
- By Scale of Operations
- Preclinical
- Clinical
- Commercial
- By End User
- Human
- Veterinary
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America contributed 46.21% of vaccine contract manufacturing market revenue in 2025 on the back of sizable public incentives and rapid permitting pathways for green-field bioprocess sites. Merck's USD 1 billion Durham facility integrates 3D-printed components and generative-AI inspection, setting new benchmarks for cycle-time metrics. Canada augments regional depth, with Moderna's 100-million-dose Laval plant expected online by 2025, underscoring commitment to reshoring supply.
Asia Pacific is the fastest-growing territory, posting an 11.68% CAGR, as China's biopharma sales hit CNY 650.6 billion in 2023 and India leverages volume efficiencies built on decades of UNICEF procurement. Samsung Biologics' USD 1.4 billion long-term contract shows multinational trust in Korean quality frameworks, while Indonesia and Thailand roll out tax holidays to lure green-field RNA suites. The region's skill base widens as universities funnel chemical engineers into GMP apprenticeships, narrowing historical gaps in validation and documentation.
Europe remains a strategic pillar, supported by cohesive EMA guidance and cross-border batch release recognition. Germany's EUR 600 million pledge to Gavi signals alignment of industrial policy with global health goals, keeping EU plants central to UNICEF tenders. Eastern European states pitch lower labor costs while adopting EU quality codes, drawing second-tier CDMOs seeking cost arbitrage without customs delays. The Middle East & Africa and South America represent smaller shares today but showcase ambitious build programs like the African Vaccine Manufacturing Accelerator. These initiatives could shift the vaccine contract manufacturing market geography by 2030 as technology transfer agreements mature. Infrastructure gaps persist, especially in ultra-cold warehousing, yet funding streams earmark upgrades that dovetail with regional disease-burden priorities.
- Ajinomoto Bio-Pharma Services
- Catalent
- Batavia Biosciences
- CJ CheilJedang (Batavia Biosciences)
- Curia Global
- Emergent Bio Solutions
- FUJIFILM
- CordenPharma
- IDT Biologika
- Lonza Group
- Recipharm
- Richter-Helm BioLogics
- Samsung Group
- Thermo Fisher Scientific
- Wuxi Biologics
- Serum Institute of India
- SK bioscience
- Bavarian Nordic
- BioNTech Manufacturing Services
- Sanofi Pasteur (Valneva JV)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Advancements In Single-Use And Modular Facilities
- 4.2.2 Government Immunization Initiatives And Funding Pools
- 4.2.3 Expansion Of Global Pediatric Vaccine Schedules
- 4.2.4 CDMO Platform Bundling For mRNA And Viral-Vector Tech
- 4.2.5 Near-Shoring Mandates From Pandemic-Era Supply-Chain Reviews
- 4.2.6 Rapid Adoption Of Digital Quality-By-Design Analytics
- 4.3 Market Restraints
- 4.3.1 Escalating Biologics-Grade Raw-Material Costs
- 4.3.2 Cold-Chain Gaps In Emerging Markets
- 4.3.3 Regulatory Lag In Tech-Transfer Validation
- 4.3.4 Post-COVID Idle Capacity Creating Price Pressure
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Vaccine Type
- 5.1.1 Inactivated Vaccines
- 5.1.2 Live-attenuated Vaccines
- 5.1.3 RNA Vaccines
- 5.1.4 Subunit Vaccines
- 5.1.5 Toxoid-based Vaccines
- 5.2 By Process
- 5.2.1 Downstream
- 5.2.1.1 Analytical & QC Studies
- 5.2.1.2 Fill & Finish
- 5.2.1.3 Packaging
- 5.2.1.4 Other Downstream Processes
- 5.2.2 Upstream
- 5.2.2.1 Bacterial Expression Systems
- 5.2.2.2 Baculovirus / Insect Expression Systems
- 5.2.2.3 Mammalian Expression Systems
- 5.2.2.4 Yeast Expression Systems
- 5.2.2.5 Other Upstream Processes
- 5.2.1 Downstream
- 5.3 By Scale of Operations
- 5.3.1 Preclinical
- 5.3.2 Clinical
- 5.3.3 Commercial
- 5.4 By End User
- 5.4.1 Human
- 5.4.2 Veterinary
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Ajinomoto Bio-Pharma Services
- 6.3.2 Catalent
- 6.3.3 Batavia Biosciences
- 6.3.4 CJ CheilJedang (Batavia Biosciences)
- 6.3.5 Curia Global
- 6.3.6 Emergent BioSolutions
- 6.3.7 Fujifilm Diosynth Biotechnologies
- 6.3.8 CordenPharma
- 6.3.9 IDT Biologika
- 6.3.10 Lonza
- 6.3.11 Recipharm
- 6.3.12 Richter-Helm BioLogics
- 6.3.13 Samsung Biologics
- 6.3.14 Thermo Fisher Scientific
- 6.3.15 WuXi Biologics
- 6.3.16 Serum Institute of India
- 6.3.17 SK bioscience
- 6.3.18 Bavarian Nordic
- 6.3.19 BioNTech Manufacturing Services
- 6.3.20 Sanofi Pasteur (Valneva JV)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


