|
시장보고서
상품코드
2124917
카셰어링 텔레매틱스 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Car Sharing Telematics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
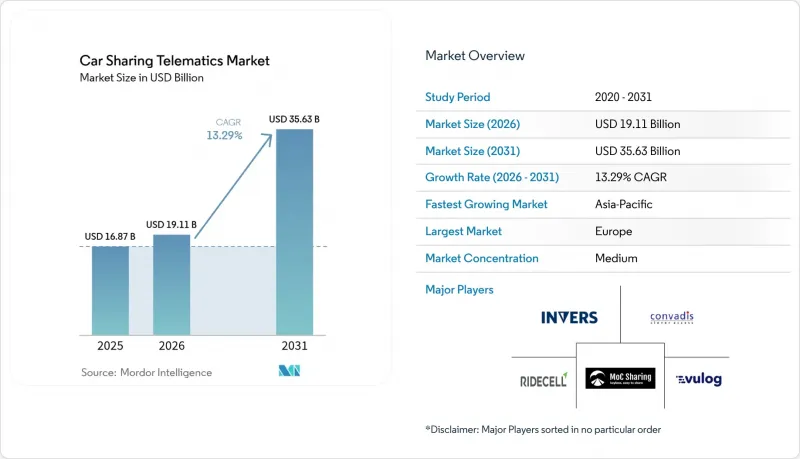
에 의하면, 2026년 카셰어링 텔레매틱스 시장 규모는 191억 1,000만 달러로 추정되고 2025년 168억 7,000만 달러에서 성장하여 2031년에는 356억 3,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 13.29%로 성장할 것으로 전망됩니다.
본 보고서는 채널별(원래 장비 제조업체(OEM), 애프터마켓), 형태별(내장형, 유선식, 통합형), 카셰어링 모델별(왕복·스테이션형, 법인·플릿, 피어 투 피어(P2P), 기타),구동 방식별(내연기관(ICE), 배터리식 전기차(BEV), 하이브리드차(HEV/PHEV)), 지역별로 분류되어 있습니다.
세계의 카셰어링 텔레매틱스 시장 동향 및 인사이트
도시 지역에서 공유 모빌리티에 대한 관심 증가
도시 과밀화가 진행되고 정체 요금 제도가 확대됨에 따라 통근의 경제성은 공유 차량으로 이동하고 있으며, 지자체 기획 담당자들은 카셰어링, 마이크로모빌리티, 대중교통을 통합한 멀티모달 모빌리티 허브를 위해 갓길 공간의 재분배를 추진하고 있습니다. 프리 플로팅 방식의 사업자는 실시간 히트맵 및 텔레메트리를 활용하여 수요가 정점에 달하는 지역으로 차량을 재배치함으로써 고객의 대기 시간을 단축하고 차량의 유휴 시간을 줄이고 있습니다. 뮌헨과 베를린에서는 이용이 집중되는 지역이 인구 밀도나 지하철 환승역과의 근접성과 일치하는 것으로 나타나, 위치 분석이 수익성의 핵심 요인임이 입증되었습니다. 기상 데이터와 이벤트 일정을 기반으로 학습된 동적 가격 책정 엔진은 차량 배분을 최적화하는 동시에 1회 승차당 배출량을 줄이고 있습니다. 이러한 도시 네트워크 효과는 교통과 환경 양쪽의 외부성을 내재화하는 카셰어링 텔레매틱스 시장 플랫폼에 대해 투자자들이 지속적으로 지원을 이어가는 이유를 여실히 보여줍니다.
차량 텔레매틱스에 관한 정부 규제(eCall, 안전성)
규제 당국은 텔레매틱스를 법적 의무로 규정함으로써 그 도입을 가속화하고 있습니다. EU의 ‘일반 안전 규정 II’에 따라 2024년 7월 이후 모든 신형 M1·N1 차량에는 지능형 속도 보조 기능, 자동 긴급 제동 장치, 사건 데이터 기록기의 탑재가 의무화됩니다. 차세대 eCall에서는 긴급 신고의 기반이 2G/3G에서 4G/5G로 전환됨에 따라, 카셰어링 차량 전체에 걸쳐 하드웨어 업데이트가 필요하게 됩니다. 러시아와 브라질에서도 유사한 체계가 도입되고 있으며, FCC 역시 동일한 규제를 검토 중입니다. 이를 통해 여러 지역에서 규정 준수를 표준화할 수 있는 공급업체에게는 규모의 경제가 실현될 것입니다. NG-eCall을 지원하도록 업그레이드된 차량은 더욱 풍부한 충돌 데이터 세트를 제공하며, 사업자는 이를 안전 운전 프로그램이나 정교해진 보험료 산정을 통해 수익화할 수 있게 되었습니다.
높은 하드웨어 및 설치 비용
반도체 공급 제약과 센서 수 증가로 인해 차량 1대당 반도체 탑재 비용은 2030년까지 1,200달러에 달하고, 2022년 수준보다 2배 증가할 것으로 예측됩니다. 이러한 추세는 NITI Aayog의 부품 비용 추적 조사에서도 뚜렷이 드러나고 있습니다. 차량의 무선 통신을 4G에서 5G로 업그레이드하면 모듈 가격은 상승하지만, 저지연 용도이 보급되기 전까지는 투자 회수 효과가 제한적입니다. 그 결과, 소규모 사업자들은 업데이트 주기를 미루거나 계약 기간에 걸쳐 자본 지출을 분산시키는 구독 모델을 모색하고 있습니다. OEM과 Tier 1 공급업체 간의 전략적 제휴(Geotab과 폭스바겐 그룹, Samsara와 스텔란티스 등)가 부상하고 있으며, 이를 통해 구매 할인 및 공동 연구개발을 실현하는 동시에, 규정 준수 업데이트를 비용이 많이 드는 서비스 캠페인이 아닌 무선(OTA)을 통해 확실하게 전달할 수 있게 하고 있습니다.
부문별 분석
2025년에는 방대한 수의 기존 차량을 배경으로, 애프터마켓에서의 사후 개조가 매출의 57.42%를 차지하며 시장을 휩쓸었습니다. 그러나 eCall과 같은 규제에 대한 출고 시 준수 및 사이버 보안 대책 강화에 힘입어 OEM 내장형 유닛은 연평균 성장률(CAGR) 14.92%로 확대되고 있습니다. 자동차 제조업체들은 현재 배터리, ADAS, 공조 시스템에 관한 상세한 데이터를 제공하는 자동차 API를 공개하고 있으며, 이를 통해 사업자들은 차량 운용 효율을 높이는 데 활용할 수 있는 더 많은 수단을 확보하고 있습니다. Geotab이 폭스바겐 그룹(Volkswagen Group)의 대시보드에 직접 연결하는 등의 제휴 사례는 하드웨어, 소프트웨어, 현장 업데이트가 가능한 펌웨어를 단일 라이프사이클 스택으로 통합하는 생태계 전략에 대한 집중을 상징합니다.
BEV의 보급이 진행됨에 따라, OEM 통합형 도입에 따른 카셰어링 텔레매틱스 시장 규모는 급격히 확대될 것으로 예측됩니다. 이는 배터리 진단을 위해서는 구동 시스템에 대한 직접적인 접근이 필요하며, 사후 장착형 동글로는 이를 확실하게 실현할 수 없기 때문입니다. 사후 장착 벤더들은 여전히 혼합 연료 차량의 차량 군이나 차량 평균 연식이 8년을 넘는 신흥 시장을 대상으로 하고 있으며, 중기적으로는 양극화된 채널 구조가 유지될 전망입니다.
반도체 가격 상승에 따라 내장형과 애프터마켓형 간의 비용 격차는 점차 줄어들고 있는 반면, 무선 프로비저닝을 통해 공장 출하 시 유닛의 설치 작업에 드는 노력이 절감되고 있습니다. 대규모 사업자들은 두 전략을 결합하여 리스크를 헤지하고 있습니다. 신규로 취득한 차량에는 내장형 텔레매틱스를 탑재하지만, 기존의 가솔린차나 하이브리드차에는 인증된 타사 장치를 도입하여 상세한 데이터 피드를 통합하고 있습니다. 이러한 하이브리드 접근 방식을 통해 기업은 단일 공급업체에 대한 의존 위험을 회피하고, 자본을 고정시키지 않으면서도 업데이트 주기를 단축할 수 있습니다. 이러한 실무 방식이 카셰어링 텔레매틱스 시장 전체의 조달 방침을 형성하고 있습니다.
2025년에는 내장형 모듈이 매출의 45.48%를 차지했으나, 4G/5G 모뎀, 엣지 AI, 보안 부트 로더를 아우르는 완전히 통합된 연결 플랫폼은 연평균 성장률(CAGR) 16.65%로 성장을 지속하고 있습니다. 이러한 유닛은 과거에는 별도의 장치가 필요했던 기능을 통합하여 배선 하네스를 줄이고 연산 처리량을 확대되고 있습니다. 통합 아키텍처는 개방형 API를 제공하여, 개발자가 동일한 텔레메트리 백본 위에 MaaS 과금 엔진, 예측 유지보수 대시보드, 탄소 발자국 계산 도구를 중첩하여 구축할 수 있게 해줍니다. 스마트폰과의 페어링에 의존하는 테더형 솔루션은 차량 운영 사업자가 잠금/잠금 해제, 이모빌라이저, 원격 비활성화 명령을 위한 상시 가동형 중복성을 우선시함에 따라 그 존재감을 잃어가고 있습니다. 대도시권에서 5G 커버리지가 확대되고, 텔레드라이빙이나 원격 발렛 서비스와 같은 지연에 민감한 용도이 가능해짐에 따라, 통합형 도입에 따른 카셰어링 텔레매틱스 시장 규모는 2027년까지 테더형 솔루션의 매출을 넘어설 것으로 예측됩니다.
엣지 측의 컨테이너화를 통해 하나의 텔레매틱스 제어 유닛 내에서 여러 가상화 용도이 안전하게 공존할 수 있게 되어, 진화하는 규격에 대응할 수 있는 미래 지향적인 차량 환경이 실현되고 있습니다. 표준화는 OEM 간 데이터 통합을 촉진하고, 멀티 브랜드 차량 운영의 간소화를 도모하며, 소프트웨어 통합에 소요되는 오버헤드를 줄여줍니다. 그 결과, 신규 진출기업과 기존 사업자 모두에서 통합형 솔루션이 RFP(제안 요청서)의 기준을 점점 더 주도하게 되면서, 카셰어링 텔레매틱스 시장에서 그 성장세가 가속화되고 있습니다.
지역별 분석
유럽은 모든 신차에 첨단 안전 및 연결 기능을 탑재하도록 의무화하는 성숙한 규제 덕분에 매출 점유율 36.62%로 선두를 유지하고 있습니다. 독일, 프랑스, 북유럽 국가 등 각국의 인센티브 제도는 전동화된 카셰어링 차량 군에 대한 보조금을 지급하고 있어, 사업자에게 BEV(배터리식 전기차) 구독 서비스가 경제적으로 매력적인 선택지가 되고 있습니다. ShareNow의 동부 지역으로의 사업 확장은 대륙 내 노하우 이전을 입증하는 것이며, 한편 르노의 위트레흐트에서 진행 중인 V2G(차량에서 전력망으로의 전력 공급) 시범 사업은 전력망과 통합된 모빌리티의 가능성을 보여주고 있습니다. 아시아태평양은 급속한 도시 인구 이동과 각국의 스마트 시티 예산에 힘입어 연평균 성장률(CAGR) 14.33%라는 가장 빠른 속도로 성장하고 있습니다. 중국 본토만 해도 50개 이상의 도시에서 로보택시 시범 운영이 진행 중이며, 각 도시마다 차량 텔레매틱스에 통합된 초저지연 연결성이 필요합니다. 이 지역에는 18억 명의 모바일 가입자가 있으며, 이는 실시간 차량fleet 조정 및 무선 업데이트(OTA)를 위한 연결 기반을 형성하고 있습니다. 동남아시아 각국 정부 역시 텔레매틱스를 활용한 차량 관리 시스템 도입을 지원하고 있어, 카셰어링 텔레매틱스 시장에 비옥한 토양을 마련하고 있습니다. 북미에서는 이러한 추세에 차이가 보입니다. 기술 지향적인 대도시권에서는 5G 기반 원격 주행 시범 사업이 도입되고 있는 반면, 교외의 무분별한 도시 확장으로 인해 차량 교체율은 낮아지고 있습니다. Verizon Business가 라스베이거스에서 Vay와 맺은 제휴는 mm파 대역폭을 활용하면서도 재배치에 드는 노력을 줄이는 원격 운전형 전기차로의 움직임을 여실히 보여주고 있습니다. 그러나 농촌 지역이나 도시 외곽에서는 여전히 LTE나 구형 3G 네트워크에 의존하고 있어, 서비스 확대의 경제성을 저해하는 요인이 되고 있습니다. 캐나다와 미국에서는 ISO/SAE 21434와 같은 연방 표준을 준수하는 사이버 보안 대책이 점점 더 중요시되고 있으며, 규정 준수 요건은 증가하고 있지만, 카셰어링 텔레매틱스 시장의 지속적인 확산에 필수적인 소비자의 신뢰를 강화하는 데에도 기여하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, car sharing telematics market size in 2026 is estimated at USD 19.11 billion, growing from 2025 value of USD 16.87 billion with 2031 projections showing USD 35.63 billion, growing at 13.29% CAGR over 2026-2031.
This report is Segmented by Channel (Original Equipment Manufacturer (OEM) and Aftermarket), Form (Embedded, Tethered, and Integrated), Car-Sharing Model (Round-Trip / Station-Based, Corporate / Fleet, Peer-To-Peer (P2P), and More), Vehicle Propulsion (Internal-Combustion Engine (ICE), Battery-Electric Vehicle (BEV), and Hybrid Electric Vehicle (HEV/PHEV)), and Geography.
Global Car Sharing Telematics Market Trends and Insights
Growing Urban Preference for Shared Mobility
Continued densification and escalating congestion-charging schemes are shifting commuter economics toward shared fleets, nudging municipal planners to re-allocate curb space for multimodal mobility hubs that integrate car sharing, micro-mobility, and public transit. Free-floating operators use real-time heat-map telemetry to reposition vehicles in zones of peak demand, cutting customer wait times and trimming fleet idle minutes. In Munich and Berlin, usage clusters align with demographic density and proximity to subway interchanges, confirming location analytics as a core profitability lever. Dynamic-pricing engines, trained on weather feeds and event calendars, optimize vehicle distribution while lowering per-ride emissions footprints. Such urban network effects underscore why investors continue to back car sharing telematics market platforms that internalize both transportation and environmental externalities.
Government Mandates for Vehicle Telematics (eCall, Safety)
Regulators are accelerating adoption by making telematics a legal obligation. Under the EU General Safety Regulation II, all new M1 and N1 vehicles must feature intelligent speed assistance, automatic emergency-braking, and event-data recorders from July 2024. Next-Generation eCall shifts the emergency-alert backbone from 2G/3G to 4G/5G, demanding hardware refreshes across car-sharing fleets.Comparable frameworks are rolling out in Russia and Brazil, and the FCC is reviewing a similar mandate, giving scale economies to vendors able to standardize multi-region compliance. Vehicles upgraded for NG-eCall deliver richer crash datasets that operators now monetize through safer-driving programs and refined insurance pricing.
High Hardware and Installation Costs
Silicon supply constraints and escalating sensor counts are pushing semiconductor content per vehicle toward USD 1,200 by 2030, doubling 2022 levels, a trend highlighted by NITI Aayog's component-cost tracking. Upgrading fleets from 4G to 5G radios elevates module prices yet delivers minimal payback until low-latency apps reach scale. Consequently, smaller operators defer refresh cycles or seek subscription models that spread capital outlay across contractual terms. Strategic OEM-tier-one alliances-Geotab with Volkswagen Group, Samsara with Stellantis-are emerging to unlock purchase discounts and shared R&D while ensuring compliance updates flow over-the-air rather than via costly service campaigns.
Other drivers and restraints analyzed in the detailed report include:
- Integration of IoT/AI/ML for Fleet Optimization
- Rapid Electrification of Car-Sharing Fleets
- Data-Privacy and Cyber-Security Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, aftermarket retrofits dominated with 57.42% revenue, reflecting the sizeable legacy vehicle pool. Yet OEM-embedded units are advancing at 14.92% CAGR, helped by factory-level compliance with eCall-style mandates and tighter cybersecurity hardening. Automakers now expose on-board APIs that furnish granular battery, ADAS, and climate data, giving operators more levers to drive up fleet utilization. Partnerships such as Geotab's direct pipeline into Volkswagen Group dashboards exemplify the gravitation toward ecosystem plays that marry hardware, software, and field-updatable firmware in a single lifecycle stack.
The car sharing telematics market size for OEM-integrated deployments is projected to climb sharply as BEV adoption widens, because battery diagnostics demand direct traction-system access that retrofit dongles cannot match reliably. Nonetheless, retrofit vendors still serve mixed-fuel fleets and emerging markets where vehicle ages average above eight years, keeping a two-speed channel landscape intact through the mid-term.
Cost parity between embedded and aftermarket is narrowing as silicon prices climb, while over-the-air provisioning reduces fit-out labor for factory units. Larger operators hedge by blending both strategies: new acquisitions arrive with embedded telematics, but veteran gasoline or hybrid units receive certified third-party devices to unify granular data feeds. This hybrid posture insulates businesses from single-vendor risk and shortens refresh cycles without stranding capital-practices that shape procurement playbooks across the broader car sharing telematics market.
Embedded modules accounted for 45.48% revenue in 2025, but fully integrated connectivity platforms-encompassing 4G/5G modems, edge AI, and secure bootloaders-exhibit a 16.65% CAGR. These units aggregate functions that once required discrete devices, trimming wiring harnesses while expanding compute throughput. Integrated architectures expose open APIs, enabling developers to layer MaaS billing engines, predictive-maintenance dashboards, and carbon-footprint calculators atop the same telemetry backbone.Tethered solutions that depend on smartphone pairing are receding as fleet operators prioritize always-on redundancy for lock/unlock, immobilizer, and remote-disabling commands. The car sharing telematics market size attached to integrated-form deployments is forecast to outstrip tethered revenues by 2027 as 5G coverage proliferates across metropolitan corridors, permitting latency-sensitive applications such as tele-driving and remote-valet services.
Edge-side containerization now allows multiple virtualized applications to coexist securely within one telematics control unit, future-proofing fleets against evolving standards. Standardization drives cross-OEM data fusion, simplifying multi-brand fleet operations and trimming software-integration overhead. As a result, integrated solutions increasingly underpin RFP criteria among both new entrants and incumbent operators, accelerating their momentum within the car sharing telematics market.
Complete Report Scope:
- By Channel
- Original Equipment Manufacturer (OEM)
- Aftermarket
- By Form
- Embedded
- Tethered
- Integrated
- By Car-Sharing Model
- Round-trip / Station-based
- Free-floating (One-way)
- Peer-to-Peer (P2P)
- Corporate / Fleet
- By Vehicle Propulsion
- Internal-Combustion Engine (ICE)
- Battery-Electric Vehicle (BEV)
- Hybrid Electric Vehicle (HEV/PHEV)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- UAE
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
Europe retains 36.62% revenue leadership owing to mature regulations that mandate advanced safety and connectivity suites on all new vehicles. National incentive schemes bordering Germany, France, and the Nordics subsidize electrified car-sharing fleets, making BEV subscriptions financially compelling for operators. ShareNow's expansion eastward demonstrates intra-continental knowledge transfer, while Renault's Utrecht V2G pilot showcases grid-integrated mobility potential. Asia Pacific is scaling fastest at 14.33% CAGR, underwritten by rapid urban migration and sovereign smart-city budgets. Mainland China alone fields robotaxi pilots across more than 50 municipalities, each requiring ultra-low-latency connectivity baked into fleet telematics. The region counts 1.8 billion mobile subscribers, a connectivity bedrock for real-time fleet orchestration and over-the-air updates. Southeast Asian governments are likewise subsidizing telematics-based fleet-management rollouts, cultivating a fertile runway for the car sharing telematics market. North America exhibits mixed momentum: tech-centric metros adopt 5G-enabled tele-driving pilots, whereas suburban sprawl depresses vehicle-turnover metrics. Verizon Business' Las Vegas partnership with Vay highlights the push toward remote-driven e-vehicles that cut repositioning labor while leveraging mmWave bandwidth. Rural and ex-urban districts, however, remain tethered to LTE or legacy 3G networks, tempering service-expansion economics. Canada and the United States increasingly prioritize cybersecurity alignment with federal standards such as ISO/SAE 21434, adding an additional compliance layer yet reinforcing consumer trust-crucial for sustained car sharing telematics market penetration.
- INVERS GmbH
- Vulog
- Ridecell Inc.
- Convadis AG
- Continental Aftermarket and Services
- OCTO Group S.p.A
- Geotab Inc.
- Targa Telematics
- Fleetster
- OpenFleet
- Mobility Tech Green
- WeGo B.V.
- MoC Sharing
- Free2Move
- Miles Mobility
- Share Now
- Sixt share
- Getaround
- Zity
- Bolt Drive
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing urban preference for shared mobility
- 4.2.2 Government mandates for vehicle telematics (eCall, safety)
- 4.2.3 Integration of IoT/AI/ML for fleet optimisation
- 4.2.4 Rapid electrification of car-sharing fleets
- 4.2.5 Usage-based-insurance partnerships lowering OPEX
- 4.2.6 API-first telematics platforms enabling MaaS aggregation
- 4.3 Market Restraints
- 4.3.1 High hardware and installation costs
- 4.3.2 Data-privacy and cyber-security concerns
- 4.3.3 Lack of telematics interoperability standards
- 4.3.4 Low utilisation rates in suburban and rural zones
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Investment and Funding Trends
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Channel
- 5.1.1 Original Equipment Manufacturer (OEM)
- 5.1.2 Aftermarket
- 5.2 By Form
- 5.2.1 Embedded
- 5.2.2 Tethered
- 5.2.3 Integrated
- 5.3 By Car-Sharing Model
- 5.3.1 Round-trip / Station-based
- 5.3.2 Free-floating (One-way)
- 5.3.3 Peer-to-Peer (P2P)
- 5.3.4 Corporate / Fleet
- 5.4 By Vehicle Propulsion
- 5.4.1 Internal-Combustion Engine (ICE)
- 5.4.2 Battery-Electric Vehicle (BEV)
- 5.4.3 Hybrid Electric Vehicle (HEV/PHEV)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 ASEAN
- 5.5.4.6 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 UAE
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 INVERS GmbH
- 6.4.2 Vulog
- 6.4.3 Ridecell Inc.
- 6.4.4 Convadis AG
- 6.4.5 Continental Aftermarket and Services
- 6.4.6 OCTO Group S.p.A
- 6.4.7 Geotab Inc.
- 6.4.8 Targa Telematics
- 6.4.9 Fleetster
- 6.4.10 OpenFleet
- 6.4.11 Mobility Tech Green
- 6.4.12 WeGo B.V.
- 6.4.13 MoC Sharing
- 6.4.14 Free2Move
- 6.4.15 Miles Mobility
- 6.4.16 Share Now
- 6.4.17 Sixt share
- 6.4.18 Getaround
- 6.4.19 Zity
- 6.4.20 Bolt Drive
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment