

|
시장보고서
상품코드
2124948
Wi-Fi 칩셋 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Wi-Fi Chipset - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
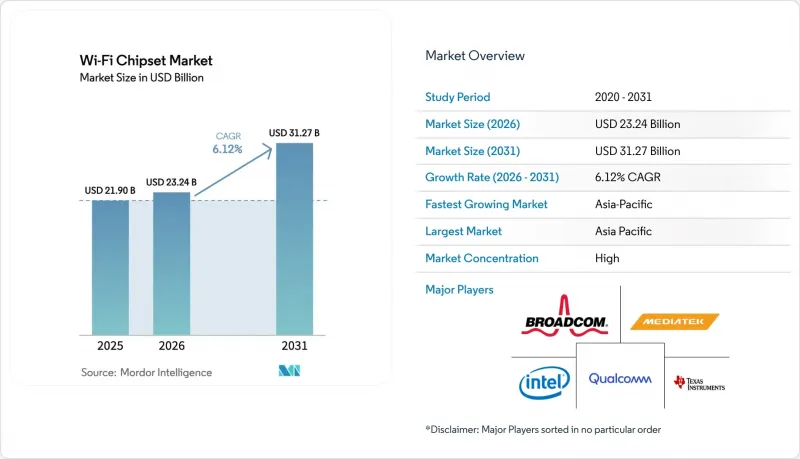
에 의하면, Wi-Fi 칩셋 시장 규모는 2025년 219억 달러로 평가되었습니다. 2026년에는 232억 4,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 6.12%로 성장을 지속하여, 2031년에는 312억 7,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 규격(Wi-Fi 4, Wi-Fi 5, Wi-Fi 6 및 6E, 기타), MIMO 구성(MU-MIMO, SU-MIMO), 기기 용도(스마트폰, 태블릿, 데스크톱, 노트북,Wi-Fi 라우터 및 광대역 게이트웨이, 기타), 최종 사용자(가정, 기업, 산업, 자동차, 기타), 지역(북미, 남미, 기타)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 Wi-Fi 칩셋 시장 동향 및 인사이트
기업 네트워크에서의 Wi-Fi 6/6E의 급속한 보급
FCC(연방통신위원회)가 개방한 6GHz 대역의 1,200MHz 주파수 대역을 발판으로, 2024년에는 기업 캠퍼스의 업그레이드가 시범 단계에서 본격적인 전개로 전환되기 시작했습니다. 채널 추가로 320MHz라는 더 넓은 대역폭이 가능해졌으며, Wi-Fi 5에 비해 처리량이 5배 향상되었습니다. 이를 통해 IT 팀은 8K 미디어 스트림이나 지연에 민감한 협업 도구를 운영하기 위한 여유 용량을 확보할 수 있게 되었습니다. 2024년까지 400종 이상의 Wi-Fi 6E 인증 기기가 시판되었으며, 엔터프라이즈급 액세스 포인트는 인증 하위 카테고리 중 가장 빠른 성장세를 보였습니다. 2.4GHz 및 5GHz 대역에서 작동하는 레거시 기기로 인한 간섭을 6GHz 대역의 깨끗한 채널이 피할 수 있기 때문에 시설 관리 팀에서는 문제 해결 요청 건수가 감소했다고 보고하고 있습니다. 각 벤더들은 Wi-Fi 6E 하드웨어를 주파수 대역이 사용 가능해졌을 때 Wi-Fi 7로 소프트웨어 업그레이드가 가능한, 미래를 내다본 투자로 자리매김하고 있습니다. 의료 및 금융과 같은 산업에서는 상시 연결된 무선 환경이 업무상 필수 요건이 되었기 때문에 조달 주기가 15개월 미만으로 단축되었습니다.
스마트 홈 기기와 주거용 메시 네트워크의 성장
2024년에는 많은 도시 지역 주택에서 가정 내 기기 밀도가 30대 이상의 연결 단말기를 넘어섰으며, 2028년까지 평균 50대를 초과할 것으로 예측됩니다. 이러한 급증으로 인해 서비스 제공업체는 메시 노드 간 6GHz 백홀 링크를 전용으로 사용할 수 있는 트라이 라디오 칩셋을 기반으로 한 게이트웨이를 재설계해야만 합니다. 이를 통해 Wi-Fi 6E 게이트웨이는 여전히 2.4GHz에서 작동하는 온도 조절기나 보안 카메라의 대역폭이 4K 스트리밍 박스에 의해 압박받는 것을 방지합니다. 새로운 칩셋에 통합된 빔 포밍 및 원활한 핸드오프 기능 덕분에 거주자가 방을 이동하더라도 일관된 처리량이 유지되어, 고객 지원 문의의 주요 원인 중 하나가 해소됩니다. 성숙한 절전 모드를 통해 작동 빈도가 낮은 센서의 배터리 수명이 연장되어 인터넷 서비스 제공업체의 현장 대응 비용이 절감됩니다. Broadcom은 북미의 일부 광섬유 서비스 지역에서 6GHz 지원 게이트웨이를 도입한 후 현장 지원 사고가 두 자릿수 감소했다고 보고했습니다.
네트워크 보안 위협과 복잡한 관리
WPA3로의 전환으로 Wi-Fi 네트워크 보안은 강화되지만, 서로 다른 세대의 기기가 혼재된 환경에서는 호환성 문제가 발생하여 기업의 업그레이드를 지연시키고 있습니다. Wi-Fi 7의 멀티링크 운영에서는 각 주파수 링크마다 동기화된 암호화 인증 정보가 필요하기 때문에 보안 정책 세트의 수가 증가합니다. 그 결과, IT 관리자는 자동화된 정책 엔진에 투자하게 되지만, 이로 인해 비용이 증가하고 도입 일정이 장기화되고 있습니다. 관리 대상 외 IoT 기기의 유입으로 인해 공격 표면이 확대되면서, 더욱 엄격한 네트워크 세분화 및 제로 트러스트 아키텍처의 도입이 요구되고 있지만, 이는 제한된 인력 자원에 부담을 주고 있습니다. 실외에서 6GHz 채널을 운영하기 위해 필요한 자동 주파수 조정 데이터베이스는 변경 관리 워크플로우를 더욱 복잡하게 만들어, 일부 조직에서는 벤더의 도구가 성숙해질 때까지 도입을 미루는 사태를 초래하고 있습니다.
부문별 분석
Wi-Fi 6과 Wi-Fi 6E는 기업 캠퍼스 현대화 프로젝트의 주요 업그레이드 경로로서, 2025년에는 합계 41.27%의 매출 점유율을 차지했습니다. 이 부문은 하위 호환성과 인증된 클라이언트 생태계의 혜택을 받고 있으며, 중기적인 관점에서 Wi-Fi 칩셋 시장을 지탱하는 기반이 되고 있습니다. Wi-Fi 7 설계가 주류를 차지하는 ‘기타’ 부문은 칩 제조업체들이 스펙트럼 효율을 획기적으로 높이는 320MHz 채널 아키텍처의 최종 조정을 진행함에 따라 6.72%라는 가장 높은 연평균 성장률(CAGR)을 나타낼 전망입니다. 애플의 플래그십 스마트폰과 노트북 플랫폼에는 2025년에 트라이밴드 Wi-Fi 7 무선 기능이 탑재되었으며, 이에 따라 기업들은 일반적으로 기기와 액세스 포인트의 기능을 일치시키기 위해 LAN 인프라에 대한 투자를 가속화할 것입니다. Filogic 기반 Wi-Fi 7 게이트웨이는 통신 사업자의 실험실 테스트에서 업링크 처리량이 4배 더 높다는 것이 입증되어, Wi-Fi 6E의 이전 세대 제품과의 차별성이 두드러집니다.
가상현실, 클라우드 게임, 초고화질 스트리밍에 대한 수요가 증가함에 따라 처리량에 대한 기대치는 Wi-Fi 6E의 상한선을 넘어 높아지고 있습니다. 얼리 어답터들은 실외 시설에서 6GHz 대역의 기존 주파수 보호 요건을 충족하기 위해 자동 주파수 조정(AFC) 기능을 갖춘 액세스 포인트를 전략적으로 발주하고 있습니다. 칩셋 벤더들 시장 홍보 캠페인에서는 양방향 XR 이용 사례에 필수적인 1밀리초 대의 지연 시간 단축이 강조되고 있습니다. Wi-Fi 칩셋 시장이 변혁기를 맞이하는 가운데, 모듈형 레퍼런스 설계를 제공하는 부품 공급업체들은 고객 시장 출시 기간을 단축하고, CPE, PC, 스마트폰 등 각 부문에서 설계 채택을 확실히 확보하고 있습니다.
MU-MIMO 솔루션은 2025년 매출의 60.65%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 6.61%를 기록했습니다. 8스트림을 지원하는 액세스 포인트는 수십 대의 기기에 대해 동시 다운링크 및 업링크 데이터를 전송합니다. 이 기능은 동시 접속 사용자 수가 500명을 넘는 경우가 잦은 강당이나 교통 허브에서 필수적입니다. Wi-Fi 6E 및 Wi-Fi 7의 PHY 계층에 통합된 빔포밍 알고리즘의 발전으로 인해 반사가 많은 실내 환경에서도 신호의 무결성이 유지됩니다. MU-MIMO 구현과 관련된 Wi-Fi 칩셋 시장 규모는 하이엔드 엔터프라이즈용 장비의 높은 평균 판매 가격(ASP)의 혜택을 받고 있습니다.
SU-MIMO 칩셋은 싱글 스레드 통신으로 충분한 엔트리 레벨 게이트웨이나 가격에 민감한 IoT 노드에 계속해서 채택되고 있습니다. 그러나 IoT 밀도가 높아짐에 따라 에어타임 경쟁을 최소화하기 위해 소비자용 액세스 포인트조차 4스트림 MU-MIMO 설계로 전환되고 있습니다. 벤더들은 클라이언트의 텔레메트리 데이터를 분석하여 공간 스트림을 동적으로 할당하는 AI 가속화 블록을 통합함으로써, 가정용 업링크 트래픽을 주도하는 화상 회의 앱에서 예측 가능한 용도 성능을 보장하고 있습니다.
지역별 분석
2025년, 아시아태평양이 Wi-Fi 칩셋 시장 출하량의 43.05%를 차지했으며, 중국, 일본, 한국이 제조와 소비 양쪽을 모두 뒷받침했습니다. 중국의 2, 3선 도시에서 정부의 광섬유 투자가 트라이라디오 게이트웨이 수요를 자극하고 있지만, 실내 6GHz 대역 운영에 관한 현행 규제로 인해 Wi-Fi 6E의 본격적인 보급은 지연되고 있습니다. 2024년 일본에서 6GHz 대역 WLAN이 규제상 승인됨에 따라, 320MHz 채널을 지원하는 Wi-Fi 7 라우터를 둘러싼 국내 OEM 업체들의 움직임이 활발해지고 있습니다. 한편, 한국의 통신 사업자들은 5G 지원 스마트 시티 회랑 내에 캐리어급 Wi-Fi 6E 액세스 포인트를 도입하고 있습니다. 인도의 인터넷 가입자 급증과 첸나이에 Wi-Fi 설계 센터 설립은 해당 지역이 엔지니어링 거점인 동시에 대규모 소비자 시장으로서도 그 역할을 확대하고 있음을 보여줍니다.
북미는 FCC에 의한 6GHz 대역 전체의 조기 개방을 활용하여 기업용 도입에서 주도적인 역할을 유지하고 있습니다. 하이브리드 근무 방식의 보급으로 인해 동적 채널 할당 기능을 갖춘 액세스 포인트에 대한 수요는 계속해서 견조합니다. 서비스 제공업체들은 고객 이탈을 방지하고 통신 속도 계층화를 넘어선 차별화를 꾀하기 위해, 기가비트 광회선 패키지에 매니지드 Wi-Fi 7 게이트웨이를 번들로 제공합니다. Wi-Fi 칩셋 시장은 총 소유 비용(TCO) 모델이 생산성 향상을 정당화하는 경우, 세대 교체를 신속하게 뒷받침하는 민간 부문의 견실한 자금 지원의 혜택을 받고 있습니다. 유럽에서는 8Gbps 멀티기가 서비스를 준비하는 광대역 사업자들 사이에서 Wi-Fi 7 도입이 가속화되고 있습니다. CEPT가 6GHz 대역 상단의 인가를 위해 기울인 노력은 사용 가능한 채널 수를 2배로 늘리고, 인구 밀집 대도시권 전체에서 대칭형 기가비트 성능을 실현하는 결과로 이어질 것입니다. 한편, 남미, 중동 및 아프리카에서는 비용이 절감된 Wi-Fi 6 칩셋이 대중용 스마트폰과 지방의 연결 격차를 해소하는 고정 무선 게이트웨이에 채택됨에 따라 신흥 시장으로서의 성장이 기대되고 있습니다. 이러한 지역에서의 주파수 할당 다양성은 전 세계 SKU의 통합을 복잡하게 만들고 있지만, 표준 규격에 따른 인증을 통해 다국적 OEM의 상호 운용성과 관련된 위험은 최소화되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the wi-Fi chipset market size is expected to grow from USD 21.90 billion in 2025 to USD 23.24 billion in 2026 and is forecast to reach USD 31.27 billion by 2031 at 6.12% CAGR over 2026-2031.
This report is Segmented by Standard (Wi-Fi 4, Wi-Fi 5, Wi-Fi 6 and 6E, and More), MIMO Configuration (MU-MIMO, SU-MIMO), Device Application (Smartphones, Tablets, Desktops, Laptops, Wi-Fi Router and Broadband Gateway, and More), End-User (Residential, Enterprise, Industrial, Automotive, and More), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Wi-Fi Chipset Market Trends and Insights
Rapid Adoption of Wi-Fi 6/6E in Enterprise Networks
Corporate campus upgrades began moving from pilot to full-scale rollouts in 2024, pushed by the 1,200 MHz of 6 GHz spectrum released by the FCC. Added channels permit larger 320 MHz widths that quintuple throughput versus Wi-Fi 5, giving IT teams capacity headroom for 8K media streams and latency-sensitive collaboration tools. More than 400 Wi-Fi 6E-certified devices had reached commercial availability by 2024, and enterprise-class access points formed the fastest-growing certification subcategory. Facilities teams report lower troubleshooting tickets as clean 6 GHz channels avoid interference created by legacy devices operating at 2.4 GHz and 5 GHz. Vendors position Wi-Fi 6E hardware as future-proof investments that accept software upgrades to Wi-Fi 7 when spectrum becomes available. Procurement cycles are shortened to under 15 months in verticals such as healthcare and finance, where always-on wireless is now an operational prerequisite.
Growth in Smart-Home Devices and Residential Mesh Networking
Household device density surpassed 30 connected endpoints in many urban dwellings during 2024, and forecasts suggest averages above 50 by 2028. That surge forces service providers to redesign gateways around tri-radio chipsets capable of dedicating 6 GHz backhaul links between mesh nodes. Wi-Fi 6E gateways thus prevent 4K streaming boxes from crowding thermostats and security cameras that still operate on 2.4 GHz. Beamforming and seamless handoff software within new chipsets sustain consistent throughput as occupants roam from room to room, addressing a top driver of support calls. Mature power-save modes extend battery life for low-duty-cycle sensors, trimming truck-roll costs for internet service providers. Broadcom quantified a double-digit drop in field-support incidents after deploying 6 GHz-enabled gateways across select North American fiber footprints.
Network Security Threats and Complex Management
Transitioning to WPA3 hardens Wi-Fi networks, yet mixed-generation device fleets create compatibility gaps that slow enterprise upgrades. Multi-Link Operation in Wi-Fi 7 multiplies policy sets because each frequency link demands synchronized encryption credentials. IT administrators, therefore, invest in automated policy engines that escalate costs and lengthen deployment timetables. The influx of unmanaged IoT devices widens attack surfaces, prompting stricter network segmentation and zero-trust architectures that strain limited staff resources. Automated Frequency Coordination databases required for outdoor 6 GHz channels further complicate change-management workflows, pushing some organizations to slow rollouts until vendor tooling matures.
Other drivers and restraints analyzed in the detailed report include:
- Integration of Wi-Fi HaLow for Low-Power Industrial IoT
- Regulatory Opening of 6-7 GHz Spectrum Accelerating Wi-Fi 7
- Semiconductor Fabrication Capacity Constraints (< 6 nm)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Wi-Fi 6 and Wi-Fi 6E together commanded 41.27% revenue share in 2025 as the preferred upgrade path for enterprise campus refresh projects. The segment benefits from backward compatibility and certified client ecosystems, anchoring the Wi-Fi chipset market through the mid-term horizon. The Others category, dominated by Wi-Fi 7 designs, is set to record the fastest 6.72% CAGR as chipmakers finalize 320 MHz channel architectures that multiply spectral efficiency. Apple's flagship smartphones and laptop platforms are scheduled to integrate tri-band Wi-Fi 7 radios in 2025, which typically triggers accelerated LAN infrastructure investment by corporations aligning device and access-point capabilities. Filogic-based Wi-Fi 7 gateways demonstrated 4X higher uplink throughput in operator lab tests, underscoring differentiation over Wi-Fi 6E predecessors.
Growing demand for virtual reality, cloud gaming, and ultra-high-definition streaming elevates throughput expectations beyond the ceiling of Wi-Fi 6E. Early adopters place strategic orders for access points that feature Automatic Frequency Coordination clients to satisfy 6 GHz incumbent protections in outdoor venues. Market education campaigns from chipset vendors emphasize latency reduction in the single-millisecond range, critical for bidirectional XR use cases. As the Wi-Fi chipset market transitions, component suppliers that offer modular reference designs accelerate customer time-to-market and lock in design wins across CPE, PC, and smartphone verticals.
MU-MIMO solutions generated 60.65% of 2025 sales and registered a 6.61% CAGR through 2031. Eight-stream access points push simultaneous downlink and uplink data to dozens of devices, a capability vital for lecture halls and transportation hubs that often peak above 500 concurrent users. Advances in beamforming algorithms embedded inside Wi-Fi 6E and Wi-Fi 7 PHY layers sustain signal integrity even in reflective indoor environments. The Wi-Fi chipset market size attached to MU-MIMO implementations benefits from premium ASPs for high-end enterprise gear.
SU-MIMO chipsets remain in entry-level gateways and price-sensitive IoT nodes where single-threaded communication remains sufficient. Yet as IoT density rises, even consumer access points are migrating to four-stream MU-MIMO designs to minimize airtime contention. Component vendors embed AI acceleration blocks that analyze client telemetry and dynamically allocate spatial streams, assuring predictable application performance for videoconferencing apps that dominate residential upstream traffic.
Complete Report Scope:
- By Standard
- Wi-Fi 4
- Wi-Fi 5 (802.11ac)
- Wi-Fi 6 and 6E (802.11ax)
- Wi-Fi 7 (802.11be)
- Other Standards (Wi-Fi 8, Older)
- By MIMO Configuration
- MU-MIMO
- SU-MIMO
- By Device Application
- Smartphones
- Tablets
- Desktops
- Laptops
- Wi-Fi Router and Broadband Gateway
- TV
- IoTs
- Infotainment Systems (Automotive)
- Other Device Applications (Drones, Gaming Devices)
- By End-User
- Residential (Consumer Electronics)
- Enterprise (Networking)
- Industrial
- Automotive
- Government and Public
- Medical
- Other End-Users (Education, Commercial)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- South-East Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific generated 43.05% of Wi-Fi chipset market shipments in 2025, with China, Japan, and South Korea anchoring both manufacturing and consumption. Government fiber investments across Tier-2 and Tier-3 Chinese cities stimulate demand for tri-radio gateways, although current limitations on indoor 6 GHz operation delay full-scale Wi-Fi 6E adoption. Japan's regulatory green light for 6 GHz WLAN in 2024 sparked local OEM activity around Wi-Fi 7 routers that support 320 MHz channels, while Korean operators deploy carrier-grade Wi-Fi 6E access points inside 5G-enabled smart-city corridors. India's surge in internet subscribers and the establishment of a Wi-Fi design center in Chennai illustrate the region's evolving role as both an engineering hub and a high-volume consumer.
North America maintains a leadership role in enterprise deployments, leveraging the FCC's early opening of the entire 6 GHz band. Hybrid work patterns keep demand strong for access points with dynamic channel allocation features. Service providers bundle managed Wi-Fi 7 gateways into gigabit fiber packages to reduce customer churn and differentiate beyond speed tiers. The Wi-Fi chipset market benefits from robust private-sector funding that underwrites rapid generation transitions when total cost-of-ownership models justify productivity gains. Europe experiences accelerated Wi-Fi 7 adoption among broadband operators preparing for 8 Gbps multi-gig services. CEPT's efforts to authorize the upper 6 GHz band would double available channels and foster symmetrical gigabit performance across densely populated metro areas. Meanwhile, South America and the Middle East, and Africa deliver emerging-market growth as cost-reduced Wi-Fi 6 chipsets migrate into mass-market smartphones and fixed-wireless gateways that bridge rural connectivity gaps. Spectrum allocation diversity across these regions complicates global SKU alignment, but standards-based certifications minimize interoperability risk for multinational OEMs.
- Qualcomm Technologies Inc.
- Broadcom Inc.
- MediaTek Inc.
- Intel Corporation
- Texas Instruments Incorporated
- STMicroelectronics N.V.
- Samsung Electronics Co., Ltd.
- NXP Semiconductors N.V.
- ON Semiconductor Corporation
- Espressif Systems
- Beken Corporation
- Infineon Technologies AG
- Renesas Electronics Corporation
- Nordic Semiconductor ASA
- Silicon Laboratories Inc.
- MaxLinear, Inc.
- UNISOC (Shanghai) Technologies Co., Ltd.
- Realtek Semiconductor Corporation
- Skyworks Solutions Inc.
- Qorvo Inc.
- Analog Devices Inc.
- Murata Manufacturing Co., Ltd.
- Marvell Technology, Inc.
- ASR Microelectronics Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of public Wi-Fi hotspots and IoT connections
- 4.2.2 Rising internet penetration and demand for high-speed connectivity
- 4.2.3 Rapid adoption of Wi-Fi 6/6E in enterprise networks
- 4.2.4 Growth in smart-home devices and residential mesh networking
- 4.2.5 Integration of Wi-Fi HaLow for low-power industrial IoT
- 4.2.6 Regulatory opening of 6-7 GHz spectrum accelerating Wi-Fi 7
- 4.3 Market Restraints
- 4.3.1 Network security threats and complex management
- 4.3.2 Competition from cellular 5G/LPWAN alternatives in IoT
- 4.3.3 Semiconductor fabrication capacity constraints (<6 nm)
- 4.3.4 Fragmented regional spectrum regulations for Wi-Fi 7
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Evolution of Wi-Fi
- 4.6 Industry Supply Chain Analysis
- 4.7 Regulatory Landscape
- 4.8 Technological Outlook
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Bargaining Power of Suppliers
- 4.9.2 Bargaining Power of Consumers
- 4.9.3 Threat of New Entrants
- 4.9.4 Intensity of Competitive Rivalry
- 4.9.5 Threat of Substitute Products
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Standard
- 5.1.1 Wi-Fi 4
- 5.1.2 Wi-Fi 5 (802.11ac)
- 5.1.3 Wi-Fi 6 and 6E (802.11ax)
- 5.1.4 Wi-Fi 7 (802.11be)
- 5.1.5 Other Standards (Wi-Fi 8, Older)
- 5.2 By MIMO Configuration
- 5.2.1 MU-MIMO
- 5.2.2 SU-MIMO
- 5.3 By Device Application
- 5.3.1 Smartphones
- 5.3.2 Tablets
- 5.3.3 Desktops
- 5.3.4 Laptops
- 5.3.5 Wi-Fi Router and Broadband Gateway
- 5.3.6 TV
- 5.3.7 IoTs
- 5.3.8 Infotainment Systems (Automotive)
- 5.3.9 Other Device Applications (Drones, Gaming Devices)
- 5.4 By End-User
- 5.4.1 Residential (Consumer Electronics)
- 5.4.2 Enterprise (Networking)
- 5.4.3 Industrial
- 5.4.4 Automotive
- 5.4.5 Government and Public
- 5.4.6 Medical
- 5.4.7 Other End-Users (Education, Commercial)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Russia
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 South-East Asia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Qualcomm Technologies Inc.
- 6.4.2 Broadcom Inc.
- 6.4.3 MediaTek Inc.
- 6.4.4 Intel Corporation
- 6.4.5 Texas Instruments Incorporated
- 6.4.6 STMicroelectronics N.V.
- 6.4.7 Samsung Electronics Co., Ltd.
- 6.4.8 NXP Semiconductors N.V.
- 6.4.9 ON Semiconductor Corporation
- 6.4.10 Espressif Systems
- 6.4.11 Beken Corporation
- 6.4.12 Infineon Technologies AG
- 6.4.13 Renesas Electronics Corporation
- 6.4.14 Nordic Semiconductor ASA
- 6.4.15 Silicon Laboratories Inc.
- 6.4.16 MaxLinear, Inc.
- 6.4.17 UNISOC (Shanghai) Technologies Co., Ltd.
- 6.4.18 Realtek Semiconductor Corporation
- 6.4.19 Skyworks Solutions Inc.
- 6.4.20 Qorvo Inc.
- 6.4.21 Analog Devices Inc.
- 6.4.22 Murata Manufacturing Co., Ltd.
- 6.4.23 Marvell Technology, Inc.
- 6.4.24 ASR Microelectronics Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


