|
시장보고서
상품코드
2125307
계량 펌프 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Metering Pumps - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
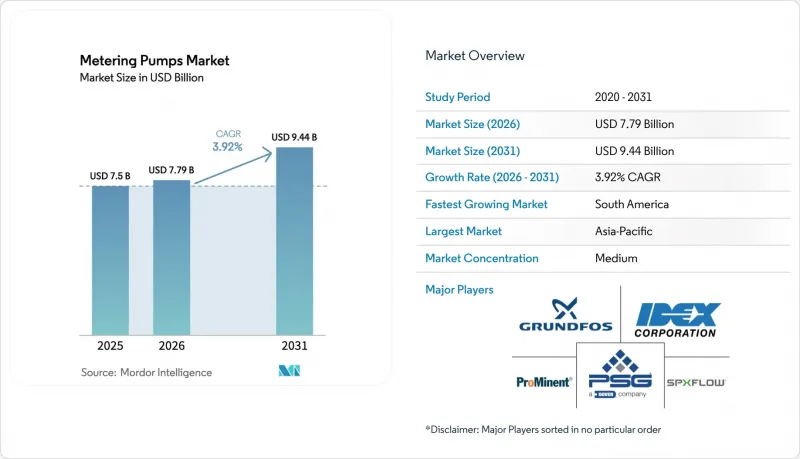
에 의하면, 계량 펌프 시장 규모는 2025년에 75억 달러로 평가되었습니다. 2026년 77억 9,000만 달러에서 2031년까지 94억 4,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 3.92%를 나타낼 전망입니다.
본 보고서는 유형별(다이어프램식, 기어식, 로터리 로브식 등), 구동 방식별(모터 구동식, 솔레노이드 구동식 등),토출 압력별(50바 이하, 51-100바 등), 최종 사용자별(수처리, 석유 및 가스, 화학 처리, 제약 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 계량 펌프 시장 동향 및 인사이트
아시아의 엄격한 산업 폐수 규제가 화학 약품 주입을 가속화
2024년에 시행된 중국의 ‘수질 오염 방지 및 관리법’의 대대적인 개정에 따라 허용되는 배수 부하량이 40% 감축되었으며, 약 6만 5,000개의 공장이 여러 개의 약품 주입 지점 설치와 디지털 데이터 기록 도입을 강요받았습니다. 전기도금, 섬유, 제약 산업의 각 거점에서의 설비 갱신은 현재 아시아 내 전체 신규 도입의 35%를 차지했으며, 기록 보관 의무를 충족하기 위해 IIoT 지원 펌프가 선호되고 있습니다(mee.gov.cn). 이러한 기준은 향후 3년 내에 동남아시아와 인도로도 확산될 것으로 예상되며, 계량 펌프 시장의 꾸준한 수요 성장을 뒷받침할 것으로 전망됩니다.
수도 유틸리티의 급속한 디지털화가 요구하는 스마트한 투여 정확도
SCADA·IoT 플랫폼을 통합한 상수도 유틸리티자는 펌프가 투여량을 실시간으로 조정함으로써 화학약품 사용량을 15-22% 절감할 수 있음을 밝혔습니다. 이러한 변화로 인해 교체 주기가 12년에서 8년 가까이 단축되었으며, 평균 판매 가격은 4분의 1 상승했습니다. 미국 남서부나 스페인 일부 등 물 부족에 직면한 지역에서는 수질 확보와 약제 비용 관리를 동시에 도모하기 위해 조기에 도입이 진행되고 있습니다. 예측 유지보수를 중심으로 한 서비스형 수익 모델이 등장하면서, 공급업체에게 비즈니스 기회가 확대되고 있습니다.
빈번한 유지보수의 필요성
기계식 다이어프램 펌프는 4,000-6,000시간 가동 후 정비가 필요한 경우가 많으며, 연속 공정이 중단됨에 따라 가동 중단 시간 동안 시간당 5,000-1만 5,000달러의 손실이 발생할 가능성이 있습니다. 신흥 시장에서는 숙련된 기술자가 부족하기 때문에 그 영향이 가장 크며, 일부 사업자는 정밀도는 떨어지더라도 유지보수 빈도가 낮은 대안을 검토하고 있습니다.
부문별 분석
2025년, 다이어프램 펌프는 전 세계 매출의 63.35%를 차지했습니다. 누출이 없는 구조는 부식성 수처리 약품에 적합하며, 규정 준수를 중시하는 시장에서 확고한 리더십을 확립하고 있습니다. 업스트림 공정 사업자들이 주입 압력을 100바 이상으로 높이는 가운데, 플런저/피스톤식 모델 시장 규모는 연평균 7.02%로 확대되고 있습니다. 이러한 차이는 가혹한 조건 하에서 유량의 안정성이 높은 수명 주기 비용을 상쇄하는 고압 틈새 시장으로의 전환을 시사합니다. 기어 펌프, 로터리 로브 펌프, 페리스탈틱 펌프는 맥동이 없는 폴리머 혼련이나 위생적인 의약품 충전 등 보다 제한적인 요구 사항을 충족하고 있습니다.
최근 엘라스토머 기술의 발전으로 페리스탈틱 튜브의 수명이 40% 연장되어, 무균 투여 라인에서의 매력이 높아지고 있습니다. 기어 펌프와 로브 펌프는 연속적이고 전단 제어된 공급 속도가 중요한 폴리머 컴파운딩 분야에서 꾸준한 보급을 유지하고 있습니다. 이러한 동향들이 결합되어 계량 펌프 시장 내의 다양한 기술 구성을 뒷받침하고 있습니다.
모터 구동식 유닛은 견고한 구조와 기존 제어 루프와의 손쉬운 통합 덕분에 2025년 매출의 54.45%를 차지했습니다. 솔레노이드 구동식 펌프는 절대 수치로는 작지만, 에너지 효율과 디지털 네이티브 설계를 바탕으로 연간 5.88%의 속도로 시장 점유율을 확대되고 있습니다. 새로운 자기 회로 형상 덕분에 유량과 압력의 한계치가 약 3분의 1 정도 향상되는 동시에, 전력 소비량도 약 30% 감소했습니다. 공압식 및 유압식 구동 방식은 위험한 현장이나 전력 공급이 불충분한 현장에서 여전히 중요한 역할을 하고 있지만, 그 시장 점유율은 상승하기보다는 안정세를 보이고 있습니다.
솔레노이드 기술의 진화는 스마트 수처리 및 화학 플랜트의 급증과 맞물려, 이 아키텍처를 2031년까지 계량 펌프 시장의 성장 동력으로 자리매김하고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 39.55%를 차지하며 계량 펌프 시장을 주도했습니다. 중국의 최신 5개년 계획에는 산업 폐수 처리 시설의 광범위한 개보수가 포함되어 있는 반면, 인도의 ‘자르-지반 미션(Jal-Jivan Mission)’은 농촌 지역의 수질 개선을 위한 투자를 추진하고 있습니다. 싱가포르와 한국에서 고순도 의약품 시장이 성장함에 따라, 스키드 장착형으로 디지털 인증을 받은 투여 모듈에 대한 수요가 증가하고 있습니다. 범용 제품 분야에서는 현지 제조업체들이 수입 모델보다 저렴한 가격을 제시하고 있지만, 고압 사양이나 특수 소재를 사용한 제품의 경우 유럽 및 미국 브랜드가 여전히 프리미엄 시장 점유율을 유지하고 있습니다.
남미는 2031년까지 연평균 성장률(CAGR)이 5.27%로 가장 빠르게 성장하고 있는 지역입니다. 브라질의 새로운 위생법에 따라 염소 처리 및 pH 제어 도입이 진행되고 있으며, 남미의 다른 국가들에서는 제조업 확장에 따라 용매 재활용 및 폐수 중화 설비의 설치가 증가하고 있습니다. 각 공급업체는 현지 인프라에 대응하기 위해 전압 변동에 강한 드라이브와 간소화된 서비스 키트를 중시하고 있습니다.
북미와 유럽은 성숙한 시장이지만 혁신이 활발합니다. 이 지역의 유틸리티자들은 펌프와 클라우드 호스팅형 대시보드의 통합을 주도하고 있으며, MQTT나 OPC UA를 통해 상태를 전송하는 솔루션을 선호하고 있습니다. 미국 환경보호청(EPA)의 납·구리 규제 개정과 유럽의 PFAS 배출 기준 강화로 인해 투여 정밀도에 대한 기준치가 상향 조정되고 있습니다. 한편, 걸프 연안 국가의 생산자나 건조한 기후를 가진 아프리카 국가들은 해수 담수화 및 물 재이용에 투자를 집중하고 있어, 내식성이 뛰어난 PVDF 및 슈퍼 듀플렉스 펌프에 대한 수주는 꾸준히 이어지고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the metering pumps market size was valued at USD 7.5 billion in 2025 and estimated to grow from USD 7.79 billion in 2026 to reach USD 9.44 billion by 2031, at a CAGR of 3.92% during the forecast period (2026-2031).
This report is Segmented by Type (Diaphragm, Gear, Rotary Lobe, and More), Drive Mechanism (Motor-Driven, Solenoid-Driven, and More), Discharge Pressure (Up To 50 Bar, 51-100 Bar, and More), End-User (Water Treatment, Oil & Gas, Chemical Processing, Pharmaceuticals, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Metering Pumps Market Trends and Insights
Strict Industrial Waste-water Norms Accelerating Chemical Dosing in Asia
Sweeping 2024 amendments to China's Water Pollution Prevention and Control Law cut allowable effluent loads by 40%, forcing roughly 65,000 factories to add multiple chemical dosing points and digital data logging. Upgrades across electroplating, textile, and pharma corridors now account for 35% of all new installs in Asia, with IIoT-ready pumps preferred to satisfy record-keeping mandates mee.gov.cn. These standards are expected to ripple through Southeast Asia and India over the next three years, underpinning consistent demand growth within the metering pumps market.
Rapid Digitalization of Water Utilities Demanding Smart Dosing Accuracy
Utilities integrating SCADA and IoT platforms have uncovered 15-22% chemical savings when pumps adjust doses in real time. The shift is shortening replacement cycles from 12 years to near 8 years and raising average selling prices by one-quarter. Regions facing water scarcity, such as the US Southwest and parts of Spain, are early adopters as they balance quality assurance with chemical cost control. Service-based revenue models around predictive maintenance are emerging, enlarging the opportunity set for vendors.
Requirement of Frequent Maintenance
Mechanical diaphragm pumps often need service after 4,000-6,000 hours, interrupting continuous processes that can lose USD 5,000-15,000 per hour during downtime. Emerging markets suffer most because skilled technicians are scarce, prompting some operators to consider less precise but lower-maintenance alternatives.
Other drivers and restraints analyzed in the detailed report include:
- Fertigation Boom in High-Value Horticulture across the Middle East
- Increasing Offshore Enhanced-Oil-Recovery Chemical Injection Needs
- Growing Customization Demands (Fluid-Property-Driven Design Tweaks)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Diaphragm pumps controlled 63.35% of global revenue in 2025. Their leak-free architecture fits corrosive water-treatment chemistries, cementing leadership across compliance-driven markets. Plunger/piston models are expanding at 7.02% annually as upstream operators push injection pressures above 100 bar. This differential signals a migration toward high-pressure niches where flow stability under extreme conditions outweighs higher lifecycle costs. Gear, rotary lobe, and peristaltic designs address narrower needs such as pulse-free polymer blending or hygienic pharma fills.
Recent elastomer advances have extended peristaltic tube life by 40%, elevating their appeal in sterile dosing lines. Gear and lobe pumps maintain steady uptake in polymer compounding where continuous, shear-controlled feed rates matter. Collectively, these trends support a diverse technology mix inside the metering pumps market.
Motor-driven units captured 54.45% of 2025 sales thanks to rugged construction and simple integration with legacy control loops. Solenoid-driven pumps, though smaller in absolute value, are climbing 5.88% per year on the back of energy efficiency and digital-native design. New magnetic circuit geometries raise their flow and pressure ceiling by almost one-third while trimming power draw roughly 30%. Pneumatic and hydraulic drives retain roles in hazardous or power-poor sites, yet their share is stable rather than rising.
Solenoid evolution dovetails with the surge in smart water and chemical plants, positioning this architecture as a growth engine for the metering pumps market through 2031
Complete Report Scope:
- By Type
- Diaphragm
- Piston / Plunger
- Peristaltic
- Gear
- Rotary Lobe
- By Drive Mechanism
- Motor-Driven
- Solenoid-Driven
- Hydraulic-Driven
- Pneumatic-Driven
- By Discharge Pressure
- Up to 50 bar
- 51 - 100 bar
- 101 - 150 bar
- Above 150 bar
- By Pump Material
- Metallic (Stainless-steel, Alloy-20, Duplex)
- Non-Metallic (PVC, PVDF, PP)
- By End-User Industry
- Water Treatment
- Oil and Gas
- Chemical Processing
- Pharmaceuticals
- Food and Beverage
- Pulp and Paper
- Agriculture and Fertigation
- Mining and Minerals
- Textiles
- Power Generation and Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific dominated the metering pumps market with 39.55% of 2025 revenue. China's latest five-year plan earmarks widespread industrial effluent upgrades, while India's Jal Jeevan Mission drives rural water quality investments. High-purity pharma growth in Singapore and South Korea stimulates demand for skid-mounted, digitally certified dosing modules. Local manufacturers undercut imported models in commodity ranges, yet Western brands keep premium share in high-pressure or exotic-material builds.
South America is the fastest-growing geography at a 5.27% CAGR to 2031. Brazil's new sanitation law triggers chlorination and pH control rollouts, and other countries in South America export manufacturing sector increases solvent recycling and wastewater neutralization installations. Vendors emphasize voltage-tolerant drives and simplified service kits to suit local infrastructure.
North America and Europe are mature but innovation-intensive. Utility operators here spearhead integration of pumps with cloud-hosted dashboards, favoring solutions that broadcast status over MQTT or OPC UA. The US EPA's lead and copper rule revisions and Europe's tightening of PFAS discharge limits both raise dosing accuracy thresholds. Meanwhile, Gulf producers and arid African nations channel spending toward desalination and reuse, preserving a steady pipeline of orders for corrosion-resistant PVDF and super-duplex pumps.
- Grundfos Holding A/S
- IDEX Corporation
- PSG - Dover Corp.
- SPX Flow, Inc.
- LEWA GmbH (Nikkiso)
- ProMinent GmbH
- Milton Roy (Ingersoll Rand)
- Seko S.p.A
- Watson-Marlow Fluid Tech Grp. (Spirax-Sarco)
- Seepex GmbH
- Verder Group
- Blue-White Industries
- Xylem Inc.
- Flowserve Corporation
- Iwaki Co., Ltd.
- Netzsch Pumpen GmbH
- Atlas Copco (Lewa-Triplex)
- Roto Pumps Ltd.
- Haosh Pump Co.
- Swelore Engineering
- Tacmina Corp.
- Ingersoll Rand (Haskel)
- Idemitsu Kosan (Eagle Industry)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Strict Industrial Waste-water Norms Accelerating Chemical Dosing in Asia
- 4.2.2 Rapid Digitalization of Water Utilities Demanding Smart Dosing Accuracy
- 4.2.3 Fertigation Boom in High-Value Horticulture across the Middle East
- 4.2.4 Increasing Offshore Enhanced-Oil-Recovery (EOR) Chemical Injection Needs
- 4.2.5 Growing Use of High-Purity API Skids in Continuous-Flow Pharma Plants
- 4.2.6 Extensive Demand from Chemical Plants
- 4.3 Market Restraints
- 4.3.1 Requirement of Frequent Maintenance
- 4.3.2 Growing Customization Demands (Fluid-Property-Driven Design Tweaks)
- 4.3.3 Cavitation Risk in High-Viscosity Peristaltic Lines Limiting Adoption
- 4.3.4 Availability of Low-cost Chinese Knock-offs Eroding Margins Globally
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook (IIoT-enabled Smart Dosing, Predictive Sensors)
- 4.7 Investment Analysis
- 4.8 Porter's Five Forces
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Diaphragm
- 5.1.2 Piston / Plunger
- 5.1.3 Peristaltic
- 5.1.4 Gear
- 5.1.5 Rotary Lobe
- 5.2 By Drive Mechanism
- 5.2.1 Motor-Driven
- 5.2.2 Solenoid-Driven
- 5.2.3 Hydraulic-Driven
- 5.2.4 Pneumatic-Driven
- 5.3 By Discharge Pressure
- 5.3.1 Up to 50 bar
- 5.3.2 51 - 100 bar
- 5.3.3 101 - 150 bar
- 5.3.4 Above 150 bar
- 5.4 By Pump Material
- 5.4.1 Metallic (Stainless-steel, Alloy-20, Duplex)
- 5.4.2 Non-Metallic (PVC, PVDF, PP)
- 5.5 By End-User Industry
- 5.5.1 Water Treatment
- 5.5.2 Oil and Gas
- 5.5.3 Chemical Processing
- 5.5.4 Pharmaceuticals
- 5.5.5 Food and Beverage
- 5.5.6 Pulp and Paper
- 5.5.7 Agriculture and Fertigation
- 5.5.8 Mining and Minerals
- 5.5.9 Textiles
- 5.5.10 Power Generation and Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 United Kingdom
- 5.6.2.2 Germany
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Rest of Asia-Pacific
- 5.6.4 Middle East
- 5.6.4.1 Israel
- 5.6.4.2 Saudi Arabia
- 5.6.4.3 United Arab Emirates
- 5.6.4.4 Turkey
- 5.6.4.5 Rest of Middle East
- 5.6.5 Africa
- 5.6.5.1 South Africa
- 5.6.5.2 Egypt
- 5.6.5.3 Rest of Africa
- 5.6.6 South America
- 5.6.6.1 Brazil
- 5.6.6.2 Argentina
- 5.6.6.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Grundfos Holding A/S
- 6.4.2 IDEX Corporation
- 6.4.3 PSG - Dover Corp.
- 6.4.4 SPX Flow, Inc.
- 6.4.5 LEWA GmbH (Nikkiso)
- 6.4.6 ProMinent GmbH
- 6.4.7 Milton Roy (Ingersoll Rand)
- 6.4.8 Seko S.p.A
- 6.4.9 Watson-Marlow Fluid Tech Grp. (Spirax-Sarco)
- 6.4.10 Seepex GmbH
- 6.4.11 Verder Group
- 6.4.12 Blue-White Industries
- 6.4.13 Xylem Inc.
- 6.4.14 Flowserve Corporation
- 6.4.15 Iwaki Co., Ltd.
- 6.4.16 Netzsch Pumpen GmbH
- 6.4.17 Atlas Copco (Lewa-Triplex)
- 6.4.18 Roto Pumps Ltd.
- 6.4.19 Haosh Pump Co.
- 6.4.20 Swelore Engineering
- 6.4.21 Tacmina Corp.
- 6.4.22 Ingersoll Rand (Haskel)
- 6.4.23 Idemitsu Kosan (Eagle Industry)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment