

|
시장보고서
상품코드
2125315
메커니컬 씰 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Mechanical Seals - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
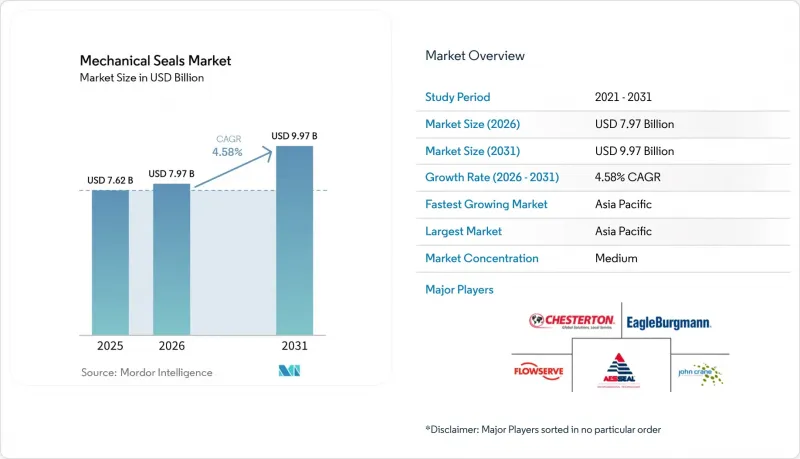
에 의하면, 메커니컬 씰 시장 규모는 2025년 76억 2,000만 달러로 평가되었습니다. 2026년에는 79억 7,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 4.58%로 성장을 지속하여, 2031년에는 99억 7,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 씰 유형(펌프용 씰, 압축기용 씰, 믹서용 씰), 설계 유형(컴포넌트/푸셔형, 카트리지형, 스플릿형), 최종 사용자 산업(석유 및 가스,발전, 화학, 상하수도, 기타 최종 사용자 산업), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 메커니컬 씰 시장 동향 및 인사이트
석유 및 가스 분야의 메가 프로젝트에 따른 수요 증가
사우디아라비아의 다운스트림 사업 진출은 원유에서 화학제품으로의 통합에 따라 추진되는 씰 요구 사항의 변화를 부각시키고 있습니다. 2027년 가동을 예정하고 있는 아람코(Aramco)의 아미랄 콤플렉스에서는 혼합 원료 크래커 및 고압 탄화수소 펌프를 위해 고품질의 씰이 요구됩니다. 현재 공급업체들은 극한의 온도나 부식성이 강한 석유화학 스트림에 내성을 가진 소재를 제공해야할 것으로 요구받고 있습니다. 존 크레인(John Crane)사의 ‘유형 8628VL’ 비접촉형 나선형 홈 씰은 수리 간격(MTBF)을 연장하는 동시에 플러싱 수요를 대폭 줄이는 것이 특징입니다. 이러한 대규모 프로젝트에서는 수명 주기 비용 절감이 예상되는 첨단 기술에 대한 선제적 투자가 중시되는 추세이며, 여전히 기존의 습식 씰 제품 라인에 의존하고 있는 공급업체들은 압박을 받고 있습니다.
신규 발전 용량의 급증
세계적으로 가스 터빈, 원자로, 재생에너지와 화석 연료를 결합한 하이브리드 발전 설비의 도입이 증가하고 있습니다. 그러나 씰에 대한 주요 수요는 보조 급수 펌프, 냉각 회로, 증기 터빈에 집중되어 있습니다. 영국의 한 정유시설에서 AESSEAL사의 STS 증기 터빈 씰을 사후 장착한 결과, 1대당 연간 증기 소비량을 대폭 절감할 수 있었습니다. 이 업그레이드를 통해 터빈의 수명이 연장되었으며, 설비 전체적으로 연간 상당한 비용 절감 효과를 거두었습니다. 전력 계통에 간헐적인 재생에너지 도입이 진행됨에 따라 복합 사이클 터빈의 가동 빈도는 더욱 높아질 것으로 예측됩니다. 이러한 가동 빈도 증가는 씰의 마모를 가속화하여 애프터마켓 수요의 급증으로 이어질 것입니다. 장래에는 모듈형 원자력 발전 개념이나 폐쇄형 냉각 시스템의 도입으로 인해 동적 씰의 수가 감소하여 매우 장기적인 성장세는 둔화될 가능성이 있지만, 당분간은 견조한 수요가 예상됩니다.
연마성 슬러리 용도에서의 높은 수명 주기 비용
광업 및 펄프 제조 사업자들은 슬러리용 씰의 높은 가격을 피하기 위해 패킹식 그랜드나 익스펠러 장치를 선택하는 경우가 많습니다. 이러한 선택은 내구성보다 재고 관리의 간소화를 우선시하고 있음을 나타냅니다. 반면, 존 크레인(John Crane)사의 SB2 듀얼 카트리지 기술은 외부 플러싱을 불필요하게 하고 수명을 연장하지만, 현장에서의 채택 여부는 주로 기술 지원 및 성능 보증이 함께 제공되는지에 크게 좌우됩니다. 이러한 보증은 초기 투자 부담을 상쇄하기 위한 것입니다. 부가적인 서비스를 제공하지 않고 제품만 판매하는 공급업체는 연마 작업 분야에서 뒤처지게 됩니다.
부문별 분석
펌프용 씰은 2025년에 매출의 64.35%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 4.56%를 기록할 전망입니다. 기존 원심 펌프의 개조가 안정적인 애프터마켓 판매를 뒷받침하고 있지만, 청정 화학물질 처리 분야에서는 씰리스화로의 전환으로 인해 기존 설비 시장이 취약한 상황에 놓여 있습니다. 비접촉형 나선형 홈 설계와 업스트림 측 펌프 면이 현재 혁신의 주류를 이루고 있으며, 공급업체는 에너지 절약 및 배출 규제 준수를 중심으로 한 업그레이드를 제안할 수 있게 되었습니다. 압축기용 씰은 판매 수량은 적지만, 기술적 복잡성과 규제 집행 강화로 인해 높은 평균 판매 가격을 실현하고 있습니다. 믹서용 씰은 여전히 틈새 시장이지만, 위생 관리가 요구되는 반응기에서는 필수적이며 높은 이익률을 유지하고 있습니다.
펌프 용도의 메커니컬 씰 시장 규모는 꾸준히 확대될 전망이지만, 아시아 제조업체들이 저비용 접촉면 카트리지를 공급하고 있어 경쟁은 치열해지고 있습니다. 유서 깊은 브랜드들은 디지털 진단, 성능 보증, 신속한 현장 서비스를 통해 차별화를 꾀하고 있습니다.
지역별 분석
아시아태평양은 2025년 메커니컬 씰 시장 매출의 36.35%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 4.68%라는 가장 높은 성장률을 나타낼 것으로 전망됩니다. 중국의 정유, 석유화학, 전력 분야에서의 사업 확장이 큰 수요를 견인하고 있습니다. 또한, 전해조 제조 분야에서 중국의 주도적인 입지가 수소 대응 씰의 조기 도입을 뒷받침하고 있습니다. 이에 이어 인도는 정유시설 및 수자원 인프라 프로젝트를 확대되고 있습니다. 그러나 가격 민감성으로 인해 표준 펌프 사업에서는 국내 제조업체가 선호되고 있습니다. 한편, 일본과 한국은 시장 규모는 작지만, LNG 및 반도체 용도의 고성능 씰에 투자하여 고수익률의 틈새 시장을 개척하고 있습니다.
북미는 2025년에 두드러진 시장 점유율을 차지했습니다. EPA(미국 환경보호청)의 메탄 규제로 인해 멕시코만 연안 지역의 중류 네트워크 전반에 걸쳐 드라이 가스용 씰의 개보수가 진행되고 있습니다. LNG 수출 터미널 및 석유화학 플랜트의 병목 현상 해소를 위한 설비 투자가 수주를 뒷받침하는 한편, 노후화된 설비 기반이 애프터마켓의 안정성을 확보하고 있습니다. 캐나다에서는 오일샌드에 대한 관세가 내마모성 듀얼 씰 수요를 끌어올리고 있지만, 파이프라인 프로젝트의 지연으로 인해 설비 투자에 변동이 발생하고 있습니다.
유럽은 시장 가치의 상당 부분을 차지했습니다. 탄소 포집, 수소 전기분해 장치, 해상 풍력 발전과 같은 에너지 전환에 초점을 맞춘 프로젝트가 성장을 가속하고 있지만, 인허가 지연으로 인해 진척이 더뎌지는 경우가 많습니다. 독일과 영국은 수소 파이프라인 분야에서 주도적인 역할을 하고 있으나, 2026년부터 2028년에 걸친 수익의 대부분은 산업용 가스 및 특수 화학제품의 업그레이드에서 비롯될 것으로 예측됩니다. 중동 및 아프리카 시장 점유율은 작지만, 해당 업계 최대 규모의 프로젝트에 참여하고 있습니다. 주목할 만한 사업으로는 사우디아라비아의 원유에서 화학제품으로의 전환, ADNOC의 이산화탄소 포집 및 저장(CCS) 사업, 그리고 남아프리카의 광업 부문 등이 있으며, 이들 모두 프로젝트별로 수백 개의 씰이 필요합니다. 그러나 공급업체들은 물류 경로의 길이와 매출채권 회수 기간의 장기화 같은 과제에 직면해 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the mechanical seals market size is expected to grow from USD 7.62 billion in 2025 to USD 7.97 billion in 2026 and is forecast to reach USD 9.97 billion by 2031 at a 4.58% CAGR over 2026-2031.
This report is Segmented by Seal Type (Pump Seals, Compressor Seals, and Mixer Seals), Design Type (Component/Pusher, Cartridge, and Split), End-User Industry (Oil and Gas, Power Generation, Chemical, Water and Waste-Water, and Other End-User Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). Market Forecasts are Provided in Terms of Value (USD).
Global Mechanical Seals Market Trends and Insights
Growing Demand from Oil and Gas Megaprojects
Saudi Arabia's push into downstream operations highlights a shift in seal requirements driven by crude-to-chemicals integration. Aramco's Amiral complex, set to commence operations in 2027, will demand premium seals for its mixed-feed crackers and high-pressure hydrocarbon pumps. Suppliers are now tasked with providing materials resilient to extreme temperatures and corrosive petrochemical streams. John Crane's Type 8628VL non-contacting spiral-groove seal boasts an extended mean time between repairs while significantly reducing flush demand. Such large-scale projects lean towards upfront investments in advanced technology, promising lifecycle savings, and putting pressure on vendors still dependent on traditional wet-seal lines.
Surge in New Power-Generation Capacity Additions
Worldwide installations of gas turbines, nuclear reactors, and hybrid renewables are on the rise. Yet, the primary demand for seals is concentrated in auxiliary feed-water pumps, cooling circuits, and steam turbines. A retrofit of AESSEAL's STS steam turbine seal at a refinery in the UK resulted in significant steam savings annually per unit. This upgrade extended the turbine's lifespan, translating to impressive annual fleet savings. As grids increasingly incorporate intermittent renewables, combined-cycle turbines are set to cycle more frequently. This heightened activity accelerates seal wear, leading to a surge in aftermarket volumes. On the horizon, while modular nuclear concepts and closed-loop cooling might reduce the number of dynamic sealing points, tempering growth in the very long term, the immediate future looks robust.
High Life-Cycle Cost in Abrasive Slurry Services
Mining and pulp operators frequently opt for packed glands or expeller devices, shunning the premium on slurry seals. Their choice underscores a preference for inventory simplicity over longevity. Meanwhile, John Crane's SB2 dual-cartridge technology, which eliminates the need for an external flush and extends service life, sees its field adoption largely dependent on bundled technical support and performance guarantees. These assurances aim to counterbalance the initial investment. Vendors who solely push products without added services find themselves sidelined in abrasive tasks.
Other drivers and restraints analyzed in the detailed report include:
- Tightening Fugitive-Emission Regulations Worldwide
- Capacity Expansion in Chemical and Petrochemical Complexes
- Seal-Less Mag-Drive and Canned-Motor Pumps Eroding Addressable Market
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Pump seals generated 64.35% revenue in 2025 and will track a 4.56% CAGR to 2031. Retrofits into existing centrifugal pumps underpin stable aftermarket sales, but the installed base is vulnerable to seal-less migration in clean chemical services. Non-contacting spiral-groove designs and upstream-pumping faces now headline innovation, allowing suppliers to frame upgrades around energy savings and emissions compliance. Compressor seals, though lower in volume, achieve higher average selling prices via technical complexity and rising regulatory enforcement. Mixer seals remain niche yet mission-critical in hygiene-sensitive reactors, sustaining premium margins.
While the mechanical seals market size for pump applications will expand steadily, competitive intensity is sharpening as Asian manufacturers offer low-cost contact-face cartridges. Established brands differentiate through digital diagnostics, performance warranties, and rapid local service.
Complete Report Scope:
- By Seal Type
- Pump Seals
- Compressor Seals
- Mixer Seals
- By Design Type
- Component/Pusher
- Cartridge
- Split
- By End-user Industry
- Oil and Gas
- Power Generation
- Chemical
- Water and Waste-water
- Other End-user Industries (Mining and Mineral Processing, Food, Pharma, etc.)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific captured 36.35% of the mechanical seals market revenue in 2025 and is projected to post the fastest 4.68% CAGR through 2031. China's expansions in refining, petrochemicals, and power sectors drive a significant demand. Additionally, China's leadership in electrolyser manufacturing has spurred an early adoption of hydrogen-ready seals. Following closely, India is ramping up its refinery and water infrastructure projects. However, due to price sensitivities, the standard pump business is leaning towards domestic producers. Meanwhile, Japan and South Korea, despite their smaller size, are investing in high-performance seals for LNG and semiconductor applications, carving out premium-margin niches.
North America commanded a notable market share in 2025. The EPA's methane regulations are driving retrofits of dry-gas seals throughout the Gulf Coast's midstream network. Capital orders are bolstered by LNG export terminals and petrochemical debottlenecks, while an aging installed base ensures stability in the aftermarket. In Canada, duties on oil sands are pushing the demand for abrasion-resistant dual seals, yet delays in pipeline projects introduce volatility in capital expenditures.
Europe represented a considerable portion of the market value. Projects focused on energy transition-like carbon capture, hydrogen electrolysers, and offshore wind-are fostering growth, though progress is often slowed by permitting delays. Germany and the UK are taking the lead in hydrogen pipelines, yet the bulk of revenues from 2026 to 2028 are anticipated to stem from upgrades in industrial gas and specialty chemicals. While the Middle East and Africa hold a smaller market share, they are involved in some of the industry's largest projects. Notable undertakings include Saudi Arabia's push from crude to chemicals, ADNOC's venture in carbon capture and storage, and South Africa's mining sector-all of which demand hundreds of seals per project. However, suppliers face challenges with longer logistics routes and extended receivables.
- A.W. Chesterton Company
- AESSEAL
- Dana Limited
- Eagle Industry Co., Ltd.
- EagleBurgmann
- Flexaseal Engineered Seals and Systems, LLC
- Flowserve Corporation
- Gallagher Seals
- Garlock
- Hutchinson Industries Inc.
- John Crane
- Parker Hannifin Corp
- SKF
- Technetics Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand from oil and gas megaprojects
- 4.2.2 Surge in new power-generation capacity additions
- 4.2.3 Tightening fugitive-emission regulations worldwide
- 4.2.4 Capacity expansion in chemical and petrochemical complexes
- 4.2.5 Hydrogen and green-ammonia cryogenic infrastructure build-out
- 4.3 Market Restraints
- 4.3.1 High life-cycle cost in abrasive slurry services
- 4.3.2 Seal-less mag-drive and canned-motor pumps eroding addressable market
- 4.3.3 SiC face-material price volatility and supply-chain risk
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Seal Type
- 5.1.1 Pump Seals
- 5.1.2 Compressor Seals
- 5.1.3 Mixer Seals
- 5.2 By Design Type
- 5.2.1 Component/Pusher
- 5.2.2 Cartridge
- 5.2.3 Split
- 5.3 By End-user Industry
- 5.3.1 Oil and Gas
- 5.3.2 Power Generation
- 5.3.3 Chemical
- 5.3.4 Water and Waste-water
- 5.3.5 Other End-user Industries (Mining and Mineral Processing, Food, Pharma, etc.)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 A.W. Chesterton Company
- 6.4.2 AESSEAL
- 6.4.3 Dana Limited
- 6.4.4 Eagle Industry Co., Ltd.
- 6.4.5 EagleBurgmann
- 6.4.6 Flexaseal Engineered Seals and Systems, LLC
- 6.4.7 Flowserve Corporation
- 6.4.8 Gallagher Seals
- 6.4.9 Garlock
- 6.4.10 Hutchinson Industries Inc.
- 6.4.11 John Crane
- 6.4.12 Parker Hannifin Corp
- 6.4.13 SKF
- 6.4.14 Technetics Group
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


