

|
시장보고서
상품코드
2125317
자석 와이어 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Magnet Wire - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
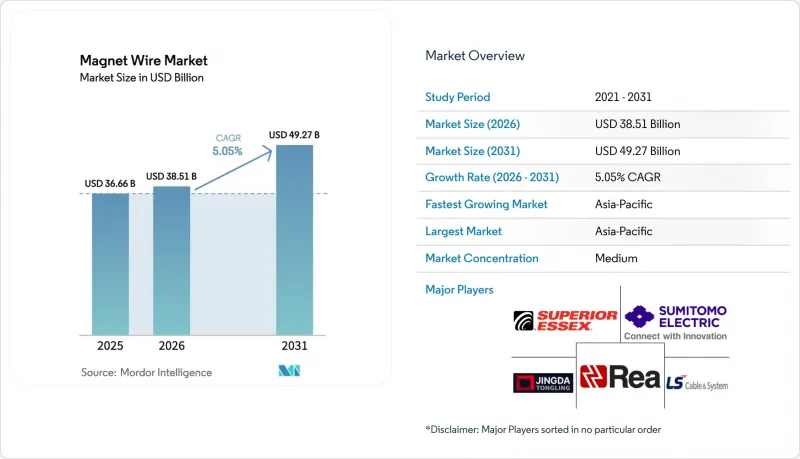
에 의하면, 자석 와이어 시장 규모는 2025년 366억 6,000만 달러로 평가되었고, 2026년에는 385억 1,000만 달러로 추정되고, 2031년까지 492억 7,000만 달러에 이를 것으로 예상되며, 2026-2031년 CAGR 5.05%로 성장할 전망입니다.
본 보고서는 소재별(구리·알루미늄), 절연 유형별(에나멜선·피복 도선), 형상별(원형·직사각형/평형), 최종 이용 산업별(전기자동차, 에너지, 산업용), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 자석 와이어 시장 동향 및 인사이트
급증하는 전기차 생산
2025년 상반기 중국의 신규 등록 대수는 562만 대에 달했으며, 국내 NEV(신에너지차) 보유 대수는 3,689만 대로 증가했습니다. 이로 인해 반기 동안만 16,000-27,000톤의 새로운 사각형 자석 와이어 수요가 발생했습니다. 인도에서 2,593억 8,000만 루피 규모의 PLI-Auto 프로그램에서는 50%의 국내 부가가치를 요구하고 있으며, 이에 따라 현지에서 트랙션 모터용 권선 라인 설치가 촉진되고 있습니다. 스미토모 전기공업은 EV 거점에서의 사각형 자석 와이어 생산 능력을 확대한 후, 2024년도에 자석 와이어 매출액으로 2,282억 엔을 기록하여 전년 대비 13.2% 증가했습니다. 헤어핀 구조를 채택함으로써 슬롯 충진율은 기존 50-60%에서 70-80%로 향상되었으며, 모터 1대당 도체 사용량은 감소한 반면, Kg당 가격은 상승했습니다. 일본은 2025년 2월 발표한 ‘녹색 성장 전략’에서 10년간 150조 엔을 투자하겠다고 약속했으며, 이는 지역 내 고품질 구리 도체에 대한 수요를 뒷받침하고 있습니다.
재생에너지 설비의 확대
국제에너지기구(IEA)는 송전망에 대한 연간 투자액이 2023년 1,400억 달러에서 2030년대 중반에는 2,000억 달러를 넘어설 것으로 예측했습니다. 해상 풍력 발전 1기가와트당 승압 변압기 및 케이블 종단 처리에 약 200-300톤의 자석 와이어가 필요하기 때문에 에나멜 피복 구리선에 대한 수요가 급격히 증가하고 있습니다. 지멘스 에너지(Siemens Energy)는 2024년 9월, 변압기용 구리 재료를 ‘Copper-Mark’ 인증을 받은 재활용 구리로 전면 전환하기로 합의했습니다. 이는 전력 회사가 추적성(추적 가능성)에 대한 프리미엄을 지불한다는 초기 증거라고 할 수 있습니다. 중국 국가전망은 2027년까지 2,800만 대의 전기차 충전기를 설치하는 것을 목표로 하고 있으며, 각 충전기에는 100-500kVA의 배전용 변압기가 필요합니다. 이를 합산하면 연간 4만-6만 톤의 에나멜선이 소비될 것으로 예측됩니다. 미국의 ‘인플레이션 억제법’과 EU의 ‘REPowerEU’에 따른 허가 절차의 신속화로 인해, 풍력 발전소 가동 시작부터 변압기 조달까지의 시간차가 단축되고 있습니다.
원자재 가격 변동
J.P. 모건은 2026년 구리의 평균 가격이 1만 2,075달러/t가 되어 33만 t공급 부족이 발생할 것으로 예측했습니다. 한편, 세계은행은 2025년 가격을 9,700달러/t 정도로 추정하고 있으며, 헤지를 하지 않을 경우 생산자의 매출 총이익을 잠식할 수도 있는 20-25%의 가격 변동이 발생할 것으로 보입니다. IMF 데이터에 따르면, 2024년 2월부터 8월에 걸쳐 8.1%의 상승세가 나타나, 장기 전선 계약에서 분기별 에스컬레이터 조항의 발동이 불가피한 상황입니다. 알루미늄은 동등한 전도성에서 구리보다 39% 저렴한 상태를 유지하고 있지만, 기니의 보크사이트 채굴 상한 규제 및 유럽 제련소의 전기 요금 급등에 직면하여 가격 면에서의 우위가 축소되고 있습니다. 폴리아미드이미드·폴리에스테르이미드 에나멜 도료는 석유화학 원료에 의존하고 있기 때문에 절연재 비용은 브렌트 원유 가격 변동이나 수지 공장에서 발생하는 정기적인 불가항력적 사건의 영향을 받기 쉬운 상황입니다.
부문별 분석
2025년, 구리는 278억 달러 규모의 자석 와이어 시장 중 72.13%를 차지한 것으로 평가되었으며, 2031년까지 연평균 성장률(CAGR) 5.45%로 확대될 것으로 전망됩니다. 알루미늄이 차지하는 자석 와이어 시장 점유율은 밀도가 39% 낮다는 장점 덕분에 항공기용 액추에이터나 장거리 가공 송전선 등 공간이 제한된 권선 분야에서 수요가 증가하고 있습니다. 스미토모 전기공업의 2024년도 급증은 전기차용 헤어핀 코일 수요를 반영한 것이며, 한편 에섹스·후루카와의 폐쇄 루프 모델은 4만 3,000톤의 구리 스크랩을 회수하고 있어, 재활용 재료의 사용이 높이 평가되는 지역에서 경쟁 우위를 점하고 있습니다. 가전용 압축기에서는 구리 피복 알루미늄의 시범 도입이 계속되고 있지만, 진동 피로에 대한 우려로 인해 자동차 분야에서의 대규모 채택이 저해되고 있습니다. ‘더 코퍼 마크(The Copper Mark)’와 같은 인증 프로그램으로 인해 투명성에 대한 기대가 높아지고 있지만, 많은 1차 알루미늄 제련소는 아직 그 수준에 미치지 못하고 있습니다.
가격 동향은 여전히 결정적인 요인으로 작용하고 있습니다. J.P. 모건이 예측한 2026년 톤당 1만 2,075달러라는 가격은 각 OEM 업체들의 헤지 거래를 뒷받침하고 있는 반면,세계은행이 제시한 2025년 톤당 9,700달러라는 다소 보수적인 전망은 현물 구매자들에게 숨을 돌릴 여지를 주고 있습니다. 봉재 공장을 통합하고 있는 생산자는 위탁 인출 업체보다 신속하게 비용을 고정할 수 있으므로, 시세가 급등할 때에도 EBIT 마진을 유지할 수 있습니다. 반면, 알루미늄 업계는 전력 가격의 불확실성에 직면해 있습니다. 유럽의 제련소들은 가스 가격 지표가 상승함에 따라 2025년 초에 연간 50만 톤의 생산 능력을 가동 중단할 예정이며, 이로 인해 전선 구매자들공급 계획은 복잡해지고 있습니다.
에나멜 제품은 전기차(EV)용 구동 모터 및 고압 변압기에 요구되는 클래스 H·클래스 C 규격을 충족하는 박층 폴리아미드이미드·폴리에스테르이미드 코팅 덕분에 2025년 매출의 94.04%를 차지했습니다. 피복선은 탭 체인저나 수리용 코일에 사용되지만, 슬롯 충진율이 20-30% 저하된다는 과제가 있어 콤팩트한 프레임에의 채택이 제한되고 있습니다. 후지쿠라는 모서리가 날카로운 부분에서도 절연 내력을 유지하면서, 각형 전선에서 ±2µm의 에나멜 코팅 균일성을 실현할 수 있는 정밀 노즐에 투자했습니다. 2027년 6월 IE4 모터 규제가 강화됨에 따라, 정격 저하 없이 고온에서 작동 가능한 내열 등급 수요가 증가하여 에나멜 피복의 입지가 더욱 공고해질 것입니다.
수지 원료 가격 변동이 주요 위험 요인으로 작용하고 있습니다. 폴리아미드이미드 모노머는 원유 가격 변동에 연동되어 있으며, 2025년 7월부터 10월에 걸쳐 브렌트유 가격이 19% 상승했을 때 에나멜선의 원가가 한 자릿수 중반대까지 상승한 것이 그 증거입니다. 각 공급업체는 스코프 3 배출량을 줄이기 위해 바이오 유래 디산(diacid)을 채택하고 있으며, 이 전략은 석유화학제품 가격의 급등에 대한 완충재 역할도 합니다. 현재 JCMA의 시험 프로토콜에는 고주파 인버터의 장기 사이클 수명을 보장하기 위해 직사각형 모서리 부분의 부분 방전 및 코로나 내성 시험이 포함되어 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 59.15%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 6.07%라는 견조한 성장세를 보이고 있습니다. 중국 공업정보화부(MIIT)가 제시한 2025년 신에너지차(NEV) 판매 대수 1,550만 대라는 목표와, 국가전망이 수립한 전기차 충전기 2,800만 기 계획은 구동 모터 및 배전 변압기 권선에 대한 구조적인 수요를 뒷받침하고 있습니다. 인도의 ‘PLI-Auto’, ‘PM E-DRIVE’, ‘ACC’ 배터리 장려책(총액 5,493.8억 루피)은 현지 전선 조달을 촉진하고, 구자라트주·타밀나두주에서의 송전선 설치를 뒷받침하고 있습니다. 일본의 150조 엔 규모 ‘녹색 성장 전략’은 해상 풍력 발전 및 전동 드라이브트레인으로 자본을 유도하고 있어, 고품질 각형 도체에 대한 수요를 지속시키고 있습니다. 한국의 LS Cable &System은 자회사인 LS Eco Energy가 2030년까지 13억 달러의 매출을 달성할 것으로 전망하고 있으며, 그 원인 중 하나로 IRA(인플레이션 억제법)의 국내 조달 크레딧 대상이 되는 미국 내 자석 와이어에 대한 투자를 꼽고 있습니다.
북미에서는 IE4 규제가 단계적으로 도입되고 있으며, 인플레이션 억제법(IRA)에 따라 고전압 직류 송전(HVDC) 및 에너지 저장 프로젝트가 가속화되고 있어 꾸준한 교체 수요가 예상됩니다. 에섹스 솔루션즈의 2억 달러 규모의 IPO 전 자금 조달 및 2025년 시가총액 14억 달러를 목표로 한 상장 계획은 이러한 전망을 반영하고 있습니다. 현재 전력 회사들은 Copper-Mark 인증을 받은 전선을 지정하고 있으며, 이로 인해 재활용 업체들은 1차 구리 사용자보다 유리한 입지에 있습니다.
유럽은 취급량 면에서는 다소 뒤처져 있지만, 지속가능성에 관한 규제 면에서는 앞서고 있습니다. 지멘스 에너지의 100% 재생 구리 조달 방침은 송전망 사업자 전반으로 확산될 가능성이 있는 조달 모델의 선례가 되고 있습니다. ‘REPowerEU’ 계획에 따라 송전망 허가 절차가 신속화되면서, 독일과 스페인의 변압기 OEM 제조업체를 대상으로 한 에나멜선 주문이 증가하고 있습니다. 남미는 브라질의 풍력 발전 붐의 혜택을 받고 있으며, 중동에서는 사우디아라비아의 NEOM 건설에 따른 자석 와이어 수요가 급증하고 있습니다. 아프리카는 여전히 규모는 작지만, 분산형 풍력 발전과 미니 그리드가 디젤 발전을 대체하는 형태로 성장을 이어가고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the magnet wire market size is expected to increase from USD 36.66 billion in 2025 to USD 38.51 billion in 2026 and reach USD 49.27 billion by 2031, growing at a CAGR of 5.05% over 2026-2031.
This report is Segmented by Material (Copper and Aluminium), Insulation Type (Enameled Wire and Covered Conductor Wire), Shape (Round and Rectangular/Flat), End-Use Industry (Electric Vehicles, Energy, and Industrial), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). Market Forecasts are Provided in Terms of Value (USD).
Global Magnet Wire Market Trends and Insights
Surging Electric-Vehicle Production
First-half 2025 Chinese registrations hit 5.62 million units, lifting the national NEV fleet to 36.89 million vehicles and translating to 16,000-27,000 t of new rectangular wire demand in a single semester. India's INR 25,938 crore PLI-Auto program requires 50% domestic value addition, prompting local traction-motor winding lines. Sumitomo Electric logged JPY 228.2 billion magnet-wire revenue in FY 2024, up 13.2%, after expanding rectangular capacity at EV hubs. Hairpin architectures elevate slot-fill density to 70-80% from the legacy 50-60%, boosting kilogram pricing despite lower conductor volume per motor. Japan's February 2025 Green Growth Strategy commits JPY 150 trillion over 10 years, underpinning regional demand for high-grade copper conductors.
Expanding Renewable-Energy Installations
The International Energy Agency expects annual transmission-grid investment to exceed USD 200 billion by the mid-2030s, up from USD 140 billion in 2023. Every gigawatt of offshore wind needs about 200-300 t of magnet wire for step-up transformers and cable terminations, creating an outsized pull for enamel-coated copper. Siemens Energy agreed in September 2024 to shift entirely to Copper-Mark-certified recycled copper for transformers, an early proof that utilities will pay traceability premiums. China's State Grid aims for 28 million EV chargers by 2027, each relying on 100-500 kVA distribution transformers that together will consume 40,000-60,000 t of enamel wire yearly. Faster permitting under the U.S. Inflation Reduction Act and the EU's REPowerEU shortens the lag between wind-farm commissioning and transformer procurement.
Raw-Material Price Volatility
J.P. Morgan sees copper averaging USD 12,075/t in 2026 on a 330,000 t deficit, whereas the World Bank pegs 2025 prices closer to USD 9,700/t, framing a 20-25% swing that can eliminate producer gross margin when not hedged. IMF data show an 8.1% rally between February and August 2024, forcing quarterly escalator clauses into long-term wire contracts. Aluminum remains 39% lighter than copper at equivalent conductivity, yet faces bauxite mining caps in Guinea and elevated European smelting power tariffs, trimming its headline pricing advantage. Polyamide-imide and polyesterimide enamels rely on petrochemical feedstocks, exposing insulation costs to Brent crude volatility and periodic force-majeure events at resin plants.
Other drivers and restraints analyzed in the detailed report include:
- Growing Consumer-Electronics Output
- Demand for Distributed Wind Micro-Generators
- PCB Stator Technology Replacing Wound Coils
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Copper accounted for 72.13% of the magnet wire market size at USD 27.8 billion in 2025 and is forecast to expand at a 5.45% CAGR to 2031. The magnet wire market share held by aluminum benefits from a 39% lower density that appeals to space-constrained windings in aircraft actuators and long-span overhead lines. Sumitomo Electric's FY 2024 surge reflects EV hairpin demand, while Essex Furukawa's closed-loop model recovered 43,000 t of copper scrap, an advantage in regions that reward recycled content. Copper-clad aluminum trials continue in appliance compressors, but vibration-fatigue concerns impede large-scale automotive take-up. Certification programs like The Copper Mark elevate transparency expectations that many primary aluminum smelters have yet to match.
Pricing dynamics remain the decisive lever. J.P. Morgan's USD 12,075/t 2026 forecast drives OEM hedging, whereas the World Bank's softer USD 9,700/t 2025 view offers breathing room for spot buyers. Producers with integrated rod mills lock cost faster than toll-drawers, preserving EBIT margins when quotes spike. In parallel, aluminum faces power-price uncertainty: European smelters idled 500,000 t annual capacity in early 2025 after gas benchmarks climbed, complicating supply planning for wire buyers.
Enameled products captured 94.04% of 2025 revenue thanks to thin polyamide-imide and polyesterimide coats that hit Class H and Class C ratings demanded by EV traction motors and HV transformers. Covered wire serves tap-changer and repair coils but suffers a 20-30% slot-fill penalty that limits uptake in compact frames. Fujikura invested in precision nozzles capable of +-2 µm enamel uniformity on rectangular wire, preserving dielectric strength at sharp corners. Tightening IE4 motor rules in June 2027 boosts demand for higher-temperature grades able to run hotter without derating, further consolidating enamel's position.
Resin feedstock volatility poses the main risk. Polyamide-imide monomers track crude-oil swings, evidenced when Brent gained 19% between July and October 2025, lifting enamel costs by mid-single digits. Suppliers are adopting bio-sourced diacids to cut Scope 3 emissions, a strategy that also cushions against petrochemical price shocks. JCMA test protocols now include partial discharge and corona endurance on rectangular edges to guarantee long-cycle life in high-frequency inverters.
Complete Report Scope:
- By Material
- Copper
- Aluminium
- By Insulation Type
- Enameled Wire
- Covered Conductor Wire
- By Shape
- Round
- Rectangular / Flat
- By End-use Industry
- Electric Vehicles
- Energy
- Transformers
- Other Energy Types
- Industrial
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific anchored 59.15% of 2025 revenue, expanding at a robust 6.07% CAGR through 2031. China's MIIT target of 15.5 million NEV sales in 2025 and State Grid's 28 million EV-charger plan embed structural demand for both traction-motor and distribution-transformer windings. India's PLI-Auto, PM E-DRIVE, and ACC battery incentives worth a combined INR 54,938 crore favor local wire procurement, boosting line installations in Gujarat and Tamil Nadu. Japan's JPY 150 trillion Green Growth Strategy routes capital toward offshore wind and electrified drivetrains, sustaining demand for premium rectangular conductors. South Korea's LS Cable & System expects its LS Eco Energy affiliate to reach USD 1.3 billion in revenue by 2030, partly through U.S. magnet-wire investments that qualify for IRA domestic-content credits.
North America shows steady replacement demand as the IE4 rule phases in and as the Inflation Reduction Act accelerates HVDC and storage projects. Essex Solutions' USD 200 million pre-IPO raise and planned 2025 listing at USD 1.4 billion value reflect this outlook. Utilities now specify Copper-Mark-certified wire, positioning recyclers ahead of primary-copper users.
Europe trails slightly in tonnage yet leads in sustainability mandates. Siemens Energy's 100% recycled-copper sourcing sets a procurement template likely to spread across grid operators. The REPowerEU plan is fast-tracking grid permits, lifting enamel-wire call-offs for transformer OEMs in Germany and Spain. South America benefits from Brazil's wind boom, and the Middle East records magnet-wire spikes tied to Saudi Arabia's NEOM builds. Africa remains small but growing where distributed wind and mini-grids replace diesel.
- Citychamp Dartong Co.
- Condumex, Inc.
- Dahren Group
- Ederfil Becker
- ELEKTRISOLA Dr. Gerd Schildbach GmbH & Co KG.
- Essex Solutions Inc.
- Fujikura Ltd.
- HENAN HUAYANG ELECTRICAL TECHNOLOGY GROUP CO.,LTD
- IRCE S.p.A.
- LS Cable & System Ltd.
- MWS Wire Industries, Inc.
- Phelps Dodge Philippines
- Proterial, Ltd.
- Rea
- Reco Zrt.
- Sam Dong Co, Ltd.
- Sumitomo Electric Industries, Ltd.
- Superior Essex Inc.
- SWCC Corporation
- Taihan Cable & Solution Co., Ltd.
- Tongling Jingda Special Magnet Wire Co., Ltd
- Tre Tau Engineering s.r.l
- Xinzhu Cable Group
- ZTT
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging electric-vehicle (EV) production
- 4.2.2 Expanding renewable-energy installations
- 4.2.3 Growing consumer-electronics output
- 4.2.4 Rapid industrial automation and motor upgrades
- 4.2.5 Demand for distributed wind micro-generators
- 4.3 Market Restraints
- 4.3.1 Raw-material price volatility (Cu, Al, and resins)
- 4.3.2 PCB stator technology replacing wound coils
- 4.3.3 Compact axial-flux motors reducing wire usage
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
- 4.6 Price Analysis
- 4.6.1 Copper Magnet Wire
- 4.6.2 Aluminium Magnet Wire
5 Market Size and Growth Forecasts (Value)
- 5.1 By Material
- 5.1.1 Copper
- 5.1.2 Aluminium
- 5.2 By Insulation Type
- 5.2.1 Enameled Wire
- 5.2.2 Covered Conductor Wire
- 5.3 By Shape
- 5.3.1 Round
- 5.3.2 Rectangular / Flat
- 5.4 By End-use Industry
- 5.4.1 Electric Vehicles
- 5.4.2 Energy
- 5.4.2.1 Transformers
- 5.4.2.2 Other Energy Types
- 5.4.3 Industrial
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 Italy
- 5.5.3.4 France
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)}
- 6.4.1 Citychamp Dartong Co.
- 6.4.2 Condumex, Inc.
- 6.4.3 Dahren Group
- 6.4.4 Ederfil Becker
- 6.4.5 ELEKTRISOLA Dr. Gerd Schildbach GmbH & Co KG.
- 6.4.6 Essex Solutions Inc.
- 6.4.7 Fujikura Ltd.
- 6.4.8 HENAN HUAYANG ELECTRICAL TECHNOLOGY GROUP CO.,LTD
- 6.4.9 IRCE S.p.A.
- 6.4.10 LS Cable & System Ltd.
- 6.4.11 MWS Wire Industries, Inc.
- 6.4.12 Phelps Dodge Philippines
- 6.4.13 Proterial, Ltd.
- 6.4.14 Rea
- 6.4.15 Reco Zrt.
- 6.4.16 Sam Dong Co, Ltd.
- 6.4.17 Sumitomo Electric Industries, Ltd.
- 6.4.18 Superior Essex Inc.
- 6.4.19 SWCC Corporation
- 6.4.20 Taihan Cable & Solution Co., Ltd.
- 6.4.21 Tongling Jingda Special Magnet Wire Co., Ltd
- 6.4.22 Tre Tau Engineering s.r.l
- 6.4.23 Xinzhu Cable Group
- 6.4.24 ZTT
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment
- 7.2 Advancements in Magnet Wire
- 7.3 Demand in High-Voltage Systems


