|
시장보고서
상품코드
2125353
미국의 주거용 난방 장비 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United States Residential Heating Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
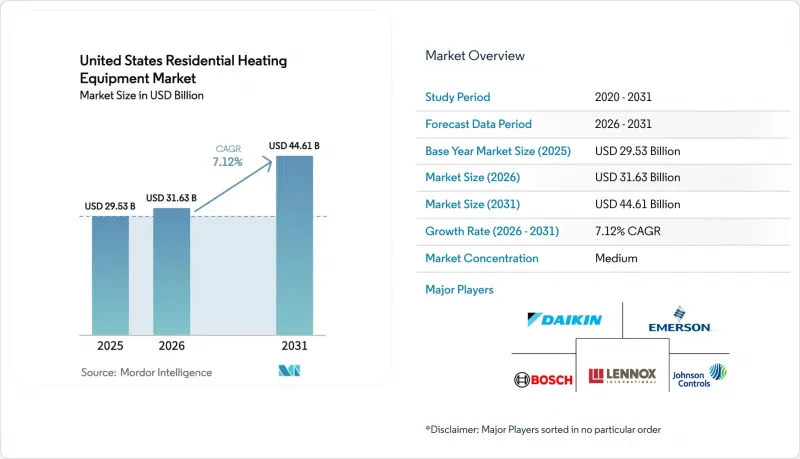
에 의하면, 2026년 미국 주거용 난방 장비 시장 규모는 316억 3,000만 달러로 추정되고 2025년 295억 3,000만 달러에서 확대해, 2031년에는 446억 1,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 7.12%를 기록하며 성장할 것으로 전망됩니다.
본 보고서는 제품 유형별(가스 난로, 전기 난로, 보일러 등), 기술별(응축식, 비응축식, 가변속 인버터, 스마트 커넥티드), 최종 사용자별(단독주택, 공동주택 등), 유통 채널별(교체·애프터마켓, 신축 OEM)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
미국의 주거용 난방 장비 시장 동향 및 인사이트
고효율 히트펌프에 대한 연방 세액 공제 및 IRA 리베이트
세제 혜택에 따라 현재 프로젝트 비용의 30%(상한 2,000달러)가 지원 대상이며, 저-중소득 가구는 추가 리베이트를 활용하여 설치 비용의 50%를 초과하는 지원을 받을 수 있습니다. ENERGY STAR ‘Most Efficient’ 인증을 의무화하는 2025년 새로운 적격성 규정에 따라 제조업체들은 더 고성능의 압축기 및 인버터 제어 기술을 채택해야 하며, 이로 인해 제품 리프레시 주기가 단축되고 있습니다. 갱신된 IRS 인증 제조업체 목록에는 캐리어, 레녹스, 리임이 등재되어 있어, 규격을 준수하는 모델의 주류 시장 유통이 보장되고 있습니다.
주 차원의 전기화 관련 건축 기준
캘리포니아주의 ‘2025년 건축물 에너지 효율 기준’에 따르면, 2026년 1월 이후 신축 주택에 히트펌프 설치를 건설업자에게 의무화하고 있으며, 워싱턴주, 오리건주, 뉴욕주에서는 이미 이 기준을 참고하고 있습니다. 2024년판 IECC의 선택적 부록에는 각 주가 개조 허가에 ‘전기 대응’ 요건을 추가할 수 있도록 하는 기성 문구가 포함되어 있어, 정책의 적용 범위를 교체 시장까지 확대되고 있습니다.
높은 초기 투자 비용과 기존 가스 난방기와의 비교
히트 펌프의 설치 가격은 8,000-1만 5,000달러인 반면, 가스 난방기는 4,000-8,000달러이며, 이 가격 차이는 세액 공제를 적용한 후에도 해소되지 않습니다. 패널 교체 및 냉매 처리에 드는 추가 비용으로 인해, 가스 가격이 낮은 지역에서는 투자 회수 기간이 길어집니다. 미국 에너지 효율 경제 협의회(ACEEE)는 난방 일수가 7,000일 미만인 지역에서는 비용 대비 효과가 현저히 향상된다고 지적하고 있습니다.
부문 분석
2025년 시점에서 가스식 난방 기기는 미국 주거용 난방 장비 시장의 44.35%를 차지했으나, 한랭지용 히트펌프는 연평균 성장률(CAGR) 10.78%로 성장하고 있어 그 시장 점유율을 빠르게 잠식할 우려가 있습니다. 미국 주거용 난방 장비 시장에서 한랭지용 히트펌프 시장 규모는 에너지부(DOE)의 노력으로 영하의 기온에서도 실용성이 입증됨에 따라 대폭 확대될 것으로 예측됩니다. 히트 펌프와 보조 가스 스테이지를 결합한 하이브리드 시스템은 완전한 전기화에 신중한 주택 소유자들에게 전환 경로가 되어, 극한 한파가 닥쳤을 때도 쾌적한 환경을 유지해 줍니다.
히트펌프식 온수기에 대한 최대 2,000달러의 연방 세액 공제로 인해 난방과 온수 공급을 결합한 개조 공사가 촉진되고 있으며, 시공업체의 평균 수주액이 상승하고 있습니다. 재생에너지가 풍부한 주에서는 시간대별 전기 요금이 계절별 가스 가격보다 낮기 때문에 전기식 난방기는 여전히 입지를 유지하고 있지만, 기존의 온수 난방 시장을 제외하면 보일러 시장 점유율은 축소되는 추세입니다. 240V 덕트식과 120V 덕트리스 방식을 모두 공급할 수 있는 제조업체는 재고 관리 효율화를 꾀하는 유통업체의 지지를 받아 더욱 견고한 입지를 다지고 있습니다.
2025년 시점에서도 비응축형 플랫폼은 미국 주거용 난방 장비 시장 점유율의 56.05%를 차지했으나, 연방 정부의 최소 효율 기준 개정이 임박함에 따라 주문은 응축형 및 인버터식 유닛으로 이동하고 있습니다. 가변속 압축기는 연평균 성장률(CAGR) 12.15%로 확대되고 있으며, 부하 추종 운전을 가능하게 함으로써 사이클 손실을 줄이고, 특정 ISO 관할 구역에서 연간 50-100달러 상당 수요 반응 보상을 획득할 수 있게 해줍니다.
전력 회사가 전력망에 부하가 걸릴 때 2시간 동안 온도를 낮추는 것을 허용한 가구에 요금 할인을 제공함에 따라, 미국 주거용 난방 장비 시장의 스마트 커넥티드 시스템 시장 규모는 가속화될 전망입니다. A2L 규정을 준수함에 따라 멀티 센서를 통한 누출 감지 기능을 통합한 재설계가 진행되고 있으며, 한편 클라우드 분석을 통해 예측 유지보수 알림이 제공됨으로써 서비스 계약업체의 출장 횟수가 감소할 것입니다. 이러한 과도기에는 회수 장치 및 교육 모듈을 포함하여 냉매 안전성을 확보한 완벽한 생태계를 인증할 수 있는 OEM이 유리한 입지를 차지할 것입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the US residential heating equipment market size in 2026 is estimated at USD 31.63 billion, growing from 2025 value of USD 29.53 billion with 2031 projections showing USD 44.61 billion, growing at 7.12% CAGR over 2026-2031.
This report is Segmented by Product Type (Gas Furnaces, Electric Furnaces, Boilers, and More), Technology (Condensing, Non-Condensing, Variable-Speed Inverter, Smart Connected), End-User (Single-Family Detached Homes, Multi-Family Residential, and More), Distribution Channel (Replacement/Aftermarket, New Construction OEM). The Market Forecasts are Provided in Terms of Value (USD).
United States Residential Heating Equipment Market Trends and Insights
Federal Tax Credits and IRA Rebates for High-Efficiency Heat Pumps
Tax incentives now cover 30% of project costs up to USD 2,000, and low-to-moderate income households can tap additional rebates that raise total support beyond 50% of installed cost. New 2025 eligibility rules that require ENERGY STAR Most Efficient certification push manufacturers toward higher-performance compressors and inverter logic, shortening product-refresh cycles. An updated IRS qualified-manufacturer list features Carrier, Lennox, and Rheem, ensuring mainstream distribution of compliant models.
State-Level Electrification Building Codes
California's 2025 Building Energy Efficiency Standards obligate builders to install heat pumps in new homes beginning January 2026, a template Washington, Oregon, and New York are already adapting. Optional appendices in the 2024 IECC provide ready-made language that allows states to layer electric-ready requirements onto renovation permits, extending policy reach to the replacement market.
High Upfront Capital Cost Versus Baseline Gas Furnaces
Installed heat-pump prices run USD 8,000-15,000 compared with USD 4,000-8,000 for gas furnaces, and the gap endures even after credits. Additional expenses for panel upgrades and refrigerant handling prolong payback in low-gas-price regions. The American Council for an Energy-Efficient Economy notes that cost-effectiveness improves markedly in zones with fewer than 7,000 heating degree days.
Other drivers and restraints analyzed in the detailed report include:
- Cold-Climate Heat-Pump Technology Advances
- Aging Housing-Stock Replacement Cycle
- Skilled Labor Shortage for Heat-Pump Installation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Gas furnaces accounted for 44.35% of the US Residential Heating Equipment market in 2025, yet cold-climate heat pumps are running an 10.78% CAGR that threatens to erode that share quickly. The US Residential Heating Equipment market size for cold-climate heat pumps is projected to widen substantially as the Department of Energy challenge proves viability at sub-zero temperatures. Hybrid systems that pair a heat pump with a secondary gas stage offer a migration path for homeowners wary of full electrification, and they preserve comfort during polar vortex events.
Federal credits of up to USD 2,000 on heat-pump water heaters are encouraging bundled space-and-water-heating retrofits, lifting average order value for contractors. Electric furnaces hold ground in renewable-rich states where time-of-use electricity rates track below seasonal gas pricing, while boilers see attrition except in legacy hydronic markets. Manufacturers that can supply both 240 V ducted and 120 V ductless formats occupy a stronger position with distributors eager to streamline stocking decisions.
Non-condensing platforms still represented 56.05% of the US Residential Heating Equipment market share in 2025, but impending federal minimum-efficiency updates skew orders toward condensing and inverter units. Variable-speed compressors are climbing at a 12.15% CAGR, enabling load-following operation that cuts cycling losses and unlocks demand-response payments worth USD 50-100 per year in select ISO territories.
The US Residential Heating Equipment market size for smart connected systems is set to accelerate as utilities offer bill credits to households that allow 2-hour temperature setbacks during grid stress. A2L compliance drives redesigns that integrate multi-sensor leak detection, while cloud analytics deliver predictive maintenance alerts that reduce truck rolls for service contractors. The transition phase favors OEMs that can certify a complete refrigerant-safe ecosystem, including recovery equipment and training modules.
Complete Report Scope:
- By Product Type
- Gas Furnaces
- Electric Furnaces
- Boilers
- Air and Water Heaters
- Heat Pumps
- Hybrid Systems
- Other Types
- By Technology
- Condensing
- Non-Condensing
- Variable-Speed Inverter
- Smart Connected
- By End-User
- Single-Family Detached Homes
- Multi-Family Residential
- Manufactured Housing
- Other Ed-users
- By Distribution Channel
- Replacement / Aftermarket
- New Construction (OEM)
List of Companies Covered in this Report:
- Carrier Global Corporation
- Trane Technologies plc
- Lennox International Inc.
- Daikin Industries Ltd.
- Rheem Manufacturing Company
- Johnson Controls International plc
- Bosch Thermotechnology Corp.
- Bradford White Corporation
- Burnham Holdings Inc.
- Mitsubishi Electric Trane HVAC US LLC
- American Standard Heating and Air Conditioning
- Emerson Electric Co.
- Honeywell International Inc. (Smart Controls)
- Nortek Global HVAC
- Navien Inc.
- Viessmann Manufacturing Co. (U.S.) Inc.
- Robert Bosch LLC
- WaterFurnace International Inc.
- LG Electronics USA - HVAC
- Panasonic USA - Heating and Cooling
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Federal tax credits and IRA rebates for high-efficiency heat pumps
- 4.2.2 State-level electrification building codes
- 4.2.3 Resale-value premium for ENERGY STAR-certified systems
- 4.2.4 Cold-climate heat-pump technology advances
- 4.2.5 Smart-thermostat enabled demand-response revenues
- 4.2.6 Aging housing-stock replacement cycle
- 4.3 Market Restraints
- 4.3.1 High upfront capital cost vs. baseline gas furnaces
- 4.3.2 Natural-gas price volatility complicating pay-back
- 4.3.3 Electric-grid constraints during extreme cold events
- 4.3.4 Skilled labor shortage for heat-pump installation
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Macro Economic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Product Type
- 5.1.1 Gas Furnaces
- 5.1.2 Electric Furnaces
- 5.1.3 Boilers
- 5.1.4 Air and Water Heaters
- 5.1.5 Heat Pumps
- 5.1.6 Hybrid Systems
- 5.1.7 Other Types
- 5.2 By Technology
- 5.2.1 Condensing
- 5.2.2 Non-Condensing
- 5.2.3 Variable-Speed Inverter
- 5.2.4 Smart Connected
- 5.3 By End-User
- 5.3.1 Single-Family Detached Homes
- 5.3.2 Multi-Family Residential
- 5.3.3 Manufactured Housing
- 5.3.4 Other Ed-users
- 5.4 By Distribution Channel
- 5.4.1 Replacement / Aftermarket
- 5.4.2 New Construction (OEM)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Carrier Global Corporation
- 6.4.2 Trane Technologies plc
- 6.4.3 Lennox International Inc.
- 6.4.4 Daikin Industries Ltd.
- 6.4.5 Rheem Manufacturing Company
- 6.4.6 Johnson Controls International plc
- 6.4.7 Bosch Thermotechnology Corp.
- 6.4.8 Bradford White Corporation
- 6.4.9 Burnham Holdings Inc.
- 6.4.10 Mitsubishi Electric Trane HVAC US LLC
- 6.4.11 American Standard Heating and Air Conditioning
- 6.4.12 Emerson Electric Co.
- 6.4.13 Honeywell International Inc. (Smart Controls)
- 6.4.14 Nortek Global HVAC
- 6.4.15 Navien Inc.
- 6.4.16 Viessmann Manufacturing Co. (U.S.) Inc.
- 6.4.17 Robert Bosch LLC
- 6.4.18 WaterFurnace International Inc.
- 6.4.19 LG Electronics USA - HVAC
- 6.4.20 Panasonic USA - Heating and Cooling
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment