|
시장보고서
상품코드
2125367
유량 제어 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Flow Control - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 유량 제어 시장 규모는 2025년 62억 1,000만 달러로 평가되었고, 2026년에는 68억 5,000만 달러로 추정되고, 2026-2031년 CAGR 10.28%로 성장을 지속할 전망이며, 2031년에는 111억 7,000만 달러에 이를 것으로 예측됩니다.

본 보고서는 제품 유형별(밸브, 펌프 등), 최종 사용자 산업별(석유 및 가스, 상하수도, 발전 등), 기능별(유량 모니터링, 유량 조절 등), 기술별(공압, 유압 등), 지역별(북미, 남미, 유럽, 아시아태평양, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 금액(달러)으로 제시되어 있습니다.
세계의 유량 제어 시장 동향 및 인사이트
기존 유량 제어 인프라의 디지털화
각 제조업체들은 공압식 및 유압식 루프를 플랜트의 SCADA 시스템에 원활하게 통합되는 다수의 센서가 탑재된 전기식 어셈블리로 대체하고 있습니다. AI와 결합된 실시간 원격 측정 기술을 통해 예기치 않은 가동 중단 시간을 최대 30%까지 줄이고, 특히 등급 수율이 유량 정확도에 좌우되는 화학 및 석유화학 공정에서 보다 엄격한 공정 허용 오차를 확보합니다. 이 개조 모델은 전면 교체에 비해 자본 지출(CAPEX)을 절감할 수 있어 성숙한 플랜트에 매력적이며, 한편 클라우드 대시보드를 통해 경영진은 에너지 및 유지보수 지표를 즉시 파악할 수 있습니다.
신흥국에서의 LNG 터미널 투자 급증
베트남, 인도, 인도네시아에서는 -160°C 이상의 온도에서 작동 가능한 극저온 대응 밸브, 액추에이터, 유량계가 필요한 신규 터미널이 건설되고 있습니다. 베트남만 해도 2030년까지 총액 120억 달러 규모의 5개 신규 시설을 계획하고 있습니다. 각 터미널에는 안전 무결성 수준(SIL)을 충족하기 위해 이중화된 디지털 차단 루프가 통합되어 있어, 극저온용 금속 소재와 SIL-3 대응 전자 기기를 모두 인증할 수 있는 공급업체에게는 수익성이 높은 틈새 시장이 열리고 있습니다.
특수 합금 공급망의 변동성
니켈 기반 초합금 가격이 40% 이상 변동한 결과, 가혹한 사용 조건에 적합한 밸브 본체의 리드타임이 40주 이상으로 늘어나는 사태가 발생하고 있습니다. 엔지니어링 팀은 재인증 없이는 금속을 쉽게 대체할 수 없기 때문에 구매자는 종종 이중 조달에 의존하거나 재고 완충량을 유지하게 되는데, 이로 인해 운전 자본이 증가할 가능성이 있습니다.
부문 분석
2025년 현재, 기존 밸브는 유량 제어 장비 시장에서 32.74%의 시장 점유율을 차지했으며, 연평균 성장률(CAGR) 13.16%로 확대되고 있습니다. 펌프와 액추에이터는 대량의 유체를 이동시키는 데 여전히 필수적이지만, 예측 알고리즘을 통해 유지보수 비용 절감 효과가 입증됨에 따라 그 성장률은 지능형 밸브 부문의 성장률보다 낮습니다. 유량계는 정확한 배출량 보고를 요구하는 규정 준수 주도형 수요의 혜택을 받고 있습니다. 전반적으로, 업그레이드된 스마트 어셈블리는 진단 플랫폼의 도입 기반을 확대하고 있으며, 현재 공급업체 총 매출의 20% 이상을 차지하는 애프터마켓 수익을 뒷받침하고 있습니다.
이러한 개조 추세는 하이브리드 솔루션을 뒷받침하고 있습니다. 이 솔루션은 기존 밸브 본체에 디지털 포지셔너를 장착함으로써 생산을 중단하지 않고도 비용 효율적인 분석으로 나아가는 길을 열어줍니다. 모듈식 전자 플랫폼을 갖춘 공급업체는 HART, Modbus, OPC UA 등과 같은 맞춤형 신호 프로토콜을 제공하며, 이는 기존 플랜트 내의 다중 공급업체 아키텍처를 지원합니다. 또한 공급업체는 ISO 5167 추적성 기준을 충족하는 교정 곡선을 미리 탑재하여 규제 감사의 신속화를 도모하고 있습니다.
석유 및 가스 기업은 LNG 확대 및 메탄 누출 감축 노력을 배경으로, 2025년 유량 제어 장비 시장에서 28.12%의 점유율을 유지했습니다. 한편, 세포 및 유전자 치료 라인이 확대됨에 따라 제약 및 생명공학 분야가 연평균 성장률(CAGR) 11.3%로 성장을 주도하고 있습니다. 물 및 폐수 처리 사업자는 순환형 경제 프로젝트의 뒷받침을 받아 그 뒤를 바짝 쫓고 있습니다. 발전 사업자는 계통의 관성을 유지하면서 변동하는 재생에너지 공급을 관리하기 위해 유량 회로를 개조하고 있으며, 이에 따라 응답성이 빠른 제어 밸브에 대한 수요가 증가하고 있습니다. 화학 기업들은 재구성 가능한 유량 스키드가 필요한 모듈형 파일럿 플랜트로 전환하고 있으며, 위생적인 식품 및 음료 가공업체들은 자동 CIP(정지 세척) 사이클에 대응하는 위생용 다이어프램 밸브를 구매하고 있습니다.
생명과학 분야의 급속한 성장은 검증된 문서에 좌우됩니다. 각 스키드에 전자 기록을 동봉하는 공급업체는 고객의 인증 취득에 따른 부담을 경감시키고 있습니다. 한편, 기존 에너지 기업들은 누출을 정량적으로 줄일 수 있는 안전상 중요한 설비에 투자를 집중하고 있으며, 장비 선정을 배출권 전략과 연계하고 있습니다.
지역별 분석
아시아태평양의 41.55%라는 점유율은 중국의 반도체 공장에서 인도의 바이오 제조 단지에 이르기까지, 타 지역을 압도하는 프로젝트 규모를 보여줍니다. 정부의 우대 조치, 낮은 인건비, 신속한 인허가 절차로 인해 자산의 수명 주기가 단축되고 있습니다. 디지털 개조 프로그램은 그린필드 건설 수준에는 미치지 못하지만, 다국적 기업들이 지역을 초월한 공통 OT(운영 기술) 기준을 요구함에 따라 그 기세가 커지고 있습니다.
북미의 구매 기업들은 연방 정부의 중요 인프라 관련 지침에 힘입어, 안전 계장 노드의 사이버 보안 강화를 위한 업그레이드에 예산을 배정하고 있습니다. 마찬가지로, 미국의 LNG 수출 확대도 극저온용 밸브 수요를 뒷받침하고 있습니다. 유럽의 최종 사용자들은 산업 배출 지침 개정에 대응하기 위해 누출 감지 및 복구 장비에 설비 투자를 하고 있으며, 지방 자치단체의 유틸리티체는 2030년 물 재사용 목표를 달성하기 위해 수년에 걸친 업그레이드를 시작하고 있습니다.
걸프협력회의(GCC) 회원국에서는 루프식 냉수를 순환시키는 IIoT 기반의 스마트 지역 냉방 네트워크 도입이 진행 중이며, 이는 내식성 버터플라이 밸브의 판매를 견인하고 있습니다. 남미에서는 광업 생산량 증가에 따라 슬러리용 밸브 소비가 확대되고 있지만, 거시경제의 변동이 설비 투자 주기를 저해하고 있습니다. 아프리카의 수처리 시설 구축은 초기 단계에 있으며, 개발은행은 현장 방문을 최소화하기 위해 하드웨어에 원격 진단 기능을 탑재할 것을 조건으로 하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the flow control market size is expected to grow from USD 6.21 billion in 2025 to USD 6.85 billion in 2026 and is forecast to reach USD 11.17 billion by 2031 at 10.28% CAGR over 2026-2031.
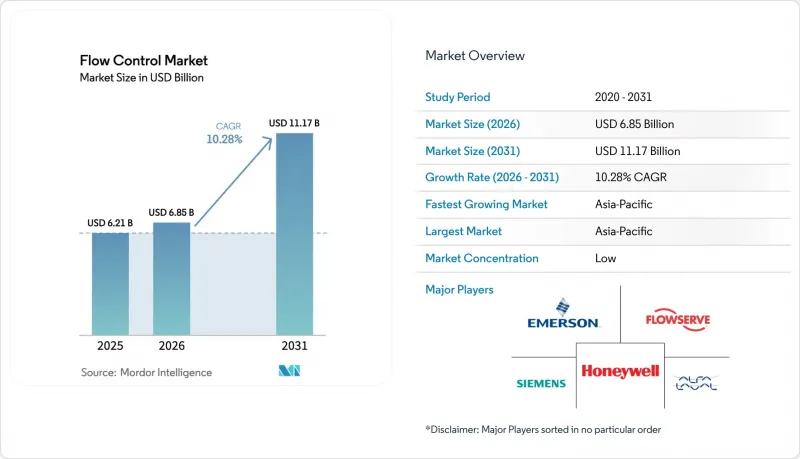
This report is Segmented by Product Type (Valves, Pumps, and More), End-User Industry (Oil and Gas, Water and Wastewater, Power Generation, and More), Function (Flow Monitoring, Flow Regulation, and More), Technology (Pneumatic, Hydraulic, and More), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Flow Control Market Trends and Insights
Digitization of Legacy Flow Control Infrastructure
Manufacturers are replacing pneumatic or hydraulic loops with sensor-rich electric assemblies that integrate seamlessly into plant SCADA systems. Real-time telemetry, combined with AI, reduces unscheduled downtime by as much as 30% and ensures tighter process tolerances, especially in chemical and petrochemical processes where grade yields hinge on flow accuracy. The retrofit model appeals to mature plants because it lowers capex versus full replacement, while cloud dashboards give executives immediate visibility into energy and maintenance metrics.
Surge in LNG Terminal Investments Across Emerging Economies
Vietnam, India, and Indonesia are adding greenfield terminals that require cryogenic-ready valves, actuators, and flow meters capable of operating at temperatures of>= -160 °C. Vietnam alone plans five new facilities worth USD 12 billion by 2030. Each terminal integrates redundant digital shutoff loops to meet safety integrity levels, opening premium niches for suppliers that can certify both extreme-temperature metallurgy and SIL-3 electronics.
Supply Chain Volatility for Specialty Alloys
Price swings of more than 40% in nickel-based superalloys have resulted in extended lead times of over 40 weeks for severe-service valve bodies. Engineering teams cannot readily substitute metals without requalification, and buyers often resort to dual sourcing or maintaining inventory buffers, which can increase working capital.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Uptake of Modular Chemical Plants
- Sustainability Mandates Driving Water Reuse Systems
- Cybersecurity Vulnerabilities in IIoT-Enabled Devices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Traditional valves held a 32.74% market share of the flow control equipment market in 2025 and are advancing at a 13.16% CAGR. Pumps and actuators remain essential for bulk fluid movement; however, their growth trails that of the intelligent valve segment, as predictive algorithms have proven to reduce maintenance outlays. Flow meters benefit from compliance-driven demand for accurate discharge reporting. Collectively, upgraded smart assemblies are expanding the installed base for diagnostics platforms, supporting aftermarket revenues that now account for more than 20% of vendor totals.
The retrofit wave favors hybrid solutions, where digital positioners are bolted onto legacy bodies, creating cost-effective pathways to analytics without halting production. Vendors with modular electronics platforms offer tailored signal protocols, including HART, Modbus, and OPC UA, which support multi-vendor architectures within brownfield plants. Suppliers also preload calibration curves that meet ISO 5167 traceability standards, thereby accelerating regulatory audits.
Oil and gas companies maintained a 28.12% market share of flow control equipment in 2025, driven by LNG expansion and methane leak reduction initiatives. Yet pharmaceuticals and biotechnology lead growth at 11.3% CAGR as cell and gene therapy lines proliferate. Water and wastewater utilities sit close behind, catalyzed by circular-economy projects. Power generators retrofit flow circuits to manage varying renewable inputs while maintaining grid inertia, which boosts demand for fast-response control valves. Chemical firms are shifting toward modular pilot plants that require reconfigurable flow skids, and hygienic food and beverage processors are buying sanitary diaphragm valves compatible with automated clean-in-place cycles.
The life-science boom hinges on validated documentation; suppliers that bundle electronic records with each skid reduce customer qualification effort. Meanwhile, conventional energy firms concentrate their spending on safety-critical units that deliver quantifiable reductions in leaks, tying equipment choices to emissions-credit strategies.
Complete Report Scope:
- By Product Type
- Valves
- Pumps
- Actuators
- Flow Meters
- By End-user Industry
- Oil and Gas
- Water and Wastewater
- Power Generation
- Chemical and Petrochemical
- Pharmaceuticals and Biotechnology
- Food and Beverage
- By Function
- Flow Monitoring
- Flow Regulation
- Flow Shutoff
- Flow Diversion
- By Technology
- Pneumatic
- Hydraulic
- Electric
- Smart/Digital
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Singapore
- Australia
- Malaysia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia Pacific's 41.55% share illustrates unmatched project volume ranging from Chinese semiconductor plants to Indian biomanufacturing parks. Government incentives, low labor costs, and rapid permitting compress asset lifecycles. Digital retrofit programs trail greenfield build-outs but are gaining traction as multinationals demand common OT standards across regions.
North American buyers allocate budgets for cyber-secure upgrades to safety-instrumented nodes, encouraged by federal critical infrastructure directives. U.S. LNG export expansion likewise sustains cryogenic valve demand. European end users earmark capex for leak-detection-and-repair equipment to meet Industrial Emissions Directive revisions, and municipal utilities have begun multi-year upgrades to achieve 2030 water reuse targets.
Gulf Cooperation Council members are integrating IIoT-based smart district cooling networks that run on looped chilled water, driving sales of corrosion-resistant butterfly valves. South American mining output boosts slurry-duty valve consumption, but macroeconomic volatility hinders capital cycles. African water-treatment build-outs are in their early stages; development banks stipulate that hardware include remote diagnostics to minimize site visits.
- Emerson Electric Co.
- Flowserve Corporation
- Siemens AG
- Honeywell International Inc.
- Alfa Laval AB
- Schlumberger Limited
- Christian Burkert GmbH & Co. KG
- Spirax-Sarco Engineering Plc
- Rotork Plc
- KSB SE & Co. KGaA
- Crane Company
- Swagelok Company
- Metso Oyj
- SAMSON AG
- IMI Plc
- Parker Hannifin Corporation
- Badger Meter Inc.
- SMC Corporation
- Festo SE & Co. KG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Digitization of legacy flow control infrastructure
- 4.2.2 Surge in LNG terminal investments across emerging economies
- 4.2.3 Rapid uptake of modular chemical plants
- 4.2.4 Sustainability mandates driving water reuse systems
- 4.2.5 Tightening fugitive-emission regulations in Europe and the United States
- 4.2.6 Micro-precision flow solutions for cell and gene therapy manufacturing
- 4.3 Market Restraints
- 4.3.1 Supply chain volatility for specialty alloys
- 4.3.2 Cybersecurity vulnerabilities in IIoT-enabled devices
- 4.3.3 Capital expenditure cuts in upstream oil downstream of 2023 price shocks
- 4.3.4 Fragmented aftermarket service landscape in developing regions
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Macro-economic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Valves
- 5.1.2 Pumps
- 5.1.3 Actuators
- 5.1.4 Flow Meters
- 5.2 By End-user Industry
- 5.2.1 Oil and Gas
- 5.2.2 Water and Wastewater
- 5.2.3 Power Generation
- 5.2.4 Chemical and Petrochemical
- 5.2.5 Pharmaceuticals and Biotechnology
- 5.2.6 Food and Beverage
- 5.3 By Function
- 5.3.1 Flow Monitoring
- 5.3.2 Flow Regulation
- 5.3.3 Flow Shutoff
- 5.3.4 Flow Diversion
- 5.4 By Technology
- 5.4.1 Pneumatic
- 5.4.2 Hydraulic
- 5.4.3 Electric
- 5.4.4 Smart/Digital
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 Singapore
- 5.5.4.5 Australia
- 5.5.4.6 Malaysia
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Emerson Electric Co.
- 6.4.2 Flowserve Corporation
- 6.4.3 Siemens AG
- 6.4.4 Honeywell International Inc.
- 6.4.5 Alfa Laval AB
- 6.4.6 Schlumberger Limited
- 6.4.7 Christian Burkert GmbH & Co. KG
- 6.4.8 Spirax-Sarco Engineering Plc
- 6.4.9 Rotork Plc
- 6.4.10 KSB SE & Co. KGaA
- 6.4.11 Crane Company
- 6.4.12 Swagelok Company
- 6.4.13 Metso Oyj
- 6.4.14 SAMSON AG
- 6.4.15 IMI Plc
- 6.4.16 Parker Hannifin Corporation
- 6.4.17 Badger Meter Inc.
- 6.4.18 SMC Corporation
- 6.4.19 Festo SE & Co. KG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment