

|
시장보고서
상품코드
2125435
태국의 포장 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Thailand Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
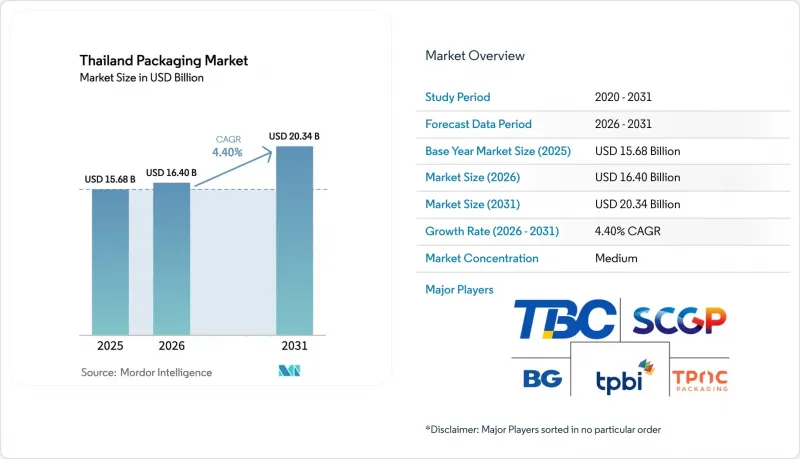
에 의하면, 태국의 포장 시장 규모는 2025년에 156억 8,000만 달러로 평가되었고, 2026년 164억 달러에서 2031년까지 203억 4,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.4%를 나타낼 전망입니다.
본 보고서는 소재 유형별(종이 및 판지, 플라스틱, 금속, 용기용 유리), 제품 유형별(종이 및 판지 제품, 플라스틱 제품, 금속 제품, 용기용 유리 제품), 포장 형태별(경질, 연질), 최종 사용자 산업별(식품, 음료, 의약품 및 의료, 기타) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
태국의 포장 시장 동향 및 인사이트
식품 및 음료 생산량 증가
태국은 2024년에 328억 달러 상당의 식품을 수출했습니다. 이러한 실적에 힘입어 포장 수요가 증가하고 있습니다. 이는 상온 보관이 가능한 수출품의 경우, 장시간 운송 중에도 풍미를 유지하기 위해 다층 배리어 필름이 필요하기 때문입니다. 2025년에는 국내 식품 공장의 설비 가동률이 78%로 상승하면서 골판지 운송 상자, 스탠드업 파우치, 무균 카톤에 대한 주문이 지속되었습니다. 관광 산업의 회복에 따라 2025년에는 호텔, 레스토랑, 기관계 바이어들의 지출이 354억 달러에 달했으며, 전자레인지용 트레이를 사용한 즉석 식사 키트에 대한 국내 수요가 강화되었습니다. 수출과 국내 시장 모두의 성장 동력에 힘입어, 가공업체들은 판매량 감소 없이 수지 원가 변동을 가격에 전가할 수 있게 되었습니다. 그 결과, 식품 처리량 증가로 인해 2026년부터 2031년까지 태국 포장 시장의 연평균 성장률(CAGR)이 1.2포인트 상승할 것으로 예측됩니다.
전자상거래 및 소포 처리량 증가
택배 업계의 선두주자인 켈리 익스프레스는 2025년에 하루 평균 700만-800만 개의 소포를 처리했으며, 이는 2022년 이후 처리량이 두 자릿수 성장세를 보이고 있음을 반영합니다. 각 소포에는 폴리에틸렌 우편 봉투나 골판지 상자가 사용되며, 당일 배송 서비스로의 전환에 따라 포장부터 출하까지의 주기를 단축할 수 있는 성형된 경량 솔루션이 선호되고 있습니다. 2025년 국내 총 상품 가치는 1,000억 바트(29억 달러)에 달했으며, 패션 및 헬스&뷰티 관련 상품이 가장 높은 재주문률을 기록했습니다. 각 택배사는 기업의 기후 변화 대응 공약을 이행하기 위해 재활용 가능하거나 생분해성 포장재 사용을 요구하고 있으며, 이에 따라 종이 재질의 기포 봉투와 퇴비화 가능한 에어필로우에 대한 수요가 증가하고 있습니다. 방콕의 라스트 마일 네트워크가 포화 상태에 이르면서 지방 허브로 확대됨에 따라, 2028년까지 전자상거래는 시장 성장에 약 1퍼센트 포인트의 기여를 계속할 것으로 예측됩니다.
일회용 플라스틱 금지 및 환경세
2025년 1월 1일부터 옥소 분해성 비닐봉지, 폴리스티렌 식품 용기, 플라스틱 빨대의 전국적인 사용 금지가 시행되어, 위반 건당 최대 100,000바트(2,857달러)의 벌금이 부과됩니다. 소매업체들은 비용이 20-40% 더 비싼 종이 빨대나 사탕수수 찌꺼기 용기로 전환할 수밖에 없게 되어, 외식 산업의 이익률을 압박하고 있습니다. 이 금지 조치로 인해 연간 약 5만 메트르톤의 폴리스티렌 수요가 사라지게 되어, 압출 성형 제조업체들은 생산 라인을 중단하거나 폴리프로필렌 생산으로 전환할 수밖에 없는 상황에 처해 있습니다. 버진 수지에 대해 1Kg당 2-5 태국 바트(0.06-0.14 달러)의 환경세가 추가로 부과될 예정이어서, 비용 부담이 더욱 심화될 가능성이 있습니다. 이러한 요인들이 복합적으로 작용하여, 단기적으로는 태국 포장 시장의 연평균 성장률(CAGR)을 0.6포인트 하락시킬 것으로 전망됩니다.
부문 분석
2025년에는 플라스틱이 시장 가치의 42.18%를 차지했으나, 재생 PET는 연평균 성장률(CAGR) 4.92%로 급성장하고 있으며, 세계 브랜드들이 사용 후 수지의 25%-50% 사용이라는 목표를 추구하는 가운데, 순환형 원료로의 전환이 진행되고 있음을 여실히 보여주고 있습니다. 태국 포장 시장에서 rPET 병만 시장 규모는 버진 수지 병보다 빠른 속도로 성장할 것으로 예측됩니다. 이는 Indorama Ventures사가 2025년 말에 5만 메트르톤 규모의 식품 등급 생산 라인을 가동하기 때문입니다. 폴리프로필렌과 고밀도 폴리에틸렌은 4%대 초반의 성장률을 보이고 있지만, 환경세로 인한 역풍에 직면해 있는 반면, 폴리스티렌 수요는 금지 조치 이후 급감했습니다.
종이 및 판지는 급증하는 전자상거래용 골판지 상자 주문에 대응하기 위해 국내 제지 공장의 생산량이 5.2% 증가한 데 힘입어 2025년 시장 가치의 약 28%를 차지했습니다. 금속은 18%를 차지했으며, 이러한 성장은 타이 베버리지 캔(Thai Beverage Can)과 볼 코퍼레이션(Ball Corporation)의 경량 알루미늄 기술 투자와 밀접한 관련이 있습니다. 유리는 12%로 그 뒤를 이었으며, BG 컨테이너 글래스(BG Container Glass)는 용해로 개량을 통한 효율성 향상에 기대를 걸고 있지만, 더 가벼운 PET 병에 시장 점유율을 빼앗기고 있습니다. 전반적으로 이러한 소재 동향은 지속가능성 프리미엄과 물류 경제성이 태국의 포장 시장을 어떻게 재편하고 있는지를 보여줍니다.
2025년 매출에서 봉지가 차지하는 비중은 28.24%였으나, 소비자들이 재밀봉이 가능하고 자립형 포장을 선호함에 따라 파우치는 5.01%로 더 빠른 성장률을 보이고 있습니다. 태국 포장 시장에서 파우치의 점유율은 지퍼나 주입구와 같은 기능 덕분에 범용 봉투 제품 라인보다 높은 12%-15%의 컨버터 마진(가공 이익률)의 혜택을 받고 있습니다. 필름 및 랩은 동부 경제 회랑의 수출용 팔레트화 및 온실 농업의 확대로 인해 4.7%의 성장률을 보이고 있습니다.
경질 플라스틱으로 만든 병, 용기, 캡은 음료 및 개인 위생 용품 수요에 힘입어 총 연평균 성장률(CAGR) 4.2%로 성장을 지속하고, 있습니다. 테더가 부착된 캡은 개당 0.01-0.02달러의 비용 증가가 발생하지만, 무단 투기를 방지하고 향후 시행될 생산자 책임 회수(EPR) 규정에도 대응하고 있습니다. 골판지 상자, 접이식 판지 상자, 성형 섬유 재질의 테이크아웃용 포장재는 2025년 1월 발효될 스티로폼 사용 금지 조치를 활용하여 외식 산업과의 계약 확보에 성공하며, 종이 제품 시장을 주도하고 있습니다. 이러한 제품 동향은 태국 포장 시장에서 부가가치가 높은 형태로의 전환이 지속적으로 진행되고 있음을 보여줍니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the Thailand packaging market size was valued at USD 15.68 billion in 2025 and is estimated to grow from USD 16.4 billion in 2026 to reach USD 20.34 billion by 2031, at a CAGR of 4.4% during the forecast period (2026-2031).
This report is Segmented by Material Type (Paper and Paperboard, Plastic, Metal, and Container Glass), Product Type (Paper and Paperboard Product, Plastic Product, Metal Product, and Container Glass Product), Packaging Format (Rigid, and Flexible), End-User Industry (Food, Beverage, Pharmaceutical and Medical, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Thailand Packaging Market Trends and Insights
Rising Food and Beverage Output
Thailand shipped USD 32.8 billion worth of food products in 2024, a performance that lifts packaging demand because shelf-stable exports need multilayer barrier films that preserve flavour during long transit. Capacity-utilization in domestic food factories climbed to 78% in 2025, sustaining orders for corrugated shippers, stand-up pouches, and aseptic cartons. Hotels, restaurants, and institutional buyers spent USD 35.4 billion in 2025 as tourism rebounded, strengthening local pull for ready-to-eat meal kits that rely on microwaveable trays. The dual export-domestic engine allows converters to transfer resin cost swings into pricing without volume loss. Consequently, rising food throughput is expected to add 1.2 percentage points to the Thailand packaging market CAGR between 2026 and 2031.
Growth Of E-Commerce and Parcel Volumes
Courier leader Kerry Express handled 7 million-8 million parcels daily during 2025, reflecting a double-digit volume climb since 2022. Each parcel uses a polyethylene mailer or corrugated box, and the shift toward same-day service favours pre-formed, lightweight solutions that shorten pack-to-ship cycles. National gross-merchandise value touched THB 100 billion (USD 2.9 billion) in 2025, with fashion and health-and-beauty goods recording the highest reorder rates. Parcel carriers now request recyclable or biodegradable mailers to meet corporate climate pledges, spurring demand for paper-based bubble mailers and compostable air pillows. As the last-mile network saturates Bangkok and expands to provincial hubs, e-commerce will continue to contribute about 1 percentage point to market growth through 2028.
Single-Use-Plastic Bans and Eco Taxes
A nationwide prohibition on oxo-degradable bags, polystyrene food boxes, and plastic straws took effect on 1 January 2025, with fines up to THB 100,000 (USD 2,857) per infraction. Retailers pivoted to paper straws and bagasse containers that cost 20%-40% more, squeezing food-service margins. The ban removed roughly 50,000 metric tons of annual polystyrene demand, forcing extruders to idle lines or retool toward polypropylene. Planned eco-tax surcharges of THB 2-THB 5 per kilogram (USD 0.06-USD 0.14) on virgin resin could deepen the cost burden. Combined, these factors shave 0.6 percentage points from the Thailand packaging market CAGR in the near term.
Other drivers and restraints analyzed in the detailed report include:
- Demand For Convenient and Flexible Packs
- Sustainability And Circular-Economy Mandates
- Volatile Petrochemical Resin Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastic captured 42.18% of value in 2025, yet recycled PET is racing ahead at a 4.92% CAGR, underlining the pivot to circular feedstock as global brands chase 25%-50% post-consumer-resin targets. The Thailand packaging market size for rPET bottles alone is projected to grow faster than virgin equivalents because Indorama Ventures commissioned a 50,000 metric-ton food-grade line in late 2025. Polypropylene and high-density polyethylene grow in the low-4% range but face eco-tax headwinds, while polystyrene demand collapsed post-ban.
Paper and paperboard represented about 28% of 2025 value, buoyed by 5.2% output growth at domestic mills that meet surging e-commerce box orders. Metal held 18%, its advance tied to Thai Beverage Can and Ball Corporation investments in lightweight aluminium technology. Glass followed at 12%, with BG Container Glass banking on furnace-upgrade efficiencies but conceding share to lighter PET bottles. Altogether, material dynamics demonstrate how sustainability premiums and logistics economics reshape the Thailand packaging market.
Bags accounted for 28.24% of 2025 revenue, yet pouches grow quicker at 5.01% as consumers favour resealable, shelf-standing formats. The Thailand packaging market share for pouches benefits from 12%-15% converter margins, higher than commodity bag lines, because of zipper and spout features. Films and wraps rise 4.7% thanks to export palletization and greenhouse farming in the Eastern Economic Corridor.
Rigid plastics bottles, jars, and caps collectively post a 4.2% CAGR, aided by beverage and personal-care demand. Tethered caps add USD 0.01-USD 0.02 each yet prevent littering and meet forthcoming EPR rules. Corrugated boxes, folding cartons, and molded-fiber takeaway packs round out paper products, leveraging the January 2025 foam ban to win food-service contracts. The product landscape signals a continuing tilt toward value-added formats within the Thailand packaging market.
Complete Report Scope:
- By Material Type
- Paper and Paperboard
- Plastic
- Polypropylene (PP)
- HDPE and LDPE
- PET
- PVC
- PS
- Other Plastics
- Metal
- Container Glass
- By Product Type
- Paper and Paperboard Product
- Folding Carton and Rigid Boxes
- Corrugated Boxes and Containers
- Single-Use Paper Products
- Other Paper and Paperboard Types
- Plastic Product
- Rigid Plastics
- Bottles and Jars
- Caps and Closures
- Bulk-Grade Products
- Other Rigid Plastics
- Flexible Plastics
- Pouches
- Bags
- Films and Wraps
- Other Flexible Plastics
- Rigid Plastics
- Metal Product
- Cans
- Caps and Closures
- Aerosol Containers
- Other Metal Products
- Container Glass Product
- Bottles
- Jars
- Paper and Paperboard Product
- By Packaging Format
- Rigid Packaging Format
- Flexible Packaging Format
- By End-User Industry
- Food
- Beverage
- Pharmaceutical and Medical
- Personal Care and Cosmetics
- Industrial and Chemical
- Agriculture
- Automotive
- Other End-User Industries
List of Companies Covered in this Report:
- SCG Packaging Public Co. Ltd
- BG Container Glass Public Co. Ltd
- TPAC Packaging Public Co. Ltd
- Thai Beverage Can Co. Ltd
- TBPI Public Co. Ltd
- Eastern Polypack Co. Ltd
- Huhtamaki Oyj
- Amcor plc
- Sealed Air Corporation
- TOPPAN Inc.
- Thai Packaging Industry PCL
- Berli Jucker Public Company Limited
- Ball Corporation
- Crown Holdings, Inc.
- Alpla Werke Alwin Lehner GmbH & Co KG
- Oji Packaging (Thailand) Ltd
- Siam Toppan Packaging Co. Ltd
- Thai Cane Paper Public Co. Ltd
- DNP Asia Co. Ltd
- Printpack Asia Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Food and Beverage Output
- 4.2.2 Growth of E-commerce and Parcel Volumes
- 4.2.3 Demand for Convenient and Flexible Packs
- 4.2.4 Sustainability and Circular-Economy Mandates
- 4.2.5 BOI Incentives for Packaging Automation
- 4.2.6 Cannabis-Infused Food and Beverage Requires Child-Safe Packs
- 4.3 Market Restraints
- 4.3.1 Single-Use-Plastic Bans and Eco Taxes
- 4.3.2 Volatile Petrochemical Resin Prices
- 4.3.3 Shortage of Food-Grade rPET Feedstock
- 4.3.4 Low-Cost Import Competition From Vietnam and China
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value-Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Paper and Paperboard
- 5.1.2 Plastic
- 5.1.2.1 Polypropylene (PP)
- 5.1.2.2 HDPE and LDPE
- 5.1.2.3 PET
- 5.1.2.4 PVC
- 5.1.2.5 PS
- 5.1.2.6 Other Plastics
- 5.1.3 Metal
- 5.1.4 Container Glass
- 5.2 By Product Type
- 5.2.1 Paper and Paperboard Product
- 5.2.1.1 Folding Carton and Rigid Boxes
- 5.2.1.2 Corrugated Boxes and Containers
- 5.2.1.3 Single-Use Paper Products
- 5.2.1.4 Other Paper and Paperboard Types
- 5.2.2 Plastic Product
- 5.2.2.1 Rigid Plastics
- 5.2.2.1.1 Bottles and Jars
- 5.2.2.1.2 Caps and Closures
- 5.2.2.1.3 Bulk-Grade Products
- 5.2.2.1.4 Other Rigid Plastics
- 5.2.2.2 Flexible Plastics
- 5.2.2.2.1 Pouches
- 5.2.2.2.2 Bags
- 5.2.2.2.3 Films and Wraps
- 5.2.2.2.4 Other Flexible Plastics
- 5.2.2.1 Rigid Plastics
- 5.2.3 Metal Product
- 5.2.3.1 Cans
- 5.2.3.2 Caps and Closures
- 5.2.3.3 Aerosol Containers
- 5.2.3.4 Other Metal Products
- 5.2.4 Container Glass Product
- 5.2.4.1 Bottles
- 5.2.4.2 Jars
- 5.2.1 Paper and Paperboard Product
- 5.3 By Packaging Format
- 5.3.1 Rigid Packaging Format
- 5.3.2 Flexible Packaging Format
- 5.4 By End-User Industry
- 5.4.1 Food
- 5.4.2 Beverage
- 5.4.3 Pharmaceutical and Medical
- 5.4.4 Personal Care and Cosmetics
- 5.4.5 Industrial and Chemical
- 5.4.6 Agriculture
- 5.4.7 Automotive
- 5.4.8 Other End-User Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 SCG Packaging Public Co. Ltd
- 6.4.2 BG Container Glass Public Co. Ltd
- 6.4.3 TPAC Packaging Public Co. Ltd
- 6.4.4 Thai Beverage Can Co. Ltd
- 6.4.5 TBPI Public Co. Ltd
- 6.4.6 Eastern Polypack Co. Ltd
- 6.4.7 Huhtamaki Oyj
- 6.4.8 Amcor plc
- 6.4.9 Sealed Air Corporation
- 6.4.10 TOPPAN Inc.
- 6.4.11 Thai Packaging Industry PCL
- 6.4.12 Berli Jucker Public Company Limited
- 6.4.13 Ball Corporation
- 6.4.14 Crown Holdings, Inc.
- 6.4.15 Alpla Werke Alwin Lehner GmbH & Co KG
- 6.4.16 Oji Packaging (Thailand) Ltd
- 6.4.17 Siam Toppan Packaging Co. Ltd
- 6.4.18 Thai Cane Paper Public Co. Ltd
- 6.4.19 DNP Asia Co. Ltd
- 6.4.20 Printpack Asia Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


