

|
시장보고서
상품코드
2125504
북미의 도시 보안 검색 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)North America Urban Security Screening - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
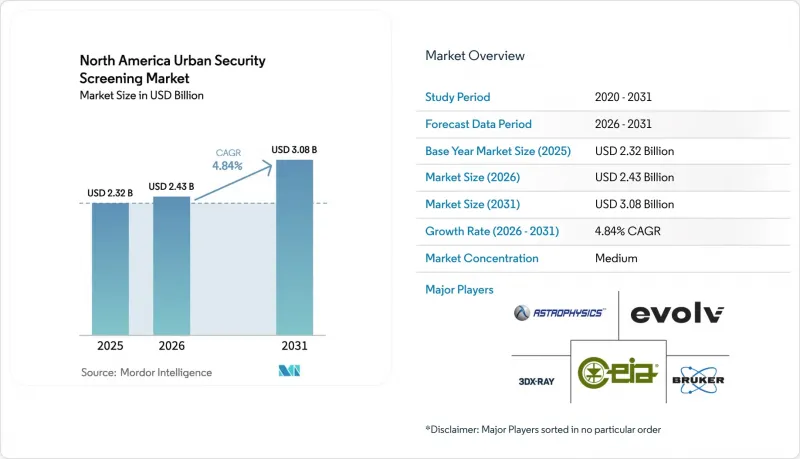
에 의하면, 북미의 도시 보안 검색 시장 규모는 2025년에 23억 2,000만 달러로 평가되었고, 2026년 24억 3,000만 달러에서 2031년까지 30억 8,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.84%를 나타낼 전망입니다.
본 보고서는 제품 유형별(X선 제품, 밀리파 제품, 기타), 최종 사용자 산업별(기업 건물, 우편실 보안 검색, 기타), 구축 방식별(고정식 보안 검색 시스템, 휴대용·핸드헬드형 보안 검색 장치, 기타), 기술별(기존 이미징, 기타), 국가별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
북미의 도시 보안 검색 시장 동향 및 인사이트
고도 위협 감지를 위한 보안 검색 분야의 자동화 발전
미국 국토안보부는 2024년, 위협 인식을 자동화하기 위해 4,500만 달러를 배정하며 기계 주도형 감지로의 결정적인 전환을 보여주었습니다. 자동화 시스템은 수동 분석으로 30초가 걸리던 화학 물질 흔적 식별을 단 3초 만에 수행할 수 있게 되어, 사업자의 교육 비용을 40% 절감하고 있습니다. 신발용 스캐너에 내장된 CT 알고리즘 덕분에 승객은 신발을 신은 채로 검사를 받을 수 있어, 검사 대열의 처리 속도가 향상되었습니다. 새로운 위협 데이터를 통해 스스로 학습하는 AI 모델 덕분에 기술적 업데이트의 필요성이 줄어들었습니다. TSA(미국 교통안전청)의 자동 검색 레인에 관한 기준은 민간 시설에도 유사한 기능의 도입을 촉진하고 있어, 공공 및 상업시설 전반에 걸쳐 지속적인 수요가 보장되고 있습니다.
지역 전반에 걸친 테러 활동의 급증
연방수사국(FBI) 기록에 따르면, 2024년 국내 테러 수사 건수는 23% 증가했습니다. 이에 따라 각 기관은 종합적인 보호를 실현하기 위해 주변 경비에 더해 실내 모니터링을 다층적으로 도입하고 있습니다. 예산 배분은 사후 대응형 바리케이드에서 비정상적인 행동을 감지하는 예측 분석으로 전환되고 있습니다. 차량 탑재형 폭발물에 대응하기 위해 기업들이 중요 자산에서 떨어진 곳에 검문소를 설치하게 되면서, 이동식 검색 차량에 대한 수요가 급증하고 있습니다. 보험사들은 현재 보상 범위를 확대하기 전에 문서화된 보안 절차를 제시할 것을 요구하고 있으며, 이는 시장 수요를 더욱 부추기고 있습니다.
지정학적 상황과 코로나19 팬데믹으로 인한 공급망 문제
2024년에 발표된 첨단 이미지 처리 부품에 대한 수출 규제로 인해 리드타임이 12주에서 20주로 연장되었습니다. 반도체 부족으로 인해 제조업체들은 구하기 쉬운 칩셋에 맞추어 기판을 재설계할 수밖에 없었습니다. 기업들은 지연에 대비해 재고를 15-25% 늘리고 있으며, 이로 인해 운전 자본 수요가 증가하고 있습니다. OSI Systems는 지정학적 리스크를 헤지하기 위해 미국 내 생산을 확대했습니다. 이러한 추세로 인해 이익률은 압박을 받겠지만, 제품 공급 안정화는 기대됩니다. 구매자들은 여러 지역에 조립 라인을 보유한 공급업체를 점점 더 선호하고 있으며, 이는 북미 도시 보안 검색 시장 경쟁 구도에 영향을 미치고 있습니다.
부문 분석
X선 장비는 항공, 물류, 공공시설에서 확립된 기준 덕분에 2025년 북미 도시 보안 검색 시장에서 44.02%의 점유율을 유지했습니다. 이 부문은 성숙기에 접어들었기 때문에 견고한 재판매 네트워크와 숙련된 운영자 풀이 형성되어 있습니다. 그럼에도 불구하고, 북미 도시 보안 검색 시장은 기능이 풍부한 AI 탑재 멀티 센서 시스템으로 전환되고 있으며, 2031년까지 연평균 성장률(CAGR) 6.21%로 확대될 것으로 예측됩니다. 각 벤더사는 위협 시그니처를 밀리초 단위로 분류하는 컨볼루션 신경망을 통합하여 수동 개입을 줄이고 있습니다. 금속 감지기는 여전히 경기장 주변 경비를 담당하고 있지만, 방사선 피폭 우려로 인해 X선 사용이 제한되는 장소에서는 밀리파 스캐너가 보급되고 있습니다. 방사선 감지 장치는 정부 기관의 방사선 위협에 대한 인식이 높아지는 것을 배경으로 수요가 확대되고 있습니다. 미량 검출 모델은 마약 및 화학 무기 물질 감지로 확대되면서 대상 수요의 범위를 넓히고 있습니다.
기존 X선 장치에 AI를 통합함으로써 자산의 수명을 연장하고, 막대한 설비 투자를 들이지 않고도 분석 기능을 제공할 수 있습니다. 스미스 디텍션(Smith Detection)은 기존 검사 레인과 통합할 수 있어 검사 시간을 단축하는 CT 방식의 신발용 스캐너를 출시했습니다. 한편, 개방형 아키텍처 인터페이스를 통해 타사 분석 기능을 중첩할 수 있게 되어, 최고 수준의 생태계 구축이 촉진되고 있습니다. 이러한 모듈성은 하드웨어 판매를 뒷받침하는 동시에, 가치 창출을 소프트웨어 구독 모델로 전환시키고 있습니다. 그 결과, X선, 미량 검출, 방사선 센서를 통합된 콘솔에 집약한 제품 라인에서는 구매 주기가 단축되고 있습니다.
2025년에는 규제 요건과 지속적인 승객 흐름을 반영하여 교통 시설이 매출의 32.35%를 차지했습니다. 그러나 데이터센터는 연평균 성장률(CAGR) 6.49%를 나타낼 것으로 예측되어 성장의 주역이 되고 있습니다. 물리적 침입은 가동 시간 및 ISO 27001과 같은 프레임워크에 따른 규정 준수 의무를 위협하기 때문에 생체 인식 및 AI 감지기에 대한 투자를 촉진하고 있습니다. 존슨 컨트롤즈의 조사에 따르면, 2024년에는 데이터 시설의 67%에서 무단 접근 시도가 기록되었습니다. 또한 기업 캠퍼스에서도 신원 확인 및 스크리닝 게이트를 통합한 방문자 관리 솔루션에 자금을 할당하고 있습니다.
우편실에서는 주목을 받은 소포 관련 사건을 계기로, 단순한 터널형 X선 검사 장치에서 화학 센서가 통합된 시스템으로 진화하고 있습니다. 창고 및 물류 사업자들은 적재 패턴에 맞추어 이동이 가능한 모바일 스캐너를 선호하고 있으며, 이는 북미의 도시 보안 검색 시장이 유연성을 중시하는 방향으로 전환되고 있음을 뒷받침합니다. 정부 기관은 여전히 안정적인 구매자이지만, 예산 상한선으로 인해 각 기관은 총 소유 비용(TCO)을 엄격하게 평가해야 하는 상황에 직면해 있습니다. 법 집행 기관 시설에서는 가혹한 사용 환경을 견디고 금지 물품을 감지할 수 있는 장비가 요구되고 있습니다. 경기장이나 행사장에서는 계절적인 수요 급증에 대응하기 위해 휴대용 포털이 선택되고 있으며, 대여 및 관리형 서비스 모델의 필요성이 확고해지고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the North America urban security screening market size was valued at USD 2.32 billion in 2025 and estimated to grow from USD 2.43 billion in 2026 to reach USD 3.08 billion by 2031, at a CAGR of 4.84% during the forecast period (2026-2031).
This report is Segmented by Product Type (X-Ray Products, Millimeter Wave Products, and More), End-User Industry (Corporate Buildings, Mailroom Screening, and More), Deployment Mode (Fixed Screening Systems, Portable/Handheld Screening Devices, and More), Technology (Conventional Imaging, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
North America Urban Security Screening Market Trends and Insights
Increasing Automation in Security Screening to Detect Advanced Threats
The Department of Homeland Security allocated USD 45 million in 2024 to automate threat recognition, signaling a decisive pivot toward machine-driven detection. Automated systems now identify chemical traces in 3 seconds versus 30 seconds for manual analysis, cutting operator training costs by 40%. CT algorithms embedded in shoe scanners allow passengers to keep their footwear on, speeding lane throughput. AI models that self-learn from new threat data reduce the need for engineering updates. TSA's automated-screening-lane standards are pushing private venues to adopt similar capabilities, ensuring sustained demand across public and commercial sites.
Upsurge in Terror Activities Across the Region
The Federal Bureau of Investigation recorded a 23% jump in domestic terrorism investigations in 2024. Organizations are therefore layering perimeter screening with interior surveillance for holistic protection. Budget allocations have migrated from reactive barricades to predictive analytics that flag anomalous behavior. Demand for mobile screening vehicles has surged as firms position checkpoints farther from critical assets to counter vehicle-borne explosives. Insurers now request documented security processes before extending coverage, reinforcing market demand.
Supply Chain Issues Caused by Geopolitical Scenario and the COVID-19 Pandemic
Export restrictions on advanced imaging components announced in 2024 pushed lead times from 12 weeks to 20 weeks. Semiconductor shortages forced manufacturers to re-engineer boards around readily available chipsets. Firms are carrying 15-25% higher inventory to buffer delays, inflating working capital needs. OSI Systems expanded U.S. manufacturing to hedge geopolitical risk, a trend expected to tighten margins yet stabilize availability. Buyers increasingly choose vendors with multi-region assembly lines, influencing competitive positioning within the North America urban security screening market.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Government Initiatives on Security Inspection in Schools and Colleges
- Increasing Government Initiatives for Smart Cities
- High Installation and Maintenance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
X-ray equipment maintained 44.02% of the North America urban security screening market share in 2025, thanks to entrenched standards in aviation, logistics, and public venues. The segment's maturity results in robust resale networks and trained operator pools. Even so, the North America urban security screening market is pivoting toward capability-rich AI-powered multi-sensor systems, which are expected to rise at a 6.21% CAGR through 2031. Vendors embed convolutional neural networks that classify threat signatures in milliseconds, shrinking manual intervention. Metal detectors continue to secure stadium perimeters, while millimeter-wave scanners gain traction where radiation exposure concerns limit X-ray usage. Radiation detection units ride on heightened radiological threat awareness among government agencies. Trace detection models expand into narcotics and chemical warfare agent discovery, widening addressable demand.
Incorporating AI into legacy X-ray machines extends asset life and delivers analytics without large capital swaps. Smiths Detection rolled out a CT shoe scanner that integrates with existing lanes and reduces divestiture time. Meanwhile, open architecture interfaces permit third-party analytics overlays, encouraging best-of-breed ecosystems. This modularity sustains hardware sales while shifting value creation toward software subscriptions. Consequently, product lines that converge X-ray, trace, and radiation sensors into a unified console are seeing faster purchase cycles.
Transportation facilities controlled 32.35% revenue in 2025, reflecting regulatory mandates and continuous passenger flows. Yet data centers headline growth with a projected 6.49% CAGR. Physical breaches jeopardize uptime and compliance obligations under frameworks such as ISO 27001, catalyzing investment in biometrics and AI detectors. A Johnson Controls survey noted that 67% of data facilities recorded unauthorized access attempts in 2024. Corporate campuses also allocate funds to visitor management solutions that merge identity verification with screening gates.
Mailrooms have evolved from simple tunnel X-rays to integrated chemical sensors after headline package incidents. Warehouse and logistics operators favor mobile scanners that relocate with loading patterns, underscoring the North America urban security screening market's shift toward flexibility. Government buildings remain steady purchasers, although budget ceilings push agencies to evaluate the total cost of ownership rigorously. Law-enforcement sites demand contraband-capable devices that withstand rugged usage. Stadiums and event venues opt for portable portals to deal with seasonal spikes, cementing the case for rental and managed-service models.
Complete Report Scope:
- By Product Type
- X-ray Products
- Millimeter Wave Products
- Metal Detectors
- Radiation Detection Products
- Chemical and Trace Detection Products
- AI-Powered Multi-Sensor Systems
- By End-User Industry
- Corporate Buildings
- Mailroom Screening
- Warehouse and Logistics
- Government Buildings
- Transportation
- Data Centers
- Law Enforcement
- Stadiums and Large Venues
- Other End-User Industries
- By Deployment Mode
- Fixed Screening Systems
- Portable / Handheld Screening Devices
- Walk-through Portals
- Vehicle-mounted Screening Units
- By Technology
- Conventional Imaging
- Artificial Intelligence-based Threat Detection
- Machine Learning Enhanced Analytics
- Terahertz Imaging
- RFID and IoT Integration
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- 3DX-Ray Ltd. (Image Scan Holdings PLC)
- Astrophysics Inc.
- Bruker Corporation
- CEIA SpA
- Evolv Technologies Holdings Inc.
- Leidos Holdings Inc.
- Liberty Defense Holdings Ltd.
- Linev Systems US Inc.
- Nuctech Company Ltd.
- Rapiscan Systems Limited
- Rohde and Schwarz GmbH and Co KG
- Smiths Detection Group Ltd.
- Tek84 Inc.
- Teledyne FLIR LLC
- Thermo Fisher Scientific Inc.
- Vehant Technologies Pvt. Ltd.
- VOTI Detection Inc.
- Garrett Metal Detectors LLC
- OSI Systems Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing automation in security screening to detect advanced threats
- 4.2.2 Upsurge in terror activities across the region
- 4.2.3 Increasing government initiatives on security inspection in schools and colleges
- 4.2.4 Increasing government initiatives for smart cities
- 4.2.5 Rapid adoption of AI-based analytics reducing false alarms
- 4.2.6 Integration of touchless biometric screening driven by hygiene norms
- 4.3 Market Restraints
- 4.3.1 Supply chain issues caused by geopolitical scenario and the COVID-19 pandemic
- 4.3.2 High installation and maintenance costs
- 4.3.3 Public privacy concerns over advanced imaging technologies
- 4.3.4 Limited cybersecurity safeguards in networked screening devices
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Impact of Macroeconomic Factors
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Product Type
- 5.1.1 X-ray Products
- 5.1.2 Millimeter Wave Products
- 5.1.3 Metal Detectors
- 5.1.4 Radiation Detection Products
- 5.1.5 Chemical and Trace Detection Products
- 5.1.6 AI-Powered Multi-Sensor Systems
- 5.2 By End-User Industry
- 5.2.1 Corporate Buildings
- 5.2.2 Mailroom Screening
- 5.2.3 Warehouse and Logistics
- 5.2.4 Government Buildings
- 5.2.5 Transportation
- 5.2.6 Data Centers
- 5.2.7 Law Enforcement
- 5.2.8 Stadiums and Large Venues
- 5.2.9 Other End-User Industries
- 5.3 By Deployment Mode
- 5.3.1 Fixed Screening Systems
- 5.3.2 Portable / Handheld Screening Devices
- 5.3.3 Walk-through Portals
- 5.3.4 Vehicle-mounted Screening Units
- 5.4 By Technology
- 5.4.1 Conventional Imaging
- 5.4.2 Artificial Intelligence-based Threat Detection
- 5.4.3 Machine Learning Enhanced Analytics
- 5.4.4 Terahertz Imaging
- 5.4.5 RFID and IoT Integration
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 3DX-Ray Ltd. (Image Scan Holdings PLC)
- 6.4.2 Astrophysics Inc.
- 6.4.3 Bruker Corporation
- 6.4.4 CEIA SpA
- 6.4.5 Evolv Technologies Holdings Inc.
- 6.4.6 Leidos Holdings Inc.
- 6.4.7 Liberty Defense Holdings Ltd.
- 6.4.8 Linev Systems US Inc.
- 6.4.9 Nuctech Company Ltd.
- 6.4.10 Rapiscan Systems Limited
- 6.4.11 Rohde and Schwarz GmbH and Co KG
- 6.4.12 Smiths Detection Group Ltd.
- 6.4.13 Tek84 Inc.
- 6.4.14 Teledyne FLIR LLC
- 6.4.15 Thermo Fisher Scientific Inc.
- 6.4.16 Vehant Technologies Pvt. Ltd.
- 6.4.17 VOTI Detection Inc.
- 6.4.18 Garrett Metal Detectors LLC
- 6.4.19 OSI Systems Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


