

|
시장보고서
상품코드
2125525
탈장 메쉬 기기 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Hernia Mesh Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 탈장 메쉬 기기 시장 규모는 2026년에 44억 7,000만 달러에 이르고, 2031년까지 연평균 복합 성장률(CAGR) 4.23%로 55억 달러에 이를 것으로 예측됩니다.
이는 수술 건수 증가와 지속되는 소송으로 인한 역풍 사이의 균형을 맞춘 꾸준한 성장을 반영한 것입니다.
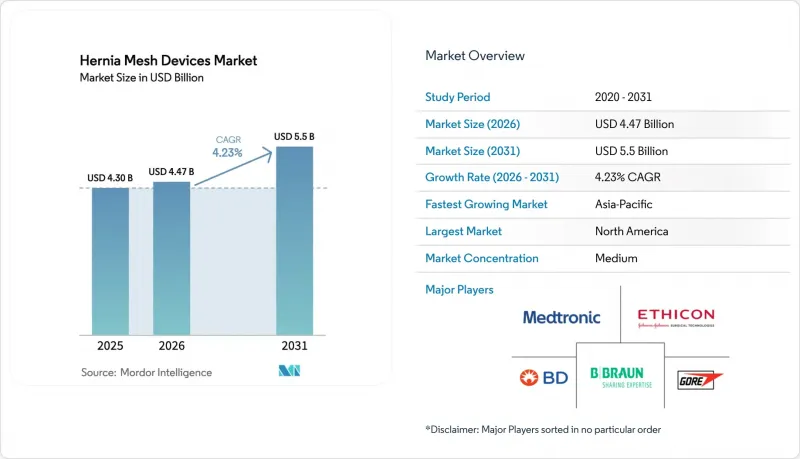
본 보고서는 탈장의 유형(서혜부 탈장, 절개부/복벽 탈장, 기타), 메쉬의 유형(합성, 생체 유래, 바이오합성/하이브리드), 메쉬의 재질(비흡수성, 기타),외과적 복구 수술법(개복술, 복강경 수술, 로봇 보조 수술), 최종 사용자(병원 등), 지역(북미 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 탈장 메쉬 기기 시장 동향 및 인사이트
비만 및 고령 인구에서 허니아 수술 건수 증가
세계 비만 유병률의 상승과 60세 이상 고령층 증가로 인해 수술 건수가 증가하고 있습니다. 특히 복벽 결손증의 경우, 비만 환자의 발생률이 표준 체중 환자에 비해 2.42배나 높은 것으로 보고되었습니다(1). 메타분석 데이터에 따르면, 비만은 서혜부 탈장의 재발률을 1.27배 높이는 것으로 나타났으며, 이로 인해 외과의들은 BMI 수치가 높은 사례에서 두꺼운 폴리프로필렌 재질 또는 보강된 복합 소재로 만들어진 메쉬를 우선적으로 사용해야 하는 상황에 놓여 있습니다. 세계보건기구(WHO)의 예측에 따르면, 2050년까지 고령 인구는 21억 명에 달할 것으로 예상되며, 이 연령대에서는 결합 조직의 취약성이나 동반 질환이 나타나 메쉬의 유착을 어렵게 할 가능성이 있습니다. 치유 기능 저하에 대응하여 설계된 흡수성 메쉬와 하이브리드 메쉬는 이러한 추세로 인해 수혜를 입고 있으며, 특히 복잡한 복벽 재건술에서 그 수요가 증가하고 있습니다. 이 분야는 이미 탈장 메쉬 기기 시장에서 연평균 성장률(CAGR) 6.54%로 성장을 지속하고, 있습니다. 체중 감량 수술을 받은 환자나 재개복 수술 사례의 경우, 대개 더 크고 여러 부위에 걸쳐 있는 결손이 발생하기 때문에 인장 지지력을 유지하면서 감염 위험을 줄여주는 프리미엄 배리어 메쉬에 대한 수요가 증가하고 있습니다.
최소 침습 및 로봇 보조 탈장 복구술로의 전환
미국의 탈장 치료 센터에서 로봇 플랫폼 도입은 전환점을 넘어섰습니다. 2022년부터 2023년까지 서혜부 탈장 복구술의 54.9%에서 로봇 보조가 활용되어 복강경 수술의 45.1%를 상회한 결과, 개복 수술로의 전환율은 1.2%까지 떨어졌습니다. 병원에서는 ‘다빈치(da Vinci)’ 시스템을 여러 전문 분야에서 공동으로 이용하고 있으며, 외과의사는 일반적으로 16-20건의 로봇 수술을 경험함으로써 숙련 수준에 도달합니다. 이는 표준 복강경 수술에 필요한 건수의 절반에 해당합니다. 메쉬의 설계도 이러한 추세를 따르고 있어, 8mm 트로카를 통과하고 추가 고정 없이도 전개할 수 있는 얇은 기기이 등장하고 있습니다. 고어(Gore)사의 ‘SYNECOR’ 하이브리드 메쉬는 버드(Bard)사의 ‘Soft Mesh’보다 2.5배 높은 인장 강도를 갖추면서도 로봇 조작에 적합한 유연성을 유지하고 있습니다. 수술 시간은 여전히 복강경 수술보다 15-20분 더 길기 때문에 각 공급업체들은 봉합이 필요 없는 자가 고정 기능을 추가하고 있습니다. 2025년 CMS ASC 목록에 따라 로봇 보조 탈장 수술이 보험 적용 대상이 된 외래수술센터(ASC)에서는 수술 접근성이 확대되고 있으며, 처리 시간을 단축하는 사전 멸균된 메쉬 키트에 대한 수요가 증가하고 있습니다.
만성 통증 및 유착 위험을 둘러싼 기기 리콜 및 소송
2024년 합의금은 10억 달러 이상에 달하며, 여기에는 BD가 3만 8,000건의 소송을 해결한 것도 포함되어 있어, 만성 통증 및 유착 관련 청구에 따른 재정적 위험의 크기를 여실히 드러내고 있습니다. 에시콘(Ethicon)사의 ‘피지오메쉬(PhysioMesh)’는 2016년에 판매를 중단했음에도 불구하고 여전히 3,617건의 소송이 계류 중이며, 한편 게팅게(Getinge)사는 2023년에 관련 소송의 합의금으로 4억 5,000만 스웨덴 크로나를 지급했습니다. 현재 병원 측은 보상 조항과 90일간의 합병증 추적 조사를 강력히 요구하고 있으며, 이로 인해 공급업체는 가격 인하를 강요받고, 고어(Gore)사의 BIO-A에 대한 13년간의 추적 조사(재발률 6.2%)와 같은 장기 데이터를 강조할 수밖에 없는 상황입니다. 소송은 획기적인 혁신을 저해하며, 연구개발의 방향성을 광범위한 감시 의무를 초래할 수 있는 신소재 개발이 아닌 기존 기기 라인의 확장으로 돌리고 있습니다.
부문 분석
비만 및 재개복 수술 증가에 힘입어 복벽 및 절개창 복구 시장은 2031년까지 연평균 성장률(CAGR)이 6.54%를 기록하며, 서혜부 시장의 성장률을 상회할 것으로 예측됩니다. 서혜부 복구술은 2025년에 탈장 메쉬 기기 시장 점유율 55.43%를 차지했으나, BMI와 서혜부 결손 사이에는 역상관 관계(오즈비 0.60)가 관찰됨에 따라 연간 성장률이 둔화되고 있습니다.
탈장 메쉬 기기 시장에서는 구성 요소의 분리나 대형 복합 메쉬가 필요한 10cm를 초과하는 복벽 탈장 사례가 점점 증가하고 있습니다. 로봇 수술의 보급은 서혜부 수술을 촉진하고 있으며(2022년부터 2023년까지 서혜부 복원술의 54.9%에서 로봇 수술이 채택되었습니다),반면 복잡한 복벽 재건술에서는 여전히 OviTex와 같은 생체 유래 스캐폴드를 병용한 개복 수술이 주류를 이루고 있으며, 이것이 TELA Bio사의 매출 29% 증가의 원동력이 되었습니다. 비만 수술 후 환자군이나 대퇴 탈장을 앓고 있는 고령 여성의 경우, 비정중선 결손 부위에 대한 메쉬 보강에 대한 수요는 다양하지만 꾸준히 유지되고 있습니다.
2025년에는 합성 메쉬가 매출의 85.11%를 차지했으나, 외과의사들이 적응증을 명백한 오염 상태 이외의 영역으로 확대함에 따라 생체 메쉬는 연평균 성장률(CAGR) 6.42%로 성장을 가속화할 것으로 예측됩니다. 클린·컨테미네이티드형 복벽 복구 분야에서 Phasix사는 2024 회계연도에 두 자릿수 성장을 기록하며, 감염 위험이 높은 상황에서도 흡수성 P4HB 스캐폴드가 큰 시장 점유율을 확보할 수 있음을 입증했습니다.
SYNECOR와 같은 하이브리드 설계의 탈장 메쉬 기기 시장 규모는 보험사들이 감염 저항성을 갖추고 저렴한 대체품을 요구함에 따라 확대될 것으로 예측됩니다. 외래수술센터(ASC)는 여전히 가격에 민감하기 때문에 생체 유래 기기의 사용률은 수술 건수의 5% 미만에 그치고 있지만, 병원에서는 복잡한 복벽 증례의 최대 25%에서 이를 채택하고 있습니다. 등록 데이터에 따르면, 복벽 복원에서 경량 합성 메쉬가 중량 기기에 비해 실패율이 높은 것으로 나타남에 따라, 경량 합성 메쉬는 엄격한 검증을 받고 있으며, 무게와 강도의 균형 잡힌 비율의 필요성이 다시 한번 강조되고 있습니다.
지역별 분석
북미는 2025년 매출의 41.35%를 차지하며, 연간 100만 건이 넘는 수술 건수, 로봇 수술의 높은 보급률, 그리고 합병증이 적은 메쉬를 우대하는 조달 모델이 주요 견인차 역할을 하고 있습니다. BD사의 10억 달러 합의금 지급을 계기로, 이 지역의 보험사 및 병원은 장기적인 성능 데이터를 강력히 요구하고 있으며, 공급업체는 10년 이상의 실적을 갖춘 메쉬를 제공해야 하는 압박을 받고 있습니다. 2022년부터 2023년까지 서혜부 복원술에서 로봇 수술 이용률은 54%를 넘어섰으며, CMS(미국 의료보험서비스센터)의 보상 제도 하에서 ASC(외래수술센터(ASC))로의 전환이 가속화되면서 일상적인 수술 건수가 저비용 시설로 이동하고 있습니다.
중국의 보험 제도 개혁으로 수술에 대한 보험 적용 범위가 확대되고, 인도의 의료기기 규제 완화로 수입량이 증가하고 있어 아시아태평양은 연평균 성장률(CAGR) 5.67%라는 가장 높은 성장률을 나타낼 것으로 예측됩니다. 그러나 멸균 체계의 미비나 콜드체인의 제약으로 인해 1급 도시 이외의 지역에서는 생체 재료의 채택률이 여전히 낮은 수준이며, 저소득층 시장에서는 폴리프로필렌 메쉬가 주류를 이루고 있습니다. 싱가포르와 태국은 SYNECOR 등의 고급 메쉬를 활용하여 의료 관광객을 유치하고 있는 반면, TELA Bio의 국제 진출은 호주 및 동남아시아의 부유층을 대상으로 한 클리닉을 타겟으로 하고 있습니다.
유럽의 엄격한 의료기기 규정(MDR)은 신기기 출시를 지연시키고 있지만, 품질에 대한 기대는 확고히 하고 있습니다. EHS 지침에 따라 메쉬 사용은 극히 작은 결손 부위로만 제한되어 있어, 1인당 총 소비량을 억제하고 있습니다. 스웨덴의 소송은 미국만큼 심각하지는 않지만, 여전히 주목할 만한 수준에 있습니다. 게팅게(Getinge)사가 4억 5,000만 스웨덴 크로나의 합의금을 지급한 사례는 이 지역의 리스크 증가를 여실히 보여주고 있습니다. 중동 및 아프리카 및 남미에서는 성장의 조짐이 보입니다. 걸프 국가들에서는 3차 의료를 위한 로봇 기술에 대한 투자가 진행되고 있으며, 브라질의 민간 의료 기관에서는 다빈치 시스템의 도입이 확대되고 있습니다. 그러나 공공 부문에서는 여전히 예산 제약이 있어 폴리프로필렌 기기에 대한 의존이 지속되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the hernia mesh devices market size reached USD 4.47 billion in 2026 and is expected to advance to USD 5.50 billion by 2031 at a 4.23% CAGR, reflecting measured growth that balances rising procedure volumes with persistent litigation headwinds.
This report is Segmented by Hernia Type (Inguinal, Incisional/Ventral, and More), Mesh Type (Synthetic, Biologic, and Bio-Synthetic/Hybrid), Mesh Material (Non-Absorbable, and More), Surgical Repair Technique (Open, Laparoscopic, and Robotic-Assisted), End-User (Hospitals, and More), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Hernia Mesh Devices Market Trends and Insights
Rising Surgical Hernia Incidence in Obese and Aging Populations
Global obesity prevalence and a growing cohort aged 60 plus are raising procedure counts, particularly for ventral defects that are 2.42 times more common in obese patients than in normal-weight peers[1]. Meta-analysis data link obesity to a 1.27-fold higher inguinal recurrence, pressing surgeons to favor heavyweight polypropylene or reinforced composites in high-BMI cases. The World Health Organization projects that there will be 2.1 billion seniors by 2050, a demographic likely to present connective-tissue weakness and comorbidities that complicate mesh integration. Absorbable and hybrid meshes designed for impaired healing benefit from this trend, especially in complex ventral reconstructions that already exhibit a 6.54% CAGR within the Hernia mesh devices market. Post-bariatric patients and repeat laparotomy cases often result in larger, multi-territory defects, driving the consumption of premium barrier meshes that reduce infection risk while maintaining tensile support.
Shift Toward Minimally Invasive and Robotic Hernia Repairs
Robotic platforms have surpassed the adoption tipping point in U.S. hernia centers, with 54.9% of inguinal repairs utilizing robotic assistance during 2022-2023, compared to 45.1% using laparoscopic techniques, thereby reducing conversion rates to open surgery to 1.2%. Hospitals amortize da Vinci systems across multiple specialties, and surgeons typically reach proficiency after 16-20 robotic cases, which is half the number required for standard laparoscopy. Mesh design has followed suit, with low-profile products that roll through an 8 mm trocar and unfold without extra fixation; Gore's SYNECOR hybrid mesh delivers 2.5 times the tensile strength of Bard Soft Mesh and remains pliable for robotic manipulation. Operative time still runs 15-20 minutes longer than laparoscopy, prompting suppliers to add self-gripping features that eliminate the need for sutures. Ambulatory centers, now eligible for robotic hernia reimbursement under the 2025 CMS ASC list, are expanding access and increasing demand for pre-sterilized mesh kits, which reduce turnaround times.
Product Recalls and Litigation Over Chronic Pain & Adhesion Risks
More than USD 1 billion in 2024 settlements, including BD's resolution of 38,000 lawsuits, underscore the financial stakes tied to chronic pain and adhesion claims. Ethicon's Physiomesh remains burdened by 3,617 pending suits despite its 2016 withdrawal, while Getinge paid SEK 450 million to settle related actions in 2023. Hospitals now insist on indemnity clauses and 90-day complication tracking, forcing suppliers to restrain prices and emphasize long-term data, such as Gore's 13-year BIO-A follow-up, which records a 6.2% recurrence rate. Litigation chills radical innovation, steering R&D toward predicate-line extensions rather than novel materials that could trigger extensive surveillance mandates.
Other drivers and restraints analyzed in the detailed report include:
- Product Innovations in Lightweight Composite and Barrier Meshes
- Adoption of Integratable Biosensors in Smart Mesh Prototypes
- High Per-Procedure Cost of Biologic and Biosynthetic Meshes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ventral and incisional repairs, propelled by obesity and repeat laparotomies, are forecast to outstrip inguinal growth at 6.54% CAGR through 2031. Inguinal repairs retained 55.43% of the Hernia mesh devices market share in 2025; however, their annual growth lags, as BMI shows an inverse association with groin defects, evidenced by an odds ratio of 0.60.
The hernia mesh devices market increasingly sees ventral cases exceeding 10 cm that require component separation and large composite meshes. Robotic uptake favors inguinal work-54.9% of groin repairs used robotics in 2022-2023-but complex ventral reconstructions still rely on open techniques paired with biologic scaffolds such as OviTex, which underpinned TELA Bio's 29% sales jump. Post-bariatric cohorts and elderly women with femoral hernias sustain a varied but steady demand for mesh reinforcement across non-midline defects.
Synthetic meshes accounted for 85.11% of the revenue in 2025; however, biologics are expected to accelerate at a 6.42% CAGR as surgeons expand indications beyond frank contamination. In clean-contaminated ventral repairs, Phasix posted double-digit growth during fiscal 2024, demonstrating that a resorbable P4HB scaffold can capture a significant market share when infection risk is elevated.
The hernia mesh devices market size for hybrid designs such as SYNECOR is projected to widen as payers seek lower-priced alternatives with infection resistance. Ambulatory centers remain price sensitive, so biologic use stays below 5% of their volume, while hospitals apply them in up to 25% of complex abdominal wall cases. Lightweight synthetics face scrutiny after registry data showed higher failure in ventral repairs versus medium-weight constructs, reinforcing the need for balanced weight-to-strength ratios.
Complete Report Scope:
- By Hernia Type
- Inguinal Hernia
- Incisional / Ventral Hernia
- Femoral Hernia
- Other Hernia Types
- By Mesh Type
- Synthetic Mesh
- Biologic Mesh
- Bio-Synthetic / Hybrid Mesh
- By Mesh Material
- Non-Absorbable (Polypropylene, ePTFE, Polyester)
- Partially-Absorbable (PP + PGA/PLA)
- Fully-Absorbable (P4HB, PGA)
- By Surgical Repair Technique
- Open Repair
- Laparoscopic Repair
- Robotic-Assisted Repair
- By End-User
- Hospitals
- Ambulatory Surgical Centres
- Other End-Users
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest Of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest Of Asia-Pacific
- Middle East And Africa
- GCC
- South Africa
- Rest Of Middle East And Africa
- South America
- Brazil
- Argentina
- Rest Of South America
- North America
Geography Analysis
North America accounted for 41.35% of 2025 revenue, driven by more than 1 million annual procedures, leading robotic penetration, and procurement models that reward low-complication meshes. The region's insurers and hospitals insist on long-term performance data after BD's USD 1 billion settlement, pushing suppliers toward meshes with decade-long track records. Robotic usage in inguinal repair surpassed 54% during 2022-2023, and ASC migration accelerates under CMS reimbursement, shifting routine volumes into lower-cost sites.
The Asia-Pacific region is expected to log the fastest growth rate of 5.67% CAGR, as Chinese insurance reforms expand surgical coverage and Indian device liberalization increases import flows. However, sterilization gaps and cold-chain limits keep biologic uptake low outside tier-one cities; polypropylene dominates lower-income segments. Singapore and Thailand leverage premium meshes, such as SYNECOR, to attract medical tourists, while TELA Bio's international expansion targets Australia and affluent clinics in Southeast Asia.
Europe's stringent Medical Device Regulation slows new product launches but cements quality expectations. EHS guidelines confine mesh use to tiny defects, tempering overall per-capita consumption. Litigation is less severe in Sweden than in the United States, but still notable; Getinge's SEK 450 million settlement highlights the growing regional risk. The Middle East & Africa, as well as South America, offer nascent growth, with Gulf states investing in tertiary robotics and Brazil's private network adding da Vinci systems. However, the public sectors remain budget-constrained and reliant on polypropylene.
- AbbVie Inc. (LifeCell)
- Advanced Medical Solutions Group
- B. Braun
- Beckton Dickinson
- Cook Group
- Cousin Surgery SAS
- Dipromed
- Duomed Group
- Ethicon Inc. (Johnson & Johnson)
- Getinge AB (Atrium Medical)
- Herniamesh Srl
- Integra LifeSciences Holdings Corp.
- Medtronic
- Novus Scientific AB
- Poly-Med Inc.
- TELA Bio Inc.
- Via Surgical Ltd.
- W. L. Gore & Associates
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Surgical Hernia Incidence in Obese and Aging Populations
- 4.2.2 Shift Toward Minimally Invasive and Robotic Hernia Repairs
- 4.2.3 Product Innovations in Lightweight Composite and Barrier Meshes
- 4.2.4 Adoption of Integratable Biosensors in Smart Mesh Prototypes
- 4.2.5 Uptake of Value-Based Procurement Contracts Favoring Low Complication Meshes
- 4.2.6 Outsourcing of Custom 3D-Printed Meshes by Specialty Centers
- 4.3 Market Restraints
- 4.3.1 Product Recalls and Litigation Over Chronic Pain & Adhesion Risks
- 4.3.2 High Per-Procedure Cost of Biologic and Biosynthetic Meshes
- 4.3.3 Availability of Suture-Only Tissue Repairs for Small Defects
- 4.3.4 Slow Uptake in Emerging Markets Owing to Sterilization Infrastructure Gaps
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Landscape
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat Of New Entrants
- 4.7.2 Bargaining Power Of Buyers
- 4.7.3 Bargaining Power Of Suppliers
- 4.7.4 Threat Of Substitutes
- 4.7.5 Intensity Of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Hernia Type
- 5.1.1 Inguinal Hernia
- 5.1.2 Incisional / Ventral Hernia
- 5.1.3 Femoral Hernia
- 5.1.4 Other Hernia Types
- 5.2 By Mesh Type
- 5.2.1 Synthetic Mesh
- 5.2.2 Biologic Mesh
- 5.2.3 Bio-Synthetic / Hybrid Mesh
- 5.3 By Mesh Material
- 5.3.1 Non-Absorbable (Polypropylene, ePTFE, Polyester)
- 5.3.2 Partially-Absorbable (PP + PGA/PLA)
- 5.3.3 Fully-Absorbable (P4HB, PGA)
- 5.4 By Surgical Repair Technique
- 5.4.1 Open Repair
- 5.4.2 Laparoscopic Repair
- 5.4.3 Robotic-Assisted Repair
- 5.5 By End-User
- 5.5.1 Hospitals
- 5.5.2 Ambulatory Surgical Centres
- 5.5.3 Other End-Users
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest Of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest Of Asia-Pacific
- 5.6.4 Middle East And Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest Of Middle East And Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest Of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share For Key Companies, Products & Services, And Recent Developments)
- 6.3.1 AbbVie Inc. (LifeCell)
- 6.3.2 Advanced Medical Solutions Group plc
- 6.3.3 B. Braun SE
- 6.3.4 Becton, Dickinson And Company
- 6.3.5 Cook Medical LLC
- 6.3.6 Cousin Surgery SAS
- 6.3.7 Dipromed Srl
- 6.3.8 Duomed Group
- 6.3.9 Ethicon Inc. (Johnson & Johnson)
- 6.3.10 Getinge AB (Atrium Medical)
- 6.3.11 Herniamesh Srl
- 6.3.12 Integra LifeSciences Holdings Corp.
- 6.3.13 Medtronic plc
- 6.3.14 Novus Scientific AB
- 6.3.15 Poly-Med Inc.
- 6.3.16 TELA Bio Inc.
- 6.3.17 Via Surgical Ltd.
- 6.3.18 W. L. Gore & Associates Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


