|
시장보고서
상품코드
2125581
해저 케이블 시스템 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Submarine Cable Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
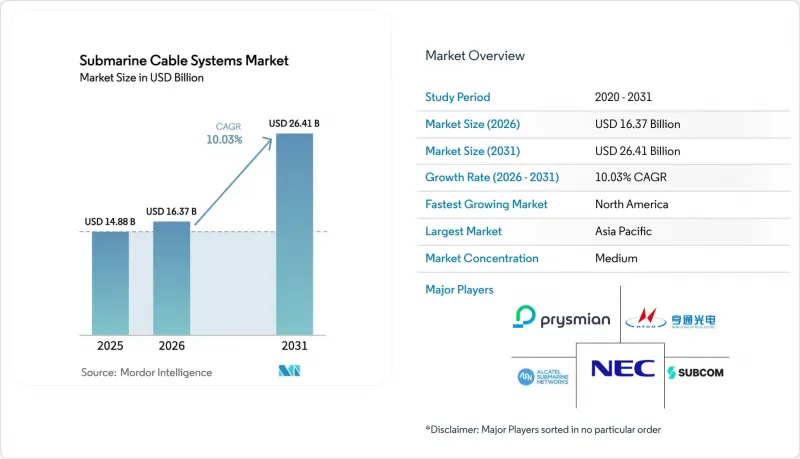
에 의하면, 해저 케이블 시스템 시장 규모는 2025년에 148억 8,000만 달러로 평가되었고 2026년 163억 7,000만 달러에서 2031년까지 264억 1,000만 달러에 이를 것으로 추정되고 있어 예측 기간(2026-2031년) CAGR은 10.03%를 나타낼 전망입니다.
본 보고서에서는 업계를 유형별(웨트 플랜트 제품·드라이 플랜트 제품), 소유 유형별(복수 소유 시스템, 단일 소유 시스템, 다자간 개발은행 지원 시스템),용도별(통신·인터넷 백본, 해상 풍력 발전의 송전 케이블·어레이 케이블 등), 광섬유 쌍 수별(8쌍 미만, 9-16쌍, 그 이상), 지역별로 분류하고 있습니다.
전 세계 해저 케이블 시스템 시장 동향 및 인사이트
하이퍼스케일러 주도의 대역폭 수요 급증
인공지능(AI) 워크로드 및 실시간 클라우드 애플리케이션에 대한 용량 요구 사항이 증가함에 따라, Google 및 Meta와 같은 기업들은 자비로 대양 횡단 시스템을 구축하기 시작했습니다. Proa 케이블과 Taihei 케이블이 특징인 구글의 ‘Pacific Connect’ 프로그램은 통신 사업자 컨소시엄을 거치지 않고 태평양 횡단 멀티테라비트급 링크를 추가했다는 점에서 이러한 변화를 상징합니다. 메타의 ‘프로젝트 워터워스(Project Waterworth)’는 24쌍의 광섬유를 사용하여 5개 대륙에 걸쳐 50,000km의 네트워크를 구축하고 있으며, 이는 하이퍼스케일러들이 통제권과 신속한 업그레이드 경로를 중시하고 있음을 여실히 보여줍니다. 이러한 프로젝트들은 구축 일정을 가속화하고 SDM 아키텍처를 표준화하고 있으며, 현재 2021년 이후 시작된 전 세계 신규 건설 프로젝트의 거의 절반을 차지하고 있습니다.
신흥 지역의 연결성을 위한 신속한 해저 케이블 건설
아프리카와 동남아시아의 디지털 인프라 격차는 지역 통신 사업자, 개발 은행, 클라우드 제공업체가 대용량 경로 건설에 공동 투자함에 따라 점차 줄어들고 있습니다. OMS 그룹의 MIST 케이블은 216 Tbps가 넘는 용량을 자랑하며, 2027년까지 인도, 말레이시아, 싱가포르, 태국을 연결할 예정입니다. 2024년 서아프리카에서 발생한 통신 장애는 단일 장애 지점(SPO) 문제를 드러냈으며, 각국 정부가 이중화 회선 구축을 지원하고 신속한 복구 서비스 비용을 부담하는 계기가 되었습니다. 이에 따라 추가 해저 설비 유닛 및 해저 케이블 설치선에 대한 장기적인 수요가 증가하고 있습니다.
데이터 주권에 관한 법규제로 인해 상륙 허가 취득이 복잡해짐
미국 연방통신위원회(FCC)의 해저 케이블 규정 개정에 따라 소유권 및 보안 대책에 관한 3년간의 보고가 의무화되었으며, 신규 상륙 승인 절차가 엄격해졌습니다. 인도 및 인도네시아의 유사한 데이터 현지화 법에 따라 국내 트래픽 종단이 의무화되어, 네트워크의 복잡성과 비용을 증가시키는 아키텍처 재설계를 피할 수 없게 되었습니다.
부문 분석
웨트 플랜트용 기어 리피터, 분기 장치, SDM 지원 광 증폭기는 2025년 매출의 67.65%를 차지했습니다. 이 하위 부문은 통신 사업자들이 첨단 재생 전자 기기에 의존하는 초장거리 경로를 선호함에 따라 2031년까지 연평균 성장률(CAGR) 10.62%로 확대될 것으로 예측됩니다. 해저 케이블 시스템 시장에서 웨트 플랜트 제품 시장 규모는 2025년에 100억 7,000만 달러에 달할 것이며, 향후 10년 말에는 184억 5,000만 달러에 이를 것으로 전망됩니다. 높은 기술적 진입 장벽이 기존 사업자를 보호하고 있어, 부품 비용이 상승하더라도 안정적인 가격 유지가 가능합니다.
ASN사의 SMART 케이블(해저 기후 센서 내장)과 같은 지능형 ? 플랜트 제품은 여러 기관을 통한 새로운 자금 조달 경로를 개척하고 있습니다. 육상 터미널 및 전력 공급 설비를 포함한 드라이 플랜트 장비는 나머지 시장 점유율을 차지하고 있지만, 하이퍼스케일러 기업들이 자체 제작한 육상국 하드웨어를 설계하게 됨에 따라 이익률 압박에 직면하고 있습니다. Open Cable 이니셔티브에 의한 표준화는 드라이 부문에서 독자 기술의 우위를 더욱 약화시키고 있습니다.
2025년에는 대서양 횡단 회선에서 기존 통신 사업자간의 제휴를 중심으로 한 컨소시엄 프로젝트가 54.12%로 여전히 가장 큰 점유율을 차지하고 있습니다. 그럼에도 불구하고, 클라우드 제공업체의 자본 지출(CAPEX) 전략에 힘입어 단일 소유자에 의한 사업이 연평균 성장률(CAGR) 13.32%로 가장 빠르게 확대되고 있습니다. 단일 소유자에 의한 건설에 할당되는 해저 케이블 시스템 시장 규모는 2025년에 68억 3,000만 달러로 추정되며, 2031년까지 144억 6,000만 달러로 확대될 것으로 예상되는데, 이는 적극적인 자체 건설 로드맵을 반영한 것입니다.
단일 소유 체제는 의사 결정 주기를 가속화하고, 32개 광섬유 쌍을 초과하는 맞춤형 SDM 설계를 가능하게 하여 새로운 용량 기록을 세우고 있습니다. 개발은행의 지원을 받는 이 시스템은 규모는 작지만 상업적 수익만으로는 불충분하여 공공 부문의 위험 완화가 필수적인, 가격에 민감한 아프리카 및 태평양 제도 지역의 회랑에서 연결성을 가능하게 합니다.
지역별 분석
북미는 2025년에 전 세계 매출의 29.12%를 차지했으며, 미국을 중심으로 한 하이퍼스케일러의 활동과 SDM 아키텍처의 조기 도입이 이를 견인했습니다. ‘퍼시픽 커넥트(Pacific Connect)’나 24페어의 ‘비프레스트(Bifrest)’ 시스템과 같은 프로젝트를 통해 태평양 횡단 회랑은 용량 증설의 최전선에 위치하고 있습니다. 국내 조달 규제로 인해 국내 생산이 촉진되고 있으며, LS 케이블의 버지니아주 거점과 프리즈미안의 메릴랜드주 투자로 인해 2027년까지 코어 도체의 연간 생산량은 총 2만 5,000톤 이상 증가할 전망입니다.
아시아태평양은 연평균 성장률(CAGR) 12.45%를 기록하며 가장 빠르게 성장하고 있는 지역입니다. 중국의 계약업체들은 2024년에 10만 km가 넘는 습식 공장을 납품할 예정이며, 2025년까지 세계 시장 점유율 60%라는 목표 달성을 목표로 하고 있습니다. 인도는 ‘인도-아시아 익스프레스’를 통해 지역 허브로의 전환을 추진하고 있으며, 한편 일본과 미국의 클라우드 기업과의 제휴를 통해 미크로네시아와 괌에 대한 착륙 거점 다각화가 진행되고 있습니다. 아세안(ASEAN) 국가들의 디지털 경제 지수 상승은 적어도 향후 10년 동안 다양한 경로를 통한 수요를 보장해 줄 것입니다.
해상 풍력 발전 메가 프로젝트와 멀티 기가와트급 에너지 상호 연결이라는 두 가지 원동력이 유럽 시장을 견인하고 있습니다. ‘이스턴 그린 링크 2’ 프로젝트만 해도 525kV 케이블 500km가 부설되며, 2029년 가동을 시작할 것으로 예측됩니다. 중동 및 아프리카는 대륙 간 전략적 거점으로서의 지위에서 혜택을 누리고 있으며, 아프리카의 ‘East2West’ 케이블 계획은 단일 경로에 대한 의존도를 낮추기 위해 개발은행으로부터 자금을 확보하고 있습니다. 남미는 규모는 작지만 전략적으로 중요한 지역으로 남아 있습니다. 구글의 훔볼트 케이블은 남태평양에서 아시아로 이어지는 최초의 직결 회선이 되어, 칠레의 통신망 지형을 완전히 바꿔 놓을 것입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 세분화
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.17According to Mordor Intelligence, the submarine cable systems market size was valued at USD 14.88 billion in 2025 and estimated to grow from USD 16.37 billion in 2026 to reach USD 26.41 billion by 2031, at a CAGR of 10.03% during the forecast period (2026-2031).
This report Segments the Industry Into by Type (Wet-Plant Products, and Dry-Plant Products), Ownership Type (Multiple-Ownership System, Single-Ownership System, and Multilateral Development-Bank-Backed System), Application (Telecom and Internet Backbone, Offshore Wind Power Export and Array Cables, and More), Fiber-Pair Count (Less Than 8 Fiber Pairs, 9 - 16 Fiber Pairs, and More), and Geography.
Global Submarine Cable Systems Market Trends and Insights
Hyperscaler-led bandwidth demand boom
Capacity requirements for artificial-intelligence workloads and real-time cloud applications have propelled companies such as Google and Meta to self-fund trans-oceanic systems. Google's Pacific Connect program, featuring the Proa and Taihei cables, exemplifies this shift by adding multi-terabit links across the Pacific without operator consortia. Meta's Project Waterworth spans 50,000 km over five continents with 24 fiber pairs, underscoring hyperscalers' preference for control and rapid upgrade paths. These projects accelerate deployment schedules, standardize SDM architectures, and now represent almost half of all new global builds initiated since 2021.
Rapid cable construction for emerging-region connectivity
The digital-infrastructure gap in Africa and Southeast Asia is narrowing as regional operators, development banks, and cloud providers co-finance high-capacity routes. OMS Group's MIST cable exceeds 216 Tbps and links India, Malaysia, Singapore, and Thailand by 2027. West-Africa outages in 2024 exposed single-point failures, prompting governments to back redundancy corridors and pay for expedited repair services, thereby lifting long-term demand for additional wet-plant units and marine-installation vessels.
Data-sovereignty legislation complicates landing licences
Revisions to the United States Federal Communications Commission submarine-line rules now mandate three-year reporting of ownership and security practices, tightening the approval window for new landings. Parallel data-localization statutes in India and Indonesia require in-country traffic termination, forcing architectural redesigns that elevate network complexity and cost.
Other drivers and restraints analyzed in the detailed report include:
- Offshore wind-farm export-cable surge
- SDM and >=32-fiber-pair technology lowering USD /Tb costs
- Global fiber and repeater supply-chain crunch
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Wet-plant gear-repeaters, branching units, and SDM-ready optical amplifiers-accounted for 67.65% revenue in 2025. This sub-segment is projected to climb at a 10.62% CAGR through 2031 as operators favor ultra-long-haul routes that rely on sophisticated regeneration electronics. The submarine cable systems market size for wet-plant products translates to USD 10.07 billion in 2025 and is on track for USD 18.45 billion by the decade's close. High engineering barriers shelter incumbents, delivering stable pricing even as component costs rise.
Intelligent wet-plant offerings such as ASN's SMART cable-with integrated seafloor climate sensors-open new multi-agency funding channels. Dry-plant equipment, covering shore-end terminals and power-feed equipment, captures the balance but endures margin compression as hyperscalers design in-house landing-station hardware. Standardization by the Open Cable initiative further dilutes proprietary advantages in the dry-segment.
Consortium projects remained the largest share contributor at 54.12% in 2025, anchored by traditional carrier collaborations on trans-Atlantic links. Nevertheless, single-ownership ventures are expanding fastest at a 13.32% CAGR, underpinned by cloud-provider CAPEX strategies. The submarine cable systems market size allocated to single-owner builds is estimated at USD 6.83 billion in 2025, climbing to USD 14.46 billion by 2031, a reflection of aggressive self-build roadmaps.
Single-party control accelerates decision cycles and permits bespoke SDM designs with >32 fiber pairs, charting new capacity highs. Development-bank-backed systems, although small in volume, unlock connectivity for price-sensitive African and Pacific Island corridors where commercial returns alone are inadequate and where public-sector de-risking is essential.
Complete Report Scope:
- By Type
- Wet-Plant Products
- Dry-Plant Products
- By Ownership Type
- Consortium / Multiple-Ownership System
- Single-Ownership (Private) System
- Multilateral Development-Bank-Backed System
- By Application
- Telecom and Internet Backbone
- Offshore Wind Power Export and Array Cables
- Oil and Gas Subsea Power / Comms
- Government and Defense Surveillance
- Scientific and Research Networks
- By Fiber-Pair Count
- Less Than 8 Fiber Pairs
- 9 - 16 Fiber Pairs
- 17 - 24 Fiber Pairs
- ? 25 Fiber Pairs (SDM)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Nordics
- Rest of Europe
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- Middle East
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia
- New Zealand
- Rest of Asia-Pacific
- North America
Geography Analysis
North America commanded 29.12% of global revenue in 2025, driven by US-centric hyperscaler activity and the early adoption of SDM architecture. Projects such as Pacific Connect and the 24-pair Bifrost system keep trans-Pacific corridors at the forefront of capacity upgrades. Domestic content rules encourage onshore manufacturing; LS Cable's Virginia site and Prysmian's Maryland investment will collectively add more than 25,000 t of annual core-conductor output by 2027.
Asia-Pacific represents the fastest-growing region with a 12.45% CAGR. China's contractors delivered over 100,000 km of wet-plant in 2024, chasing a 60% global share target by 2025. India is pivoting into a regional hub through the India-Asia Xpress, while Japan's alliances with US cloud firms bring landing diversity to Micronesia and Guam. Rising digital-economy indices across ASEAN economies guarantee multi-route demand for at least the next decade.
The twin engines of offshore-wind megaprojects and multi-gigawatt energy interconnectors buoy Europe's market. The Eastern Green Link 2 alone will lay 500 km of 525 kV cable and is expected online in 2029. Middle East and Africa benefit from strategic junction status between continents; Africa's East2West cable plan secures development-bank finance to reduce single-route exposure. South America remains small yet strategic: Google's Humboldt cable will offer the first direct South-Pacific link to Asia, reshaping Chile's connectivity map.
- Alcatel Submarine Networks SAS
- NEC Corporation
- Prysmian S.p.A. (Submarine Telecom and Power Cables BU)
- SubCom, LLC
- Hengtong Optic-Electric Co., Ltd.
- HMN Tech Co., Ltd. (Huawei Marine)
- Nexans S.A.
- Fujitsu Limited
- NTT Communications Corporation
- Google LLC
- Sumitomo Electric Industries, Ltd.
- Global Marine Systems Limited
- Orange Marine S.A.S.
- JDR Cable Systems Ltd.
- Zhongtian Technology Submarine Cable Co., Ltd.
- BW Digital Pte. Ltd. (Hawaiki)
- Padtec Holding S.A.
- Xtera, Inc.
- Orient Cable (NBO) Co., Ltd.
- Cable and Wireless Marine Service Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Hyperscaler-led bandwidth demand boom
- 4.2.2 Rapid cable construction for emerging region connectivity
- 4.2.3 Offshore wind-farm export-cable surge
- 4.2.4 SDM and 32-fiber-pair technology lowering USD/Tb costs
- 4.2.5 Redeployment of retired cables for resilience in underserved islands
- 4.2.6 Green-finance incentives for low-carbon, low-loss repeaters
- 4.3 Market Restraints
- 4.3.1 Data-sovereignty legislation complicating landing licences
- 4.3.2 Geopolitical vetoes on routes and vendors
- 4.3.3 Long permitting cycles and ESG push-back on near-shore routes
- 4.3.4 Global fiber and repeater supply-chain crunch
- 4.4 Evaluation of Critical Regulatory Framework
- 4.5 Value Chain Analysis
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact Assessment of Key Stakeholders
- 4.9 Key Use Cases and Case Studies
- 4.10 Impact on Macroeconomic Factors of the Market
- 4.11 Investment Analysis
5 MARKET SEGMENTATION
- 5.1 By Type
- 5.1.1 Wet-Plant Products
- 5.1.2 Dry-Plant Products
- 5.2 By Ownership Type
- 5.2.1 Consortium / Multiple-Ownership System
- 5.2.2 Single-Ownership (Private) System
- 5.2.3 Multilateral Development-Bank-Backed System
- 5.3 By Application
- 5.3.1 Telecom and Internet Backbone
- 5.3.2 Offshore Wind Power Export and Array Cables
- 5.3.3 Oil and Gas Subsea Power / Comms
- 5.3.4 Government and Defense Surveillance
- 5.3.5 Scientific and Research Networks
- 5.4 By Fiber-Pair Count
- 5.4.1 Less Than 8 Fiber Pairs
- 5.4.2 9 - 16 Fiber Pairs
- 5.4.3 17 - 24 Fiber Pairs
- 5.4.4 ? 25 Fiber Pairs (SDM)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Nordics
- 5.5.3.7 Rest of Europe
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Turkey
- 5.5.4.1.4 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Nigeria
- 5.5.4.2.4 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 Asia-Pacific
- 5.5.5.1 China
- 5.5.5.2 India
- 5.5.5.3 Japan
- 5.5.5.4 South Korea
- 5.5.5.5 ASEAN
- 5.5.5.6 Australia
- 5.5.5.7 New Zealand
- 5.5.5.8 Rest of Asia-Pacific
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Alcatel Submarine Networks SAS
- 6.4.2 NEC Corporation
- 6.4.3 Prysmian S.p.A. (Submarine Telecom and Power Cables BU)
- 6.4.4 SubCom, LLC
- 6.4.5 Hengtong Optic-Electric Co., Ltd.
- 6.4.6 HMN Tech Co., Ltd. (Huawei Marine)
- 6.4.7 Nexans S.A.
- 6.4.8 Fujitsu Limited
- 6.4.9 NTT Communications Corporation
- 6.4.10 Google LLC
- 6.4.11 Sumitomo Electric Industries, Ltd.
- 6.4.12 Global Marine Systems Limited
- 6.4.13 Orange Marine S.A.S.
- 6.4.14 JDR Cable Systems Ltd.
- 6.4.15 Zhongtian Technology Submarine Cable Co., Ltd.
- 6.4.16 BW Digital Pte. Ltd. (Hawaiki)
- 6.4.17 Padtec Holding S.A.
- 6.4.18 Xtera, Inc.
- 6.4.19 Orient Cable (NBO) Co., Ltd.
- 6.4.20 Cable and Wireless Marine Service Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment