

|
시장보고서
상품코드
2125590
영국의 파사드 시장 : 시장 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)UK Facade - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 영국의 파사드 시장 규모는 109억 9,000만 달러로 추정되고, 2025년 105억 달러에서 확대해, 2031년에는 137억 9,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 4.63%로 성장할 것으로 전망됩니다.
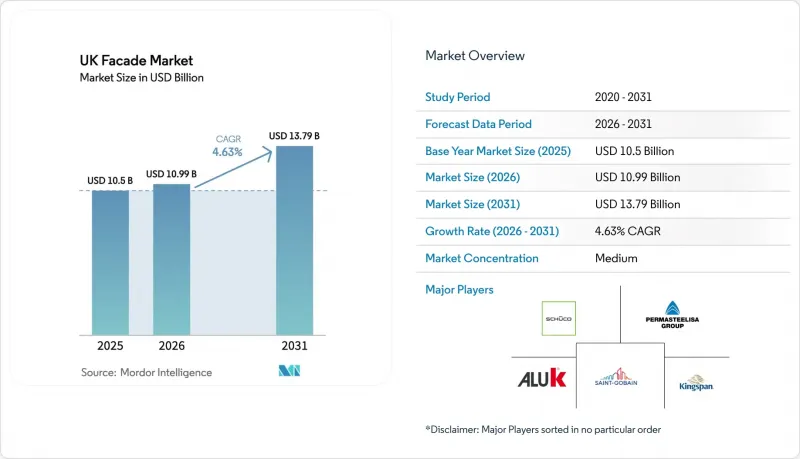
본 보고서는 유형별(통기형, 비통기형, 기타), 파사드 시스템별(레인스크린·클래딩 등), 재료별(유리, 금속 등), 시공 형태별(신축, 개수·리모델링), 최종 사용자별(상업시설, 주택, 기타), 지역별(잉글랜드 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
영국의 파사드 시장 동향 및 인사이트
글렌펠 화재 이후 외벽 재시공 급증
2022년 건축안전법에 따라, 2025년 4월 시점에서 높이 11미터를 초과하는 주택 건물 중 안전 기준을 충족하지 않는 외장재가 사용된 건물 5,052동이 확인되었으며, 그중 2,477동에서는 이미 보수 공사가 진행되고 있습니다. 1심 재판소의 판결에 따르면, 현재는 화재 위험 평가가 ‘중간 수준’이라 하더라도 허용할 수 없는 것으로 간주되어 책임 범위가 확대되고 있습니다. 보험사는 가연성 파사드를 보험 대상에서 제외하고 있어, 사실상 A1 등급 시스템의 채택이 의무화되어 있습니다. 개보수 공사에 대한 부가가치세(VAT) 공제를 통해 개보수 비용은 더욱 절감됩니다. 그 결과, 인증을 받은 불연성 제품 라인업을 갖춘 유서 깊은 공급업체들이 막대한 수요를 확보하고 있습니다.
‘넷 제로 2050’ 외피 요건
2025년에 도입될 예정인 ‘퓨처 홈스 스탠다드(Future Homes Standard)’에서는 운영 시 탄소 배출량의 대폭적인 감축이 요구되며, 런던에서는 1,000 m²를 초과하는 계획에 대해 전 생애 주기에 걸친 탄소 평가가 의무화되어 있습니다. 조사에 따르면, 외벽의 내재 탄소의 최대 60%를 유리가 차지하는 것으로 밝혀졌으며, 이에 따라 각 제조업체는 재생 재료 함유율이 높은 유리 제품 개발을 추진하고 있습니다. 정부가 데이터센터를 국가적으로 중요한 인프라로 인정함에 따라 계획 소요 기간은 단축되었으나, 에너지 성능 기준은 더욱 엄격해졌습니다. 공공 부문에서 BREEAM ‘엑설런트(Excellent)’ 등급을 획득하기 위한 기준은 현재 외관의 탈탄소화에 달려 있으며, 카디프의 벨린더 암 센터가 그 대표적인 예입니다.
알루미늄 및 유리 가격 변동
에너지 집약적인 알루미늄 제련은 공급 상황의 변화와 지정학적 무역 위험에 직면해 있으며, 그 영향이 파사드 예산에도 파급되고 있습니다. 2024년 6월 현재, 영국의 건축자재 지수는 전년 동월 대비 2.0% 하락을 기록했지만, 현물 가격은 여전히 불안정하여 리드타임이 긴 파사드 계약의 비용 계획 수립을 어렵게 하고 있습니다. 각 판유리 제조업체들은 분당 최대 100만 파운드(135만 100달러)에 달할 수 있는 예기치 못한 가동 중단을 억제하기 위해 자동화에 대한 투자를 추진하고 있습니다.
부문 분석
2025년, 영국의 파사드 시장에서 통기형 시스템은 시장 점유율의 45.32%를 차지했으며, 이 부문은 2031년까지 연평균 성장률(CAGR) 7.65%를 나타낼 것으로 예측됩니다. 이 시스템의 중공 구조는 화재 확산을 억제하고 열 조절 기능을 강화하며, 건축 안전법(Building Safety Act) 준수 및 넷 제로(Net Zero) 목표라는 현재 영국 파사드 시장의 거의 모든 입찰을 좌우하는 두 가지 우선 과제와 부합합니다. 이 기술은 seele사의 ‘ISOshade(R)’와 같은 스마트 모듈로 진화하고 있습니다. 이 제품은 내장 센서와 AI 제어 루버를 활용하여 능동적인 에너지 소비 없이 일사열 획득량을 조절합니다. 또한, VAT(부가가치세) 감면 조치와 보험상의 우대 조치를 활용하여 가연성 외장재를 대체하기 위해, 거주 중인 주거용 고층 빌딩에서의 통기형 개조 수요도 증가하고 있습니다. 보험사의 인수 기준이 엄격해지는 가운데, 개발업체들은 통기형 시스템을 단순한 업그레이드가 아닌 표준적인 솔루션으로 인식하기 시작했습니다.
2025년, 레인스크린 클래딩은 영국 파사드 시장 매출의 32.74%를 차지했으며, 그 범용성과 실적이 입증된 A1 등급 조립 구조가 높이 평가받았습니다. 그러나 유닛식 커튼월은 공장에서의 품질 관리와 영국 파사드 시장의 인력 부족을 해소하는 신속한 시공을 배경으로, 2031년까지 연평균 성장률(CAGR) 8.47%로 확대되고 있습니다. 각 제조업체들은 시스템 간의 경계를 모호하게 만들고 있으며, 유닛형 커튼월과 레인스크린을 결합한 하이브리드 솔루션은 레인스크린의 미적 자유도와 유닛형 패널의 시공 속도라는 장점을 모두 충족시킬 것으로 기대됩니다. 현재 대부분의 고층 건축 프로젝트에서 CWCT 인증 모형이 의무화되어 있으며, 최악의 하중 시나리오 하에서 유닛 조립체 전체를 시험할 수 있는 공급업체가 우대받고 있습니다. 모듈식 건축업체들이 베이 크기를 표준화함에 따라 유닛 패널이 기본 인터페이스로 자리 잡고 있습니다.
기타 혜택 :
- Excel 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, UK facade market size in 2026 is estimated at USD 10.99 billion, growing from 2025 value of USD 10.5 billion with 2031 projections showing USD 13.79 billion, growing at 4.63% CAGR over 2026-2031.
This report is Segmented by Type (Ventilated, Non-Ventilated, and Others), by Facade System Type (Rainscreen Cladding, and More), by Material (Glass, Metal, and More), by Installation (New Construction, Renovation & Retrofit), by End User (Commercial, Residential, and Others), and by Region (England, and More). The Market Forecasts are Provided in Terms of Value (USD).
UK Facade Market Trends and Insights
Post-Grenfell Recladding Surge
The Building Safety Act 2022 identified 5,052 residential blocks over 11 meters with unsafe cladding as of April 2025, with 2,477 already undergoing remediation . First-tier Tribunal rulings now deem even "medium" fire-risk ratings unacceptable, broadening liability exposure. Insurers are excluding combustible facades, effectively mandating A1-rated systems. VAT deductions on remediation work further lower upgrade costs. Established suppliers with certified, non-combustible portfolios are therefore capturing outsized demand.
Net-Zero 2050 Envelope Mandates
The Future Homes Standard, due in 2025, requires steep cuts in operational carbon, while London obliges whole-life carbon assessments for schemes above 1,000 m2. Research shows glass accounts for up to 60% of facade embodied carbon, prompting manufacturers to develop high-recycled-content glazing. Government recognition of data centers as nationally significant infrastructure is shortening planning timelines but tightening energy-performance criteria. Public-sector BREEAM "Excellent" thresholds now hinge on facade decarbonization, illustrated by Cardiff's Velindre Cancer Centre.
Aluminium & Glass Price Volatility
Energy-intensive aluminium smelting faces shifting supply dynamics and geopolitical trade risks that filter through to facade budgets. UK construction material indices recorded a 2.0% year-on-year decline as of June 2024, yet spot prices remain unstable, complicating cost planning for long-lead facade contracts. Flat-glass producers are investing in automation to curb unplanned downtime that can top GBP 1 million (USD 1.3501 million) per minute.
Other drivers and restraints analyzed in the detailed report include:
- Modular Off-Site Build Adoption
- Data-Center Build Boom
- Shortage of Certified Facade Labor
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ventilated systems accounted for 45.32% of UK facade market share in 2025, and the segment is set to grow at a 7.65% CAGR through 2031. Their cavity design limits fire propagation and enhances thermal regulation, aligning with Building Safety Act compliance and net-zero targets two priorities that now shape nearly every tender in the UK facade market. The technology is evolving toward smart modules such as seele's ISOshade(R), which uses embedded sensors and AI-driven louvers to modulate solar gain without active energy consumption. Demand is also rising for ventilated retrofits on occupied residential towers, leveraging VAT relief and insurance incentives to replace combustible cladding. As insurers tighten underwriting, developers increasingly view ventilated systems as the baseline solution rather than an upgrade.
Rainscreen cladding captured 32.74% of UK facade market revenue in 2025, reflecting its versatility and proven A1-rated assemblies. However, unitised curtain walls are advancing at an 8.47% CAGR to 2031, driven by factory-controlled quality and faster installation that counters labor shortages in the UK facade market. Manufacturers are blurring lines between systems; hybrid unitised-rainscreen solutions promise the aesthetic freedom of rainscreens with the speed advantages of unitised panels. CWCT-certified mock-ups are now mandatory on most high-rise projects, favoring suppliers that can test entire unitised assemblies under worst-case load scenarios. As modular builders standardize bay sizes, unitised panels are becoming the default interface.
Complete Report Scope:
- By Type
- Ventilated
- Non-Ventilated
- Others
- By Facade System Type
- Rainscreen Cladding
- Curtain-Wall Systems
- Others
- By Material
- Glass
- Metal
- Plastic & Fibres
- Stone
- Others
- By Installation
- New Construction
- Renovation & Retrofit
- By End-User
- Commercial
- Residential
- Others
- By Region
- England
- Scotland
- Wales
- Northern Ireland
List of Companies Covered in this Report:
- Schuco UK
- Permasteelisa UK
- Kingspan Insulated Panels UK
- Saint-Gobain Glass UK
- Reynaers Aluminium UK
- Kawneer UK
- AluK (GB) Ltd
- Senior Architectural Systems
- Yuanda Europe (UK)
- McMullen Facades
- Etex EOS Facades
- Sotech UK
- Prism Architectural
- Technal UK
- Alucraft Systems
- Vision Built UK
- Sto Ltd
- Glassolutions (Saint-Gobain)
- Fineline Aluminium
- OAG (Optima Architectural Glazing)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Post-Grenfell recladding surge
- 4.2.2 Net-zero 2050 envelope mandates
- 4.2.3 Modular off-site build adoption
- 4.2.4 Data-centre build boom
- 4.2.5 VAT relief energising BIPV facades
- 4.2.6 London "Retrofit First" policy
- 4.3 Market Restraints
- 4.3.1 Aluminium & glass price volatility
- 4.3.2 Shortage of certified facade labour
- 4.3.3 Insurance exclusions for combustible systems
- 4.3.4 Embodied-carbon caps (London Plan)
- 4.4 Brief on Different Structures Used in the Facades Industry
- 4.5 Pricing Analysis
- 4.6 Value / Supply-Chain Analysis
- 4.7 Regulatory Landscape
- 4.8 Technological Outlook
- 4.9 Porter's Five Forces
- 4.9.1 Bargaining Power of Suppliers
- 4.9.2 Bargaining Power of Consumers
- 4.9.3 Threat of New Entrants
- 4.9.4 Threat of Substitutes
- 4.9.5 Intensity of Competitive Rivalry
- 4.10 Consumer Behavior Analysis (Contractors, Architects, Developers, Individual Buyers, Facility & Property Managers/Building Owners)
- 4.11 Sustainability Trends
5 Market Size & Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Ventilated
- 5.1.2 Non-Ventilated
- 5.1.3 Others
- 5.2 By Facade System Type
- 5.2.1 Rainscreen Cladding
- 5.2.2 Curtain-Wall Systems
- 5.2.3 Others
- 5.3 By Material
- 5.3.1 Glass
- 5.3.2 Metal
- 5.3.3 Plastic & Fibres
- 5.3.4 Stone
- 5.3.5 Others
- 5.4 By Installation
- 5.4.1 New Construction
- 5.4.2 Renovation & Retrofit
- 5.5 By End-User
- 5.5.1 Commercial
- 5.5.2 Residential
- 5.5.3 Others
- 5.6 By Region
- 5.6.1 England
- 5.6.2 Scotland
- 5.6.3 Wales
- 5.6.4 Northern Ireland
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.4.1 Schuco UK
- 6.4.2 Permasteelisa UK
- 6.4.3 Kingspan Insulated Panels UK
- 6.4.4 Saint-Gobain Glass UK
- 6.4.5 Reynaers Aluminium UK
- 6.4.6 Kawneer UK
- 6.4.7 AluK (GB) Ltd
- 6.4.8 Senior Architectural Systems
- 6.4.9 Yuanda Europe (UK)
- 6.4.10 McMullen Facades
- 6.4.11 Etex EOS Facades
- 6.4.12 Sotech UK
- 6.4.13 Prism Architectural
- 6.4.14 Technal UK
- 6.4.15 Alucraft Systems
- 6.4.16 Vision Built UK
- 6.4.17 Sto Ltd
- 6.4.18 Glassolutions (Saint-Gobain)
- 6.4.19 Fineline Aluminium
- 6.4.20 OAG (Optima Architectural Glazing)
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


