|
시장보고서
상품코드
2125641
동남아시아의 압축천연가스(CNG) 디스펜서 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Southeast Asia Compressed Natural Gas (CNG) Dispenser - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
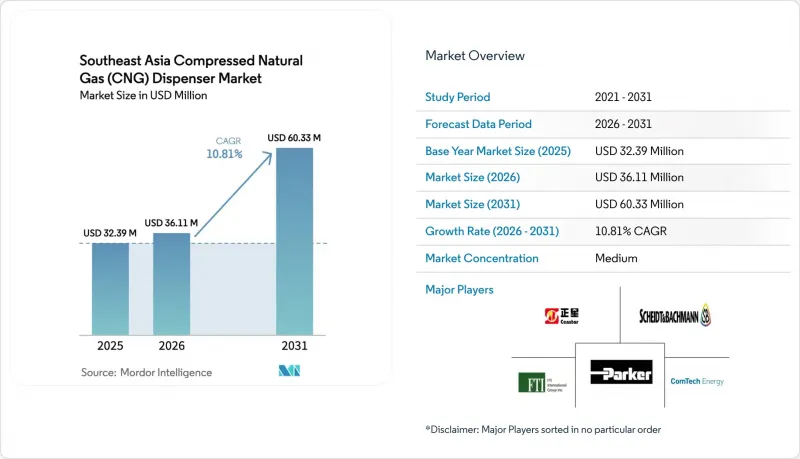
에 의하면, 동남아시아 압축천연가스(CNG) 디스펜서 시장 규모는 2025년에 3,239만 달러로 평가되었고 2026년 3,611만 달러에서 2031년까지 6,033만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 10.81%를 나타낼 전망입니다.
본 보고서는 디스펜서 구성(싱글 호스, 듀얼 호스, 멀티 호스),충전소의 유형(고속 충전, 시간제 충전, 이동식/휴대용), 최종 사용자(공공 소매 충전소, 민간 차량 기지, 대중교통 및 버스 차량, 산업·광업 시설), 그리고 지역(태국, 싱가포르, 인도네시아, 말레이시아, 필리핀, 베트남 및 동남아시아의 기타 지역)에 따라 분류되어 있습니다.
동남아시아 압축천연가스(CNG) 디스펜서 시장 동향 및 인사이트
디젤 연료에 비해 총 소유 비용(TCO)이 낮음
인도네시아 및 베트남의 차량 운영 사업자들은 2024년에 최고점에서 최저점까지 25%를 초과하는 디젤 가격 변동을 헤지하기 위해 5-7년간의 CNG 공급 계약을 체결했으며, 일일 150대 이상의 처리량 기준 정비 거점의 투자 회수 기간을 3.2년으로 단축했습니다. 펠타미나의 파이프라인 확장 이후, 자바섬 및 수마트라섬의 CNG 공급 비용은 18% 하락했으며, LNG 가격이 급등했을 때조차 디젤 연료 대비 30-40%의 운영 비용 격차가 고착화되었습니다. 베트남의 제조업체들도 이러한 추세를 반영하여, 2025년에는 민간 저장소가 전년 대비 22% 증가했습니다. 사업자들은 가동률이 60% 미만으로 떨어질 경우에만 해소되는 유지보수 및 엔진 수명 측면의 이점을 꼽고 있습니다. 따라서 동남아시아의 CNG 디스펜서 시장은 도시 지역의 일반 승용차가 아닌 대형 차량 플릿이 성장의 주축이 되고 있으며, 직접 가스 공급 계약을 통해 소매 가격 변동의 영향을 덜 받고 있습니다.
지역 내 LNG 수입 능력 확충
2023년부터 2025년까지 베트남의 카이멩 및 필리핀의 신규 터미널을 통해 연간 810만 톤의 재기화 용량이 추가되었습니다. 이에 따라 아시아태평양의 가격이 12달러/MMBtu 아래로 떨어질 경우, 충전소 운영 사업자는 현물 LNG 화물을 조달할 수 있게 되었습니다. 인도네시아의 국영 파이프라인 사업자는 중부 자바 및 남수마트라로 향하는 간선 파이프라인 부설을 추진하고 있으며, 이를 통해 ‘가상 파이프라인’으로서의 트럭 운송 비용을 절감하고 있습니다. 태국의 ‘동부 경제 회랑’에서는 소규모 위성 LNG 스테이션의 시범 운영이 진행되고 있으며, 한 곳당 설비 투자액이 200만 달러 미만으로 유지된다면 기존의 파이프라인 유통 체제에 타격을 줄 가능성이 있습니다. 그러나 싱가포르의 제2 터미널은 향후 10년 동안 완전 가동 수준에 도달하지 못할 전망이며, 싱가포르 사업자는 말레이시아로부터의 파이프라인 수입에 의존할 수밖에 없어 네트워크 확장도 제한될 것입니다.
배터리식 전기 모빌리티의 경쟁력 향상
방콕이 2025년에 발주한 500대의 배터리식 전기버스와 호치민시가 2025년 12월에 실시한 58대의 CNG 버스를 전기버스로 전환함에 따라, 도시 지역의 CNG 수요는 전년 대비 약 15% 감소했습니다. 말레이시아가 2025년 7월 4만 4,383대의 천연가스 차량(NGV)을 폐차하도록 의무화한 것은 정책에 따라 대상 시장이 급격히 축소될 수 있음을 보여줍니다. 대중교통 사업자들이 제로 배출 목표 달성을 추진하는 가운데, 도심 지역의 충전소 가동률은 손익분기점을 밑돌고 있으며, 일부 거점에서는 수소나 LPG로 전환할 수밖에 없는 상황입니다. 이에 따라 지역 공급업체들은 전기화의 영향을 덜 받는 산업 및 광업 고객을 대상으로 영업팀을 재배치하고 있습니다.
부문 분석
자카르타, 방콕, 호치민시의 사업자들이 3대 또는 4대의 차량에 동시에 연료를 공급할 수 있도록 구형 듀얼 호스식 충전소를 개조함에 따라, 멀티 호스식 설비가 동남아시아의 CNG 디스펜서 시장에서 점유율을 확대했습니다. 2025년 시점에서도 듀얼 호스식 유닛은 매출의 39.8%를 차지했으나, 멀티 호스식은 연평균 성장률(CAGR) 12.8%를 나타낼 것으로 예측됩니다. 이는 토지 제약으로 인해 1제곱미터당 처리 능력이 극히 중요해진 상황을 반영한 것입니다. 싱글 호스식 설비는 편의성이 속도보다 우선시되는 지방이나 교통량이 적은 차량 기지에서 여전히 사용되고 있지만, 지방 도시에서 서비스 수준에 관한 규제가 강화됨에 따라 그 점유율은 감소 추세를 보이고 있습니다.
각 제조업체는 현재 12개월마다 호스를 추가할 수 있는 모듈식 캐비닛을 제공하고 있으며, 이를 통해 설비 투자를 실제 수요에 맞추고 자산의 유휴화를 방지할 수 있게 되었습니다. ISO 19880 규격 준수를 반영함으로써, 최소한의 개조만으로 향후 수소 혼합 연료에 대응할 수 있게 되었으며, 이는 리스크 회피 성향이 강한 연료 소매업체들이 점점 더 요구하는 안전 장치로 자리 잡고 있습니다. 파커 허니핀(Parker Hannifin)과 길버코 비더 루트(Gilberco-Weider-Root)는 24시간 부품 지원과 초기 비용을 5년 서비스 계약에 분산시키는 소프트웨어 구독 모델을 결합하여 시장 점유율을 확대되고 있습니다. 중국의 신규 진출기업들은 가격 면에서 경쟁하고 있지만, 도시 지역의 고급 주유소에서는 이미지 격차에 직면하고 있어, 경쟁 압력은 시장을 불안정하게 할 정도는 아니며 적정한 수준에 머물고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the Southeast Asia compressed natural gas dispenser market size was valued at USD 32.39 million in 2025 and is estimated to grow from USD 36.11 million in 2026 to reach USD 60.33 million by 2031, at a CAGR of 10.81% during the forecast period (2026-2031).
This report is Segmented by Dispenser Configuration (Single-Hose, Dual-Hose, and Multi-Hose), Station Type (Fast-Fill, Time-Fill, and Mobile/Portable), End-User (Public Retail Stations, Private Fleet Depots, Transit and Bus Fleets, and Industrial and Mining Sites), and Geography (Thailand, Singapore, Indonesia, Malaysia, Philippines, Vietnam, and Rest of Southeast Asia).
Southeast Asia Compressed Natural Gas (CNG) Dispenser Market Trends and Insights
Lower Total Cost of Ownership vs Diesel
Fleet operators in Indonesia and Vietnam have locked in five-to-seven-year CNG supply contracts that hedge against diesel swings exceeding 25% peak-to-trough in 2024, reducing depot payback periods to 3.2 years at throughputs above 150 vehicles daily. Delivered CNG costs in Java and Sumatra fell 18% after Pertamina's pipeline extensions, cementing a 30-40% operating-cost gap versus diesel that persists even during LNG price spikes. Vietnamese manufacturers mirrored the shift as private depots grew 22% year-on-year in 2025, with operators citing maintenance and engine-life advantages that close only when utilization drops below 60%. The Southeast Asia CNG dispenser market, therefore, draws its core growth from heavy-duty fleets, not urban consumer vehicles, and is increasingly insulated from retail-price politics through direct gas-supply agreements.
Regional LNG Import Capacity Build-Out
Between 2023 and 2025, Vietnam's Cai Mep and the Philippines' new terminals added 8.1 million t p.a. of regasification, enabling station operators to source spot LNG cargoes when Asia-Pacific prices dip below USD 12/MMBtu. Indonesia's state pipeline operator is pushing trunk lines into Central Java and South Sumatra, cutting virtual-pipeline truck costs. Thailand's Eastern Economic Corridor pilots small-scale satellite LNG stations that could disrupt legacy pipeline distribution if capex falls beneath USD 2 million per site. Yet Singapore's second terminal will not reach full output this decade, leaving operators there exposed to Malaysian pipeline imports and limiting network expansion.
Rising Competitiveness of Battery-Electric Mobility
Bangkok's 2025 order for 500 battery-electric buses and Ho Chi Minh City's December 2025 conversion of 58 CNG buses to electric cut urban CNG demand by roughly 15% year-on-year. Malaysia's July 2025 mandate eliminating 44,383 NGVs showed that policy can abruptly shrink the addressable base. With public-transport operators chasing zero-emission targets, dispenser utilization in city cores has dipped below break-even, forcing some sites to pivot to hydrogen or LPG. Regional suppliers are therefore redirecting sales teams toward industrial and mining clients less vulnerable to electrification.
Other drivers and restraints analyzed in the detailed report include:
- Government NGV Incentives & Subsidies
- Adoption of IoT-Enabled Dispensers
- High Upfront Station CAPEX & Land-Leasing Hurdles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Multi-hose installations captured a rising share of the Southeast Asia CNG dispenser market as operators in Jakarta, Bangkok, and Ho Chi Minh City retrofit older dual-hose forecourts to serve three or four vehicles simultaneously. Dual-hose units still held 39.8% revenue in 2025, but multi-hose variants are projected to log a 12.8% CAGR, reflecting land constraints that make throughput per square meter critical. Single-hose equipment lingers in rural or low-traffic depots where simplicity trumps speed, although its share is ebbing as secondary cities tighten service-level rules.
Manufacturers now offer modular cabinets that add hoses in 12-month intervals, matching capex to realized demand and guarding against stranded assets. Integrating ISO 19880 compatibility prepares sites for future hydrogen blends with minimal retrofit, an insurance policy increasingly specified by risk-averse fuel retailers. Parker Hannifin and Gilbarco Veeder-Root have gained ground by bundling 24-hour parts support with software-subscription models that spread upfront costs across five-year service contracts. Chinese challengers compete on price but face perception gaps in premium urban stations, keeping competitive pressure moderate rather than destabilizing.
Complete Report Scope:
- By Dispenser Configuration
- Single-Hose
- Dual-Hose
- Multi-Hose
- By Station Type
- Fast-Fill
- Time-Fill
- Mobile/Portable
- By End-User
- Public Retail Stations
- Private Fleet Depots
- Transit and Bus Fleets
- Industrial and Mining Sites
- By Geography
- Thailand
- Singapore
- Indonesia
- Malaysia
- Philippines
- Vietnam
- Rest of Southeast Asia
List of Companies Covered in this Report:
- Parker Hannifin Corp
- Gilbarco Veeder-Root
- Censtar Science & Technology
- Tatsuno Corporation
- Scheidt & Bachmann
- Greka Engineering
- FTI International Group
- ComTech Energy
- Sanki Industry Group
- TGT Fuel Technologies India
- Compac Industries
- Tokheim Corporation
- ANGI Energy Systems
- WEH GmbH
- Linde Hydrogen & Gas Equipment
- Bosch Rexroth
- Chart Industries
- KwangShin Machine
- Armstrong Equipment
- Clean Energy Compression
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government NGV incentives & subsidy programs
- 4.2.2 Lower total cost of ownership vs gasoline & diesel
- 4.2.3 Growing city-bus fleet conversions to CNG
- 4.2.4 Regional pipeline & LNG import capacity build-out
- 4.2.5 Rapid biogas-to-CNG project roll-outs
- 4.2.6 Adoption of IoT-enabled dispensers for predictive maintenance
- 4.3 Market Restraints
- 4.3.1 Rising competitiveness of battery-electric mobility
- 4.3.2 High upfront station CAPEX & land-leasing hurdles
- 4.3.3 Volatility of LNG spot prices impacting CNG retail price
- 4.3.4 Urban zoning limits on high-pressure fueling facilities
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products & Services
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Dispenser Configuration
- 5.1.1 Single-Hose
- 5.1.2 Dual-Hose
- 5.1.3 Multi-Hose
- 5.2 By Station Type
- 5.2.1 Fast-Fill
- 5.2.2 Time-Fill
- 5.2.3 Mobile/Portable
- 5.3 By End-User
- 5.3.1 Public Retail Stations
- 5.3.2 Private Fleet Depots
- 5.3.3 Transit and Bus Fleets
- 5.3.4 Industrial and Mining Sites
- 5.4 By Geography
- 5.4.1 Thailand
- 5.4.2 Singapore
- 5.4.3 Indonesia
- 5.4.4 Malaysia
- 5.4.5 Philippines
- 5.4.6 Vietnam
- 5.4.7 Rest of Southeast Asia
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Parker Hannifin Corp
- 6.4.2 Gilbarco Veeder-Root
- 6.4.3 Censtar Science & Technology
- 6.4.4 Tatsuno Corporation
- 6.4.5 Scheidt & Bachmann
- 6.4.6 Greka Engineering
- 6.4.7 FTI International Group
- 6.4.8 ComTech Energy
- 6.4.9 Sanki Industry Group
- 6.4.10 TGT Fuel Technologies India
- 6.4.11 Compac Industries
- 6.4.12 Tokheim Corporation
- 6.4.13 ANGI Energy Systems
- 6.4.14 WEH GmbH
- 6.4.15 Linde Hydrogen & Gas Equipment
- 6.4.16 Bosch Rexroth
- 6.4.17 Chart Industries
- 6.4.18 KwangShin Machine
- 6.4.19 Armstrong Equipment
- 6.4.20 Clean Energy Compression
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment