|
시장보고서
상품코드
2125644
환경 컨설팅 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Environmental Consulting - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
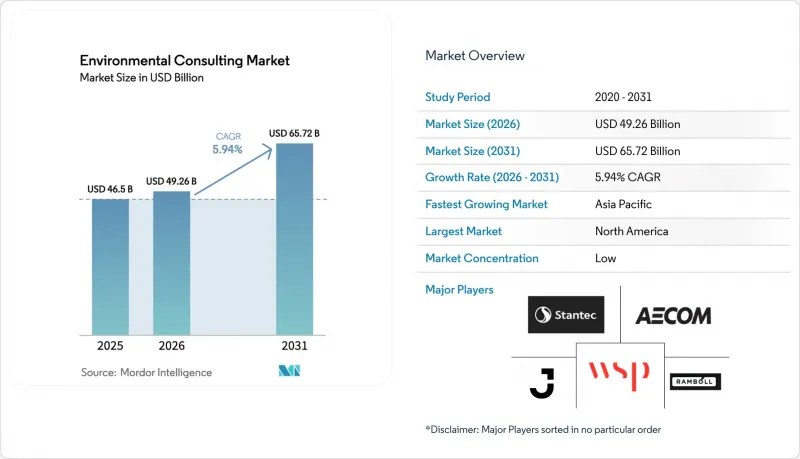
환경 컨설팅 시장 규모는 2025년에 465억 달러로 평가되었고, 2026년 492억 6,000만 달러에서 2031년까지 657억 2,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.94%를 나타낼 전망입니다.
본 보고서는 서비스 유형별(기후 변화 컨설팅, EHS, 환경영향 평가, 수자원·폐수 관리 등), 최종 사용자 산업별(에너지 및 전력, 광업 및 금속, 공공 부문, 제조업 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계의 환경 컨설팅 시장 동향 및 인사이트
OECD 및 G20 국가들의 기후 정책 준수 의무
기후 변화에 관한 규제의 통일화에 따라 컨설팅 수요는 일회성 프로젝트 업무가 아닌, 표준화되고 반복적으로 제공 가능한 서비스 라인으로 변화하고 있습니다. 업데이트된 OECD 환경 성과 검토(Environmental Performance Review)에서는 정량화된 탈탄소화 로드맵이 요구되고 있는 반면, 탄소 국경 조정 메커니즘(CBAM)의 도입으로 인해 국경을 넘는 공급망에 대한 검증 필요성이 대두되고 있습니다. 컨설팅 기업들은 여러 관할 구역에 걸쳐 단일 조사 기법을 적용함으로써 맞춤화 비용을 절감하고 고객 기반을 확대되고 있습니다. 규정 준수가 자발적인 것에서 의무적인 것으로 전환됨에 따라 서비스 파이프라인은 더욱 예측 가능해지고, 장기적인 자원 계획 및 디지털 제공 플랫폼에 대한 투자가 가능해집니다.
기업의 넷제로 및 ESG 공시 의무
EU의 ‘기업 지속가능성 보고 지침’은 2024년부터 5만 개 이상의 기업에 적용되며, 기존의 자발적 지침을 뛰어넘는 상세한 환경 정보 공개를 의무화하고 있습니다. 많은 기업은 사업 활동을 택소노미 기준에 맞추어 검토할 내부 전문 지식이 부족하여, 그 결과 자문 업무 수주가 수년 치나 밀려 있는 상황입니다. 미국 증권거래위원회(SEC) 및 기타 규제 당국이 검토 중인 유사한 규정으로 인해, 전 세계적으로 이와 유사한 수요 패턴이 확산되고 있습니다. 그 결과, 환경 컨설팅 시장의 관계는 단기적인 규정 준수 업무에서 시나리오 모델링 및 보증 대응 준비를 포함한 지속적인 전략적 파트너십으로 전환되고 있습니다.
기본 계약을 통한 지속적인 수수료 압박
기업 구매 측은 연간 비용 절감 조항이 포함된 다년 계약 하에 공급업체를 통합하고 있습니다. 일상적인 규정 준수 업무는 상품화가 진행되고 있어, 컨설턴트들은 PFAS(퍼플루오로알킬 물질) 정화나 ‘네이처 포지티브’ 회계와 같은 전문적이고 고부가가치의 틈새 분야로 사업을 다각화할 수밖에 없습니다. 대기업은 규모의 경제와 교차 판매를 활용하여 이익률을 지키려는 반면, 소규모 부티크 기업들은 독자적인 기술적 전문성을 무기로 프리미엄 요금을 책정하고 있습니다.
부문 분석
환경 영향 평가는 2025년에 환경 컨설팅 시장의 30.25%를 차지한 것으로 평가되었으며, 이는 모든 주요 경제권에서 프로젝트 인허가 취득에 있어 확고한 역할을 수행하고 있음을 반영합니다. 그 규모에도 불구하고, 표준화된 디지털 워크플로우로 인해 현장 작업 기간이 단축되면서 수수료 수준에 압박이 가해지고 있습니다. 반면, ESG 보고 및 지속가능성 전략은 프로젝트 단위가 아닌 지속적인 참여를 요구하는 공시 의무 규정에 힘입어 연평균 성장률(CAGR) 6.12%로 증가할 것으로 예측됩니다. 기후 변화 컨설팅 시장 규모는 전환 경로 모델링이 이사회 차원의 우선 과제가 됨에 따라 확대되고 있으며, 컨설턴트들은 자본 배분에 관한 전략적 자문가로서의 입지를 확고히 하고 있습니다.
상하수도 관리 분야는 인프라 부양책과 EPA의 납·구리 규제 개선과 같은 새로운 오염 물질 규제의 혜택을 받고 있으며, 이로 인해 2030년까지 450억 달러 규모의 대응 가능한 프로젝트가 창출될 것입니다. PFAS(퍼플루오로알킬 물질) 정화를 전문으로 하는 컨설턴트들은 수문지질학적 전문 지식과 고도의 처리 설계를 필요로 하는 복잡하고 수년에 걸친 프로젝트를 수주하고 있습니다. 한편, AI를 활용한 오염 부지 평가는 기존의 현장 조사를 단축하는 동시에, 데이터 분석 및 원격 감지 해석 분야에서 새로운 수익원을 개척하고 있습니다.
지역별 분석
북미는 2025년 환경 컨설팅 시장의 35.53% 점유율을 차지했으며, ‘국가환경정책법(NEPA)’ 등 성숙한 규제 체계를 바탕으로 영향 평가 및 정화에 대한 안정적인 수요를 뒷받침하고 있습니다. 연방 정부의 인프라 대책 패키지는 기후 변화 대응력 강화, 상수도 시스템 및 전력망 현대화에 초점을 맞춘 장기 프로젝트를 추가함으로써 수익 전망을 높이고 있습니다. 주 차원에서 부상하고 있는 기후 정보 공개 법안은 자문 프로젝트의 파이프라인을 더욱 확대되고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 6.31%로 지역 성장을 주도했습니다. 중국의 ‘생태환경법’ 초안은 분산되어 있던 규제를 통합하는 것으로, 산업 사업자들에게 표준화된 컨설팅 지원을 요구하도록 촉진하고 있습니다. 인도의 재생에너지 목표와 ‘메이크 인 인디아(Make in India)’ 정책에 따른 제조업 확대는 환경 허가 수요를 높이고 있는 반면, 동남아시아 국가들에서는 탄소 가격 책정 및 ESG 보고 체계가 도입되고 있습니다. 현지 규제에 정통하고 전 세계적인 기술 자원을 보유한 컨설팅 기업들이 선구자로서의 우위를 점하고 있습니다.
유럽에서는 수천 개 기업에 공시 의무를 제도화하는 ‘EU 택소노미’ 및 ‘기업 지속가능성 보고 지침’에 힘입어 견조한 활동이 유지되고 있습니다. 컨설팅 기업들은 유사한 프레임워크를 채택하는 관할 구역으로 자사의 경험을 확대하며, 유럽의 전문 지식을 세계 경쟁력 있는 자산으로 전환하고 있습니다. 중동 및 아프리카에서는 메가 프로젝트나 새로운 물 부족 대책과 관련하여 높은 성장이 예상되는 지역도 있지만, 규제 집행의 불균일성이 시장의 기세를 둔화시키고 있습니다. 라틴아메리카는 광업 투자 및 재생에너지 확장의 혜택을 받고 있지만, 정치적 불안정성과 허가 취득 기간의 장기화 문제에 계속해서 직면하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the environmental consulting market size was valued at USD 46.50 billion in 2025 and estimated to grow from USD 49.26 billion in 2026 to reach USD 65.72 billion by 2031, at a CAGR of 5.94% during the forecast period (2026-2031).
This report is Segmented by Service Type (Climate Change Consulting, EHS, Environmental Impact Assessment, Water and Wastewater Management, and More), End-User Industry (Energy and Power, Mining and Metals, Public Sector, Manufacturing, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Environmental Consulting Market Trends and Insights
Mandatory Climate-Policy Compliance in OECD and G20 Economies
Converging climate rules transform consulting demand into a standardized, repeatable service line rather than episodic project work. Updated OECD Environmental Performance Reviews require quantified decarbonization pathways, while carbon-border adjustment mechanisms introduce supply-chain verification needs that transcend national boundaries.Consulting firms deploy single methodological frameworks across multiple jurisdictions, lowering customization costs and enlarging their client base. As compliance shifts from voluntary to mandatory, service pipelines become more predictable, enabling long-term resource planning and investment in digital delivery platforms.
Corporate Net-Zero and ESG Disclosure Mandates
The EU Corporate Sustainability Reporting Directive applies to more than 50,000 companies starting in 2024, compelling detailed environmental disclosures that exceed prior voluntary guidelines. Many firms lack in-house expertise to map operations to taxonomy criteria, producing a multi-year backlog of advisory assignments. Similar rules under consideration by the U.S. Securities and Exchange Commission and other regulators extend the same demand pattern globally. Consequently, environmental consulting market relationships migrate from short-term compliance engagements to continuous strategic partnerships that include scenario modeling and assurance readiness.
Persistent Fee-Pressure from Framework Contracts
Corporate buyers consolidate vendors under multiyear frameworks that embed annual cost-down clauses. Routine compliance tasks become commoditized, forcing consultants to diversify toward specialized, high-value niches such as PFAS remediation or nature-positive accounting. Larger firms leverage scale and cross-selling to defend margins, whereas smaller boutiques rely on unique technical depth to command premium rates.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Green and Transition Bonds Requiring 3rd-Party Verification
- Industrial Decarbonization Funds Tied to Advisory Spend
- Delayed Permitting for Large Infrastructure in Emerging Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Environmental Impact Assessment captured 30.25% of the environmental consulting market in 2025, reflecting its entrenched role in project permitting across every major economy. Despite its scale, fee rates face pressure as standardized digital workflows shorten field programs. Conversely, ESG Reporting and Sustainability Strategy is forecast to increase at a 6.12% CAGR, propelled by mandatory disclosure rules that necessitate continuous rather than project-based engagement. The environmental consulting market size for climate-change consulting accelerates as transition pathway modeling becomes a board-level priority, positioning consultants as strategic advisors on capital allocation.
Water and wastewater management benefits from infrastructure stimulus and new contaminant regulations such as the EPA Lead and Copper Rule Improvements, which unlock USD 45 billion of addressable projects through 2030. Consultants specializing in PFAS remediation secure complex, multi-year assignments requiring hydrogeological expertise and advanced treatment design. Meanwhile, AI-driven contaminated-site assessment compresses traditional fieldwork yet opens new revenue streams in data analytics and remote sensing interpretation.
Complete Report Scope:
- By Service Type
- Climate Change Consulting
- EHS
- Environmental Impact Assessment
- Water and Wastewater Management
- ESG Reporting and Sustainability Strategy
- Other Service Types (Includes Contaminated Site Assessment)
- By End-User Industry
- Energy and Power
- Mining and Metals
- Public Sector
- Manufacturing
- Pharmaceuticals
- Other End-user Industries (Construction and Infrastructure, Transportation, etc.)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Poland
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 35.53% of environmental consulting market share in 2025, leveraging mature rules such as the National Environmental Policy Act that underpin steady demand for impact assessments and remediation. Federal infrastructure packages add long-cycle projects focused on climate resilience, water systems, and grid renewal, enhancing revenue visibility. Emerging state-level climate disclosure bills further amplify advisory pipelines.
Asia-Pacific leads regional growth at a 6.31% CAGR through 2031. China's draft Ecological and Environmental Code consolidates fragmented regulations, compelling industrial operators to seek standardized consulting support. India's renewable-energy targets and Make-in-India manufacturing expansion elevate demand for environmental permitting, while Southeast Asian countries adopt carbon-pricing and ESG reporting frameworks. Consultants with local regulatory fluency and global technical resources gain first-mover advantage.
Europe maintains robust activity through the EU Taxonomy and Corporate Sustainability Reporting Directive, which institutionalize disclosure obligations for thousands of firms. Consultants export their experience to jurisdictions adopting similar frameworks, transforming European expertise into a global competitive asset. Middle East and Africa present pockets of high growth tied to megaprojects and emerging water scarcity solutions, though uneven regulatory enforcement tempers market velocity. Latin America benefits from mining investments and renewable build-out but continues to battle political volatility and elongated permitting.
- Jacobs Solutions Inc.
- AECOM
- WSP Global Inc.
- Tetra Tech, Inc.
- Stantec Inc.
- Ramboll Group A/S
- ERM International Group Limited
- Arup Group Limited
- GHD Group Pty Ltd
- Sweco AB
- Arcadis N.V.
- John Wood Group PLC (Wood)
- SNC-Lavalin Group Inc. (AtkinsRealis)
- HDR, Inc.
- SLR Consulting Limited
- Antea Group N.V.
- Mott MacDonald Group Limited
- Montrose Environmental Group, Inc.
- Brown and Caldwell, Inc.
- Worley Limited
- ICF International, Inc.
- EA Engineering, Science, and Technology, Inc., PBC
- Cardno Limited
- Golder Associates Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Mandatory Climate-Policy Compliance in OECD and G20 Economies
- 4.2.2 Corporate Net-Zero and ESG Disclosure Mandates
- 4.2.3 Growth of Green and Transition Bonds Requiring 3rd-Party Verification
- 4.2.4 Industrial Decarbonisation Funds Tied to Advisory Spend
- 4.2.5 AI-Enabled Rapid Site-Characterisation Tools Cut Due-Diligence Time
- 4.2.6 "Nature-Positive" Impact Accounting Frameworks Emerge
- 4.3 Market Restraints
- 4.3.1 Persistent Fee-Pressure from Framework Contracts
- 4.3.2 Delayed Permitting for Large Infrastructure in Emerging Markets
- 4.3.3 Scarcity of Licensed Hydro-geologists and Toxicologists
- 4.3.4 Client Shift to In-House Digital EHS Platforms
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Bargaining Power of Buyers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Impact of Macroeconomic Shocks
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Climate Change Consulting
- 5.1.2 EHS
- 5.1.3 Environmental Impact Assessment
- 5.1.4 Water and Wastewater Management
- 5.1.5 ESG Reporting and Sustainability Strategy
- 5.1.6 Other Service Types (Includes Contaminated Site Assessment)
- 5.2 By End-User Industry
- 5.2.1 Energy and Power
- 5.2.2 Mining and Metals
- 5.2.3 Public Sector
- 5.2.4 Manufacturing
- 5.2.5 Pharmaceuticals
- 5.2.6 Other End-user Industries (Construction and Infrastructure, Transportation, etc.)
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 South America
- 5.3.2.1 Brazil
- 5.3.2.2 Argentina
- 5.3.2.3 Rest of South America
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Poland
- 5.3.3.7 Russia
- 5.3.3.8 Rest of Europe
- 5.3.4 Asia Pacific
- 5.3.4.1 China
- 5.3.4.2 India
- 5.3.4.3 Japan
- 5.3.4.4 South Korea
- 5.3.4.5 Australia
- 5.3.4.6 Rest of Asia Pacific
- 5.3.5 Middle East and Africa
- 5.3.5.1 Middle East
- 5.3.5.1.1 Saudi Arabia
- 5.3.5.1.2 United Arab Emirates
- 5.3.5.1.3 Turkey
- 5.3.5.1.4 Rest of Middle East
- 5.3.5.2 Africa
- 5.3.5.2.1 South Africa
- 5.3.5.2.2 Nigeria
- 5.3.5.2.3 Egypt
- 5.3.5.2.4 Rest of Africa
- 5.3.5.1 Middle East
- 5.3.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Jacobs Solutions Inc.
- 6.4.2 AECOM
- 6.4.3 WSP Global Inc.
- 6.4.4 Tetra Tech, Inc.
- 6.4.5 Stantec Inc.
- 6.4.6 Ramboll Group A/S
- 6.4.7 ERM International Group Limited
- 6.4.8 Arup Group Limited
- 6.4.9 GHD Group Pty Ltd
- 6.4.10 Sweco AB
- 6.4.11 Arcadis N.V.
- 6.4.12 John Wood Group PLC (Wood)
- 6.4.13 SNC-Lavalin Group Inc. (AtkinsRealis)
- 6.4.14 HDR, Inc.
- 6.4.15 SLR Consulting Limited
- 6.4.16 Antea Group N.V.
- 6.4.17 Mott MacDonald Group Limited
- 6.4.18 Montrose Environmental Group, Inc.
- 6.4.19 Brown and Caldwell, Inc.
- 6.4.20 Worley Limited
- 6.4.21 ICF International, Inc.
- 6.4.22 EA Engineering, Science, and Technology, Inc., PBC
- 6.4.23 Cardno Limited
- 6.4.24 Golder Associates Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment