

|
시장보고서
상품코드
2125670
프라이빗 제트 차터 서비스 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Private Jet Charter Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
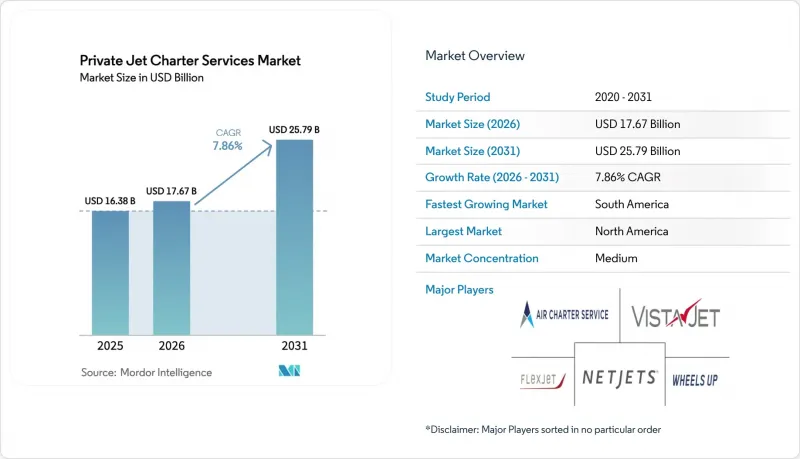
프라이빗 제트 차터 서비스 시장 규모는 2025년에 163억 8,000만 달러로 평가되었고, 2026년 176억 7,000만 달러에서 2031년까지 257억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 7.86%를 나타낼 전망입니다.
본 보고서는 항공기 크기별(소형, 중형, 대형), 서비스 모델별(주문형 전세기, 제트 카드 회원제, 구독형 전세기 등), 비행 유형별(국내선 및 국제선), 최종 사용자별(대기업 및 중소기업, 고소득층/개인 등), 지역별(북미, 유럽 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 프라이빗 제트 차터 서비스 시장 동향 및 인사이트
전 세계 초고액 자산가(UHNWI) 증가세가 가속화되고 있습니다.
2025년에는 전 세계 초부유층 인구가 62만 5,000명을 넘어 30조 달러의 자산을 보유하게 되었으며, 연간 4%의 속도로 확대되고 있습니다. 중국과 인도의 부유층 증가로 인해 아시아가 프라이빗 제트 차터 서비스 시장에서 차지하는 비중이 높아지고 있습니다. 이는 젊은 부유층 여행자들이 물질적인 사치보다 몰입형 경험을 중시하기 때문입니다. 기업 임원들은 빡빡한 일정과 라이프스타일 선택을 양립시키기 위해 지점 간 이동 수단을 활용하고 있으며, 사설 항공은 생산성 향상을 위한 도구로 자리 잡고 있습니다. 부유층의 거점이 다양해지는 인구 통계학적 변화는 동남아시아와 중동의 새로운 수요를 뒷받침하고 있습니다. 그 결과, 현재의 항공기 운용 전략은 대륙 간 이동을 위한 장거리 제트기와 국내 이동을 목적으로 하는 라이트 제트기 간의 균형을 맞추고 있으며, 이를 통해 사업자들은 프라이빗 제트 차터 서비스 시장에서의 점유율 확대를 도모하고 있습니다.
팬데믹 이후 유연한 여행 수단에 대한 수요 증가
상업 항공이 완전히 회복되었음에도 불구하고, 2025년 중반까지 비즈니스 제트기 이용률은 2019년 수준을 10% 상회하고 있습니다. 팬데믹을 계기로 수천 명의 신규 이용자가 프라이빗 제트를 이용하기 시작했으며, 혼잡한 허브 공항에서의 노출을 최소화하고 맞춤형 여정을 중시하는 여행객들 덕분에 재이용률도 견조한 추세를 보이고 있습니다. 카리브해 리조트 여행 등 북미의 레저 여행 일정이 현저히 증가했습니다. 유럽의 전세 항공 이용 패턴은 기업용과 레저용 두 부문이 혼재되어 있으며, 많은 경우 지방 공항에도 착륙 가능한 소형 또는 중형 항공기가 이용되고 있습니다. 중동에서는 비즈니스 제트기 교통량이 2019년 대비 2배 이상 증가했으며, 이는 해당 지역이 유럽, 아프리카, 아시아를 잇는 요충지로서의 위상을 반영하고 있습니다. 이러한 변화가 이용률을 뒷받침하며, 프라이빗 제트 차터 서비스 시장에서 기단을 확충하는 사업자들의 낙관적인 전망을 뒷받침하고 있습니다.
급등하는 운영비와 전세기 요금에 대한 압박
보험, 승무원, 정비에 드는 지출은 계속 증가하고 있어, 재무 기반이 취약한 운항 사업자들의 이익률을 압박하고 있습니다. 항공기 보험 및 배상 책임 보험의 연간 보험료는 항공기 가치와 조종사의 경력에 따라 1만 달러에서 50만 달러 범위 내에서 변동하며, 기상 조건으로 인한 보험금 청구가 가격 변동성을 더욱 높이고 있습니다. 공급망 혼란으로 인해 항공기 가동 중단 기간이 길어지면서 전세기 대체 비용이 증가하고 있습니다. 제트 연료 가격은 여전히 지정학적 사건의 영향을 받기 쉬워, 사업자가 장기적인 가격을 고정하는 능력을 제한하고 있습니다. 경쟁력을 유지하기 위해 시장을 선도하는 기업들은 수량 할인을 협상하거나, 예정에 없던 수리를 줄여주는 예측 유지보수 시스템을 구형 항공기에 사후 장착하고 있지만, 비용 구조가 여전히 높은 수준을 유지함에 따라 프라이빗 제트 차터 서비스 시장의 단기적인 가격 책정 유연성은 여전히 제약을 받고 있습니다.
부문 분석
2025년, 대형 제트기는 프라이빗 제트 차터 서비스 시장 매출의 52.74%를 차지했습니다. 이는 대륙 간 비행이 가능한 항속 거리와 기업 의전에 부합하는 널찍한 객실이 높이 평가받았기 때문입니다. 기체 데이터에 따르면, 소유주들이 속도, 쾌적성, 그리고 뉴욕에서 도쿄로 가는 직항편을 원하고 있기 때문에 넓은 객실을 갖춘 모델이 신규 인도에 대한 설비 투자의 약 3분의 2를 차지하는 것으로 확인되었습니다. 한편, 라이트 제트 부문의 프라이빗 제트 차터 서비스 시장 규모는 2026-2031년 연평균 성장률(CAGR) 7.92%로 확대될 것으로 예측됩니다. 이는 ‘페놈 300’이나 ‘사이테이션 CJ3 Gen2’와 같은 비용 효율성이 뛰어난 기체가 지방의 경영진이나 의료 이송 사업자에게도 프라이빗 항공 이용을 가능하게 하고 있기 때문입니다.
기단 현대화 프로그램은 성능과 지속가능성으로의 전환을 강조하고 있습니다. 하네웰(Honeywell)은 2035년까지 8,500대의 새로운 비즈니스 제트기가 인도될 것이며, 그 총액은 2,800억 달러에 달할 것으로 예측하고 있으며, 그중 66%를 북미가 차지할 것으로 전망됩니다. Wheels Up과 같은 운항사는 구형 터보프롭기를 퇴역시키고 두 가지 제트기 제품군으로 표준화함으로써 기단의 복잡성을 줄이고, 유지비 절감 및 승무원 일정 관리의 간소화를 도모했습니다. 2025년에 취항하는 라이트 제트기는 지속가능한 항공 연료(SAF)를 지원하도록 도입되어 환경 규제를 준수하는 동시에, 처음으로 전세기를 이용하는 고객층으로의 보급을 촉진하고 있습니다. 이러한 이중 수요 곡선은 프라이빗 제트 전세기 서비스 시장에서 각 크기 카테고리 간의 균형 잡힌 성장을 뒷받침하고 있습니다.
2025년에는 온디맨드 항공편이 프라이빗 제트 전세기 서비스 시장 매출의 51.62%를 차지한 것으로 평가되었으며, 이는 갑작스러운 임원 출장이나 특별 행사 시 유연한 예약에 대한 의존도를 반영한 것입니다. 기업의 항공 부문은 장기 계약에 얽매이지 않고 항공기를 유연하게 활용함으로써 대차대조표상의 위험을 최소화하고 있습니다. 아직 발전 단계에 있지만, 구독 모델은 고객이 이용 보장, 가격 확실성, 로열티 크레딧을 중요시함에 따라 2031년까지 연평균 성장률(CAGR) 9.63%를 나타낼 것으로 예측됩니다.
제트 카드는 일회성 이용형과 프랙셔널 프로그램의 중간에 위치하며, 이월이 가능한 예치금과 투명성이 높은 시간당 단가를 제공합니다. 엠티 레그 마켓플레이스는 본래 유휴 상태가 되는 재배치 항공편을 상품화하여 시간당 단가를 절감하는 동시에 새로운 수요를 창출하고 있습니다. 셰어드 시트 사업자는 라운지에서의 사생활 보호와 유연한 출발 시간대를 원하며, 일반 항공 운임보다 높은 요금을 지불할 의사가 있는 레저 고객층을 타겟으로 하고 있습니다. 가격 책정 알고리즘이 성숙해짐에 따라, 사업자들은 세분화를 정교화하여 니치 시장을 포착하고, 지속적인 수익원을 강화하는 동시에 프라이빗 제트 차터 서비스 시장 규모 다변화를 도모하고 있습니다.
지역별 분석
북미는 5,000대를 넘는 항공기 수, 밀집된 FBO 네트워크, 그리고 유리한 감가상각 제도 덕분에 2025년에도 매출의 81.93%를 차지하며 주도적인 위치를 유지했습니다. 미국에는 세계에서 가장 밀집된 초고액 자산가(UHNWI)가 거주하고 있으며, 이는 국내 및 대서양 횡단 노선의 안정적인 수요로 이어지고 있습니다. 캐나다와 멕시코는 자원 부문 관련 출장 및 관광 흐름을 통해 수요 증가에 기여하고 있습니다. USMCA(미국·멕시코·캐나다 협정)에 따른 노선 자유화는 국경을 초월한 원활한 운항 일정을 가능하게 하여, 프라이빗 제트 차터 서비스 시장에서 이 지역의 주도적 지위를 공고히 하고 있습니다.
유럽은 탄소세 및 지속가능 항공연료(SAF) 의무화가 강화되고 있음에도 불구하고 견조한 모습을 유지하고 있습니다. 영국, 프랑스, 독일은 여전히 주요 허브이며, 런던의 비긴 힐과 파리의 르 부르제에서는 팬데믹 이전의 최고치를 웃도는 이용률이 보고되고 있습니다. 각 항공사는 ReFuelEU 기준치 하에서 슬롯 이용권을 확보하기 위해 항공기에 SAF 대응 엔진을 사후 장착하고 있습니다. 이를 통해 규정 준수 비용이 상승하는 상황에서도 프라이빗 제트 전세기 서비스 시장에서의 점유율을 유지할 수 있게 되었습니다. 동유럽에서는 부의 축적이 기존의 수도권 이외의 지역으로 확대되고 있어 잠재적 수요가 축적되고 있습니다.
남미는 9.78%의 예측 연평균 성장률(CAGR)을 보이고 있으며, 이 지역은 가장 빠르게 확장되는 성장 기회의 거점으로 자리매김하고 있습니다. 브라질은 인프라 투자를 주도하며 캄피나스나 고이아니아와 같은 지방 공항의 현대화를 추진하고 있으며, 이로 인해 상파울루 콩고냐스 공항의 혼잡도에 대한 의존도가 낮아지고 있습니다. 아르헨티나의 광업 프로젝트와 콜롬비아의 기술 분야에 대한 투자가 도시 간 에어택시 수요를 뒷받침하고 있습니다. 환율 변동과 복잡한 규제는 여전히 장벽으로 작용하고 있지만, 수요의 펀더멘털은 미개척 시장의 성장을 추구하는 전 세계 항공사들 시장 진입을 뒷받침하고 있습니다.
아시아태평양의 전망은 엇갈리고 있습니다. 중국의 규제 강화로 인해 2024년 국내 전세편 운항은 둔화되었으나, 해외 레저 수요가 싱가포르, 푸켓, 몰디브행 항공편을 견인하고 있습니다. 인도네시아, 베트남, 필리핀에서는 제조 거점이 세계 밸류체인에 더욱 깊이 통합됨에 따라 비즈니스 제트기 이용이 두 자릿수 성장세를 보이고 있습니다. 호주에서는 자원 부문의 셔틀 노선 덕분에 수요가 안정적입니다. 중동 및 아프리카은 풍부한 천연자원과 관광 주도형 경제 다각화를 동시에 갖추고 있습니다. 사우디아라비아의 ‘비전 2030’에 따라 리야드의 킹 살만 국제공항에 대한 투자가 촉진되면서, 개인 전용기 전세 서비스 시장에서 지역 간 협력이 강화되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the private jet charter services market size was valued at USD 16.38 billion in 2025 and estimated to grow from USD 17.67 billion in 2026 to reach USD 25.79 billion by 2031, at a CAGR of 7.86% during the forecast period (2026-2031).
This report is Segmented by Aircraft Size (Light, Mid-Size, and Large), Service Model (On-Demand Charter, Jet Card Membership, Subscription-Based Charter, and More), Flight Type (Domestic and International), End User (Corporates and SMEs, HNWI/Private Individuals, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD)
Global Private Jet Charter Services Market Trends and Insights
Accelerating growth in global ultra-high-net-worth individuals (UHNWIs)
The wealthy population surpassed 625,000 people worldwide in 2025, controlling assets of USD 30 trillion and expanding 4% yearly. Rising affluence in China and India strengthens Asia's contribution to the private jet charter services market as younger high-net-worth travelers prioritize immersive experiences over material goods. Corporate executives use point-to-point connectivity to reconcile intense schedules with lifestyle choices, turning private aviation into a productivity tool. The demographic shift toward diversified wealth centers supports fresh demand in Southeast Asia and the Middle East. Consequently, fleet strategies now balance long-range jets for transcontinental journeys with light jets aimed at domestic connectivity, helping operators capture incremental share in the private jet charter services market.
Heightened demand for flexible, post-pandemic travel alternatives
Business jet activity re mained 10% above 2019 levels through mid-2025, despite commercial aviation's full recovery. The pandemic introduced thousands of first-time users to private flying, and retention has proven strong as travelers value minimal exposure to congested hubs and tailored itineraries. North American leisure itineraries, such as Caribbean resort hops, noticeably increased. European charter patterns blend corporate and leisure segments, often on light or mid-size aircraft that can land at secondary airports. In the Middle East, business jet traffic has more than doubled from 2019, reflecting the region's status as a connector between Europe, Africa, and Asia. These shifts sustain utilization rates and underpin optimism among operators expanding fleets inside the private jet charter services market.
Escalating operating expenses and charter pricing pressures
Insurance, crew, and maintenance outlays continue to rise, squeezing margins for operators with smaller balanced sheets. Annual hull and liability premiums range from USD 10,000 to USD 500,000, depending on aircraft value and pilot experience, and weather-related claims drive further pricing volatility. Supply chain disruptions extend aircraft downtime, increasing charter-substitution costs. Jet fuel prices remain sensitive to geopolitical events, limiting operators' ability to lock long-term rates. To remain competitive, market leaders negotiate volume discounts and retrofit older aircraft with predictive-maintenance systems that reduce unscheduled repairs, yet elevated cost structures still restrain near-term pricing flexibility in the private jet charter services market.
Other drivers and restraints analyzed in the detailed report include:
- Proliferation of jet-card, subscription, and membership models
- Adoption of AI-enabled real-time pricing and booking algorithms
- Stricter environmental compliance mandates and expanding carbon levies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Large jets contributed 52.74% of the private jet charter services market revenue in 2025, favored for intercontinental range and spacious cabins that match corporate protocols. Fleet data confirms that heavy-cabin models capture roughly two-thirds of capital expenditure in new deliveries, as owners seek speed, comfort, and nonstop reach from New York to Tokyo. The private jet charter services market size for light-jets, however, is projected to grow at a 7.92% CAGR between 2026 and 2031 as cost-efficient airframes like the Phenom 300 and Citation CJ3 Gen2 open private aviation to regional executives and medical-evacuation providers.
Fleet modernization programs underscore a shift toward performance and sustainability. Honeywell forecasts 8,500 new business jet deliveries worth USD 280 billion by 2035, with North America absorbing 66% of shipments. Operators such as Wheels Up trimmed fleet complexity by retiring older turboprops and standardizing on two jet families to lower maintenance expenses and simplify crew scheduling. Light-jet models entering service in 2025 arrive SAF-ready, aligning with environmental mandates and encouraging adoption among first-time charter clients. This dual demand curve reinforces balanced growth across size categories within the private jet charter services market.
On-demand trips generated 51.62% of the private jet charter services market revenue 2025, reflecting reliance on flexible arrangements for last-minute executive travel and special events. Corporate flight departments use aircraft interchangeably without long-term contractual lock-in, minimizing balance-sheet exposure. Though still emerging, subscription models are expected to record a 9.63% CAGR through 2031 as clients value guaranteed availability, price certainty, and loyalty credits.
Jet cards position themselves between ad-hoc and fractional programs, offering deposits that roll over and transparent hourly rates. Empty-leg marketplaces commoditize otherwise idle repositioning flights, slicing hourly costs, and feeding new traffic. Shared-seat operators target leisure groups willing to pay above commercial fares for lounge privacy and flexible departure windows. As pricing algorithms mature, operators refine segmentation to capture demand pockets, fortifying recurring-revenue pipelines and diversifying the private jet charter services market size streams.
Complete Report Scope:
- By Aircraft Size
- Light
- Mid-size
- Large
- By Service Model
- On-Demand Charter
- Jet Card Membership
- Subscription-based Charter
- Fractional Charter Integration
- Empty-Leg/Shared Charter
- By Flight Type
- Domestic
- Short Haul
- Long Haul
- International
- Short Haul
- Long Haul
- Domestic
- By End User
- Corporates and SMEs
- HNWI/Private Individuals
- Sports and Entertainment
- Government and NGO
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained 81.93% revenue dominance in 2025 due to a 5,000-plus fleet, dense FBO networks, and favorable depreciation allowances. The United States houses the most concentrated UHNWI base globally, translating into consistent domestic and trans-Atlantic flight demand. Canada and Mexico contribute incremental volumes through resource-sector travel and tourism flows. Route liberalization under the USMCA supports seamless cross-border scheduling, cementing regional leadership in the private jet charter services market.
Europe stays resilient despite intensifying carbon levies and SAF mandates. The United Kingdom, France, and Germany remain the primary hubs, with London Biggin Hill and Paris Le Bourget reporting utilization above pre-pandemic peaks. Operators retrofit fleets with SAF-compatible engines to safeguard slot access under ReFuelEU thresholds. This allows them to preserve their share in the private jet charter services market size even as compliance costs rise. Eastern Europe exhibits pent-up potential as wealth accumulation spreads beyond legacy capitals.
South America's 9.78% forecasted CAGR positions the region as the fastest-expanding pocket of opportunity. Brazil spearheads infrastructure spending, modernizing secondary airports such as Campinas and Goiania, which reduces reliance on Sao Paulo Congonhas congestion. Argentine mining projects and Colombian tech investments fuel inter-city air-taxi requirements. Currency volatility and regulatory complexity remain obstacles, yet demand fundamentals support commitment from global operators seeking white-space growth.
Asia-Pacific presents a mixed outlook. China's regulatory tightening cooled domestic charter activity in 2024, yet outbound leisure traffic pushes flights to Singapore, Phuket, and the Maldives. Indonesia, Vietnam, and the Philippines witness double-digit business-jet traffic expansion as manufacturing hubs integrate deeper into global value chains. Australia maintains a stable demand through resource-sector shuttle work. Middle East and Africa combine natural-resource wealth and tourism-led diversification; Saudi Arabia's Vision 2030 funnels investment into Riyadh's King Salman International Airport, strengthening regional linkage within the private jet charter services market.
- NETJETS IP, LLC
- Flexjet LLC
- VistaJet Group Holding Limited
- Wheels Up Experience Inc.
- flyExclusive
- XO Global LLC
- Jet Linx Aviation, LLC
- GAMA Aviation Plc
- Air Charter Service Group Limited
- PrivateFly Limited
- Sentient Jet
- Paramount Business Jets
- GlobeAir AG
- Luxaviation Group
- Jetex FZE
- RoyalJet Group
- DeerJet
- Club One Air
- Metrojet Limited
- Executive Jets Asia Pte. Ltd.
- Magellan Jets
- FXAIR
- Flapper Technologia S.A.
- Global Jet Centre
- Insijets Ltd.
- OJets Pte. Ltd.
- Jettly Inc.
- Prime Jet LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating growth in global ultra-high-net-worth individuals (UHNWIs)
- 4.2.2 Heightened demand for flexible, post-pandemic travel alternatives
- 4.2.3 Proliferation of jet-card, subscription, and membership models
- 4.2.4 Adoption of AI-enabled real-time pricing and booking algorithms
- 4.2.5 Increasing client preference for sustainable aviation fuel (SAF)-compatible charters
- 4.2.6 Expansion of secondary airports and FBO infrastructure across emerging markets
- 4.3 Market Restraints
- 4.3.1 Escalating operating expenses and charter pricing pressures
- 4.3.2 Stricter environmental compliance mandates and expanding carbon levies
- 4.3.3 Growing shortage of qualified business-aviation flight crews
- 4.3.4 Upward spiral in aviation-insurance premiums following safety incidents
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Aircraft Size
- 5.1.1 Light
- 5.1.2 Mid-size
- 5.1.3 Large
- 5.2 By Service Model
- 5.2.1 On-Demand Charter
- 5.2.2 Jet Card Membership
- 5.2.3 Subscription-based Charter
- 5.2.4 Fractional Charter Integration
- 5.2.5 Empty-Leg/Shared Charter
- 5.3 By Flight Type
- 5.3.1 Domestic
- 5.3.1.1 Short Haul
- 5.3.1.2 Long Haul
- 5.3.2 International
- 5.3.2.1 Short Haul
- 5.3.2.2 Long Haul
- 5.3.1 Domestic
- 5.4 By End User
- 5.4.1 Corporates and SMEs
- 5.4.2 HNWI/Private Individuals
- 5.4.3 Sports and Entertainment
- 5.4.4 Government and NGO
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Spain
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 NETJETS IP, LLC
- 6.4.2 Flexjet LLC
- 6.4.3 VistaJet Group Holding Limited
- 6.4.4 Wheels Up Experience Inc.
- 6.4.5 flyExclusive
- 6.4.6 XO Global LLC
- 6.4.7 Jet Linx Aviation, LLC
- 6.4.8 GAMA Aviation Plc
- 6.4.9 Air Charter Service Group Limited
- 6.4.10 PrivateFly Limited
- 6.4.11 Sentient Jet
- 6.4.12 Paramount Business Jets
- 6.4.13 GlobeAir AG
- 6.4.14 Luxaviation Group
- 6.4.15 Jetex FZE
- 6.4.16 RoyalJet Group
- 6.4.17 DeerJet
- 6.4.18 Club One Air
- 6.4.19 Metrojet Limited
- 6.4.20 Executive Jets Asia Pte. Ltd.
- 6.4.21 Magellan Jets
- 6.4.22 FXAIR
- 6.4.23 Flapper Technologia S.A.
- 6.4.24 Global Jet Centre
- 6.4.25 Insijets Ltd.
- 6.4.26 OJets Pte. Ltd.
- 6.4.27 Jettly Inc.
- 6.4.28 Prime Jet LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


