

|
시장보고서
상품코드
2125710
카운터톱 제빙기 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Countertop Ice Makers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
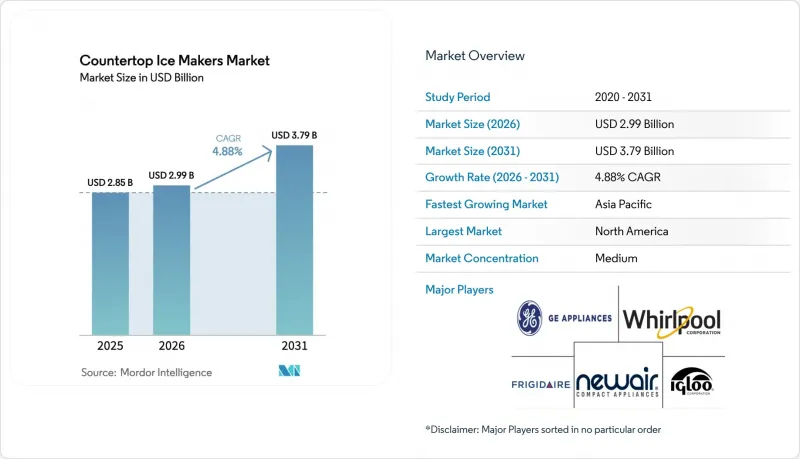
에 의하면, 카운터톱 제빙기 시장 규모는 2025년에 28억 5,000만 달러로 평가되었고, 2026년 29억 9,000만 달러에서 2031년까지 37억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.88%를 나타낼 전망입니다.

본 보고서에서는 제품 유형별(탄환형 제빙기, 너겟형 제빙기, 기타), 생산 능력별(일일 26파운드 이하, 일일 26-40파운드, 일일 40파운드 이상), 최종 사용자별(가정용 및 상업용), 유통 채널별(온라인 및 오프라인), 지역별(북미, 유럽, 기타)로 세분화되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 카운터톱 제빙기 시장 동향 및 인사이트
컴팩트한 주거 공간 증가로 인한 휴대용 가전 수요 증가
도시 지역의 고밀도화로 인해 소비자들은 빌트인형 디스펜서를 설치할 수 없는 좁은 주방으로 이동하고 있습니다. 밀레니얼 세대와 Z세대 임차인들은 임대 계약 변경 시 이동이 가능한 가전제품을 선택하며, 표준 콘센트에 꽂기만 하면 사용할 수 있는 경량 카운터탑형 디자인을 선호합니다. 미국 에너지부(DOE)의 2029년 에너지 기준은 기준 효율성을 보장하는 것으로, 각 브랜드에 가변 속도 압축기 및 더 두꺼운 단열재 채택을 촉진하고 있습니다. 이러한 요인들로 인해, 카운터톱 제빙기 시장은 특히 연간 1제곱피트당 바닥 면적 비용이 50달러를 초과하는 도시 지역에서 단순한 ‘사치품’이 아닌 ‘필수품’으로서의 위상을 확립해 가고 있습니다.
소비자의 편의성 추구와 가정 내 음료 문화
홈 믹솔로지, 스페셜티 커피, 스파클링 워터로의 지속적인 전환으로 인해 얼음의 품질에 대한 기대가 높아지고 있습니다. 너겟형 제빙기는 콜드 브루나 크래프트 칵테일에 최적화된 씹는 맛이 있는 식감에 대한 수요를 충족시키고 있습니다. GE 어플라이언스의 ‘오팔(Opal)’ 시리즈는 프리미엄 제품에 대한 소비자의 지불 의지를 상징하며, 소매 가격이 700달러에 육박하는 모델이 해당 브랜드의 베스트셀러로 자리 잡고 있습니다. 미식 음료에 대한 관심이 지속됨에 따라, 카운터톱 제빙기 시장 전체에서 고사양 기종의 두 자릿수 성장세가 유지되고 있습니다.
현대식 냉장고에 제빙 디스펜서가 통합되면서 수요가 감소하고 있습니다.
현재 고급 냉장고에는 크래프트 아이스(구형)나 듀얼 제조업체가 탑재되어 있어, 부유층 가정의 독립형 제빙기 수요를 잠식하고 있습니다. LG의 ‘크래프트 아이스’ 냉장고는 냉동실 문에서 직접 녹기 어려운 구형 얼음을 공급하며, 고급 카운터톱 제빙기에 도전하고 있습니다. 그러나 카운터탑형 모델은 휴대 편의성, 짧은 제조 시간, 특수한 너겟 형태 등의 장점을 무기로 삼아, 파티나 파티오, RV에서 사용하기에 최적의 보완적 제품으로 자리매김하고 있습니다.
부문 분석
2025년, 총알형 제빙기는 성숙한 제조 기술, 8분의 초기 동결 주기, 150달러 이하의 가격대를 바탕으로 카운터톱 제빙기 시장에서 45.03%라는 최대 점유율을 차지했습니다. 이 부문은 단순한 각형 얼음을 중시하는 아파트, 기숙사, 휴게실 등을 대상으로 합니다. 너겟형 제빙기는 수량은 적지만, 탄산음료의 탄산을 유지해 주는 ‘씹어 먹을 수 있는 펠릿’의 매력 덕분에 연평균 성장률(CAGR) 9.22%로 성장하고 있습니다. 소비자들은 이러한 식감을 위해 2-3배의 가격을 지불하기 때문에 Wi-Fi를 통한 일정 설정 및 물때 방지 필터를 갖춘 GE의 ‘Opal 2.0’과 같은 혁신적인 제품이 등장하고 있습니다.
전문적인 미식가용 모델은 숙성 위스키의 희석도를 최소화하기 위해 투명하고 두께 2인치의 얼음을 필요로 하는 믹솔로지스트를 대상으로 합니다. 이러한 제품은 이중벽 구조의 냉동실을 통해 기포를 제거하며, 500-900달러에 판매되고 있습니다. 비록 틈새 시장이지만, 이 카테고리는 수제 칵테일 붐과 인스타그램의 시각적 문화의 혜택을 받고 있습니다. 전반적으로 제품의 다양화로 인해 카운터톱 제빙기 시장 전체의 평균 판매 가격 상승이 뒷받침되고 있습니다.
2025년 기준으로, 하루 최대 26파운드까지 생산 가능한 모델이 카운터톱 제빙기 시장 규모의 38.12%를 차지했으며, 일반 가정의 일일 수요를 충족시키고 있습니다. 하루 26-40파운드 용량의 모델은 소규모 카페용으로, 6분 주기의 작동 시간과 카운터 아래에 수납할 수 있는 탈부착식 보관함을 갖추고 있습니다.
하루 40파운드를 초과하는 모델은 연평균 성장률(CAGR) 8.33%로 가장 빠르게 성장하는 그룹이며, 보충 횟수 감소와 지속적인 서비스를 중시하는 사무실 및 푸드 트럭의 관심을 끌고 있습니다. 가변 속도 커패시터와 R290 냉매를 통해 전력 소비가 감소되어 캘리포니아주 및 EU의 환경 규제를 충족합니다. 더 큰 용량의 빙통에 대한 수요는 소규모 상업용과 가정 내 엔터테인먼트 트렌드가 융합되고 있음을 보여주며, 카운터톱 제빙기 시장의 전반적인 생산 능력에 대한 기대를 높이고 있습니다.
지역별 분석
북미는 매출의 36.62%를 차지하며, 세계 수요의 기반을 형성하고 있습니다. 미국에서는 콜드 브루에 적합한 너겟형 얼음이 선호되며, 사무실에서는 자판기용 얼음 봉지를 대체하는 것으로 하루 40파운드 용량의 기종이 사용되고 있습니다. 캐나다에서도 유사한 경향이 나타나며, 멕시코 도시 지역의 콘도미니엄에서는 주방 공간이 소형화됨에 따라 휴대용 제빙기가 채택되고 있습니다. FDA의 식품 등급 규정과 DOE의 에너지 목표에 따라 명확한 규제 체계가 마련되어 있으며, 각 브랜드는 소음이 더 적은 압축기와 식품에 안전한 내부 구조를 채택하는 방향으로 나아가고 있습니다.
아시아태평양은 성장의 원동력이 되고 있습니다. 중국에서는 중산층을 위한 아파트 붐이 첫 구매를 촉진하고 있으며, 쇼핑몰에서는 ‘11.11’ 쇼핑 페스티벌 기간 동안 카운터톱 제빙기의 플래그십 모델이 전시되고 있습니다. 인도의 호스피탈리티 분야 스타트업은 코워킹 카페에 태양광 발전 지원 제빙기를 도입하여, 불안정한 지자체에 의한 얼음 배송에 대한 의존도를 줄이고 있습니다. 일본에서는 가제트의 소형화에 대한 관심이 높아지면서, 10분 만에 투명한 얼음을 만들 수 있는 제품이 크라우드펀딩을 통해 자금을 조달하고 있습니다. 아세안(ASEAN)에서는 전력 공급이 불안정한 해변 리조트에서 휴대용 제빙기가 수요를 주도하고 있습니다.
유럽은 안정적이고 이익률이 높은 매출을 창출하고 있습니다. 에너지 라벨 개정으로 인해 각 브랜드는 kW시(kWh)당 소비량 감축을 강조하게 되었으며, 환경 의식이 높은 북유럽 소비자들의 공감을 얻고 있습니다. 팬데믹으로 인한 봉쇄 조치 이후 활기를 띠고 있는 영국의 홈 바 붐이 너겟형 제빙기의 매출을 뒷받침하고 있는 반면, 스페인 해안가 바에서는 관광객의 급증에 대응하기 위해 고출력 제빙기가 도입되고 있습니다. 수입업체들은 인증 비용을 상승시키는 새로운 수질 기준에 대응해야 하는 압박을 받고 있지만, 기준 준수는 브랜드에 대한 신뢰를 높여 카운터톱 제빙기 시장 전체의 장기적인 전망을 뒷받침하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the countertop ice makers market size was valued at USD 2.85 billion in 2025 and estimated to grow from USD 2.99 billion in 2026 to reach USD 3.79 billion by 2031, at a CAGR of 4.88% during the forecast period (2026-2031).
This report Segments by Product Type (Bullet Ice Makers, Nugget Ice Makers and More), by Capacity (Up To 26 Lbs/Day, 26 - 40 Lbs/Day, and More), by End User (Residential, and Commercial), by Distribution Channel (Online, and Offline), and by Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Countertop Ice Makers Market Trends and Insights
Growth in Compact Living Spaces Pushing Demand for Portable Appliances
Urban densification drives consumers toward smaller kitchens where built-in dispensers do not fit. Millennials and Gen Z renters choose appliances they can move between leases, favoring lightweight countertop designs that plug into standard outlets. DOE's 2029 energy standards assure baseline efficiency, nudging brands to adopt variable-speed compressors and thicker insulation. These forces position the countertop ice maker market as a staple rather than a discretionary category, particularly in cities where floor-space costs top USD 50 per square foot annually.
Consumer Convenience Preference and At-Home Beverage Culture
Permanent shifts toward home mixology, specialty coffee, and sparkling water elevate ice quality expectations. Nugget machines meet demands for chewable texture ideal for cold brew and craft cocktails. GE Appliances' Opal line exemplifies premium willingness to pay, with models retailing near USD 700 and ranking among the brand's bestsellers. Continuing interest in gourmet beverages sustains double-digit growth for higher-spec units across the countertop ice maker market.
Integration of Ice Dispensers in Modern Refrigerators Reducing Need
High-end fridges now include craft-ice spheres and dual makers, eroding standalone demand in affluent households. LG's Craft Ice refrigerator supplies slow-melting spheres directly from the freezer door, challenging premium countertop units. However, countertop models counter with portability, faster cycle times, and specialty nugget formats, positioning themselves as complementary for parties, patios, and RVs.
Other drivers and restraints analyzed in the detailed report include:
- Rising Adoption in Offices, Breakrooms, and Small HoReCa Outlets
- E-commerce Channel Proliferation Improving Product Accessibility
- Operational Noise and Reliability Concerns Affecting Consumer Satisfaction
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bullet units delivered the largest 45.03% countertop ice maker market share in 2025 on the back of mature manufacturing, 8-minute first-freeze cycles, and price points under USD 150. The segment serves apartments, dorms, and breakrooms that value straightforward cubes. Nugget machines, though smaller in volume, expand at 9.22% CAGR on the allure of chewable pellets that retain soda carbonation. Consumers pay 2- 3 times more for these textures, fueling innovation such as GE's Opal 2.0 with WiFi scheduling and scale-inhibiting filtration.
Specialized gourmet models aim at mixologists who require crystal-clear, 2-inch slabs that minimize dilution in aged whisky. Their double-wall freezing chambers force air bubbles out, selling at USD 500-900. Although niche, the category benefits from the craft-cocktail boom and Instagram visual culture. Collectively, product diversification sustains a climb in average selling price across the countertop ice maker market.
The Up to 26 lbs/day tier owned the largest slice of the countertop ice maker market size in 2025 at 38.12%, matching the daily needs of typical households. Units rated 26-40 lb/day bridge into small cafes, providing 6-minute cycles and removable bins that fit under counters.
Above-40 lb/day models, the fastest-growing group at 8.33% CAGR, entice offices and food trucks that prioritize fewer refills and continuous service. Variable-speed condensers and R290 refrigerant cut power draw, satisfying environmental codes in California and the EU. Demand for bigger bins indicates convergence between light commercial and residential entertaining trends and advances overall output expectations in the countertop ice maker market.
Complete Report Scope:
- By Product Type
- Bullet Ice Makers
- Nugget / Pea Ice Makers
- Gourmet / Clear Ice Makers
- By Capacity
- Up to 26 lbs / day
- 26 - 40 lbs / day
- Above 40 lbs / day
- By End User
- Residential
- Commercial
- Small Cafes and Bars
- Offices and Co-working Spaces
- Recreational Vehicles and Marine
- By Distribution Channel
- Offline
- Specialty Appliance Stores
- Big-Box Retailers
- Dealer and Distributor Networks
- Online
- E-commerce Marketplaces
- Brand-owned Webstores
- Offline
- By Geography
- North America
- Canada
- United States
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia Pacific
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Middle East And Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East And Africa
- North America
Geography Analysis
North America anchors global demand with a 36.62% slice of revenue. U.S. households value nugget textures for cold brew, while offices use 40 lb/day units to replace vending bags. Canada mirrors these patterns, and Mexico's urban condos adopt portable makers as kitchens shrink. FDA food-grade rules and DOE energy targets provide a clear regulatory landscape, nudging brands toward quieter compressors and food-safe interiors.
Asia-Pacific is the growth engine. China's middle-class apartment boom fuels first-time purchases, and malls showcase countertop ice maker market flagships during 11-11 shopping festivals. India's hospitality startups outfit co-working cafes with solar-ready makers, cutting reliance on erratic municipal ice deliveries. Japan's fascination with gadget miniaturization yields crowd-funded upgrades featuring 10-minute crystal-clear cycles. ASEAN economies add volume through beach resorts where portable machines offset unreliable grid power.
Europe contributes stable, margin-rich sales. Energy-label revisions push brands to advertise kilowatt-hour drops, resonating with eco-conscious Nordic consumers. The UK home-bar hobby, rising after pandemic lockdowns, sustains nugget sales, while Spain's coastal bars adopt high-output units to meet tourist surges. Importers must navigate emerging water-quality standards that raise certification costs, yet compliance enhances brand trust, sustaining long-run prospects across the countertop ice maker market.
- Whirlpool Corporation
- NewAir Appliances
- Frigidaire (Electrolux AB)
- Igloo (Nostalgia Products LLC)
- hOmeLabs (Aterian Inc.)
- GE Appliances (Haier)
- Scotsman (Ali Group)
- Manitowoc Ice (Welbilt Inc.)
- Vremi (Aterian Inc.)
- Magic Chef (Midea Group)
- EdgeStar (Living Direct)
- Della (SPT)
- Costway
- Dometic Group
- Luma Comfort (NewAir)
- Maxx Ice (Chef's Deal)
- SPT (Sunpentown)
- Sunpentown International
- Whynter
- Euhomy
- AGLUCKY
- Antarctic Star*
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth in compact living spaces pushing demand for portable appliances
- 4.2.2 Consumer convenience preference and at-home beverage culture
- 4.2.3 Rising adoption in offices, breakrooms, and small HoReCa outlets
- 4.2.4 E-commerce channel proliferation improving product accessibility
- 4.2.5 Van-life and RV community demand for off-grid ice (under-the-radar)
- 4.2.6 Efficiency gains enabling solar-powered countertop units (under-the-radar)
- 4.3 Market Restraints
- 4.3.1 Integration of ice dispensers in modern refrigerators reducing need
- 4.3.2 Operational noise and reliability concerns affecting consumer satisfaction
- 4.3.3 Emerging water-quality regulations increasing compliance costs (under-the-radar)
- 4.3.4 Influx of sub-standard imports eroding brand trust (under-the-radar)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Landscape
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts
- 5.1 By Product Type
- 5.1.1 Bullet Ice Makers
- 5.1.2 Nugget / Pea Ice Makers
- 5.1.3 Gourmet / Clear Ice Makers
- 5.2 By Capacity
- 5.2.1 Up to 26 lbs / day
- 5.2.2 26 - 40 lbs / day
- 5.2.3 Above 40 lbs / day
- 5.3 By End User
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.2.1 Small Cafes and Bars
- 5.3.2.2 Offices and Co-working Spaces
- 5.3.2.3 Recreational Vehicles and Marine
- 5.4 By Distribution Channel
- 5.4.1 Offline
- 5.4.1.1 Specialty Appliance Stores
- 5.4.1.2 Big-Box Retailers
- 5.4.1.3 Dealer and Distributor Networks
- 5.4.2 Online
- 5.4.2.1 E-commerce Marketplaces
- 5.4.2.2 Brand-owned Webstores
- 5.4.1 Offline
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 Canada
- 5.5.1.2 United States
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Peru
- 5.5.2.3 Chile
- 5.5.2.4 Argentina
- 5.5.2.5 Rest of South America
- 5.5.3 Asia-Pacific
- 5.5.3.1 India
- 5.5.3.2 China
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- 5.5.3.7 Rest of Asia Pacific
- 5.5.4 Europe
- 5.5.4.1 United Kingdom
- 5.5.4.2 Germany
- 5.5.4.3 France
- 5.5.4.4 Spain
- 5.5.4.5 Italy
- 5.5.4.6 BENELUX (Belgium, Netherlands, and Luxembourg)
- 5.5.4.7 NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- 5.5.4.8 Rest of Europe
- 5.5.5 Middle East And Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Nigeria
- 5.5.5.5 Rest of Middle East And Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Whirlpool Corporation
- 6.4.2 NewAir Appliances
- 6.4.3 Frigidaire (Electrolux AB)
- 6.4.4 Igloo (Nostalgia Products LLC)
- 6.4.5 hOmeLabs (Aterian Inc.)
- 6.4.6 GE Appliances (Haier)
- 6.4.7 Scotsman (Ali Group)
- 6.4.8 Manitowoc Ice (Welbilt Inc.)
- 6.4.9 Vremi (Aterian Inc.)
- 6.4.10 Magic Chef (Midea Group)
- 6.4.11 EdgeStar (Living Direct)
- 6.4.12 Della (SPT)
- 6.4.13 Costway
- 6.4.14 Dometic Group
- 6.4.15 Luma Comfort (NewAir)
- 6.4.16 Maxx Ice (Chef's Deal)
- 6.4.17 SPT (Sunpentown)
- 6.4.18 Sunpentown International
- 6.4.19 Whynter
- 6.4.20 Euhomy
- 6.4.21 AGLUCKY
- 6.4.22 Antarctic Star*
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-need assessment


