

|
시장보고서
상품코드
2125729
인도네시아의 클라우드 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Indonesia Cloud - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
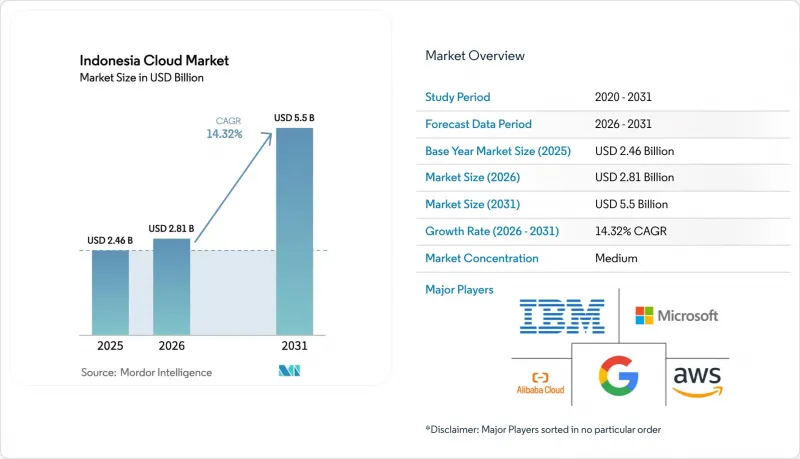
에 의하면, 인도네시아 클라우드 시장 규모는 2025년 24억 6,000만 달러에서 2026년에는 28억 1,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 14.32%로 성장을 지속하여, 2031년에는 55억 달러에 이를 것으로 예측됩니다.
본 보고서는 서비스 모델(SaaS(Software as a Service), PaaS(Platform as a Service) 등), 도입 모델(퍼블릭 클라우드, 프라이빗 클라우드, 하이브리드 클라우드), 조직 규모(중소기업 및 대기업),최종 이용 산업(IT 및 통신, 은행, 금융서비스 및 보험(BFSI), 소매 및 소비재 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
인도네시아 클라우드 시장 동향 및 인사이트
기업들의 디지털 전환에 대한 급속한 투자
대기업들은 디지털 네이티브 경쟁사들에 맞서 시장 점유율을 지키기 위해 핵심 시스템의 현대화를 추진하고 있습니다. 마이크로소프트의 17억 달러 규모 지역 클라우드 계획과 Oracle의 65억 달러 규모 바탐 캠퍼스는 장기적인 수요를 뒷받침합니다. GoTo가 알리바바 클라우드 및 텐센트 클라우드와 병행하여 제휴를 맺고 가격과 내결함성의 균형을 맞추면서 멀티 클라우드 도입이 가속화되고 있습니다. 텔콤 인도네시아와 레카 AI의 제휴는 기존 기업들이 PaaS(Platform as a Service)를 통해 언어 인식 AI를 통합하여 고객과의 상호작용을 개선하고 있음을 보여줍니다. 지속적인 혁신 주기로 인해 투자는 일회성 전환에 그치지 않고, 수익성이 높은 클라우드 서비스의 도입이 지속되고 있습니다. 이러한 추세는 SaaS의 주도적 지위를 공고히 하는 한편, DevOps 지원 PaaS 스택에 대한 수요를 불러일으키고 있습니다.
인도네시아 데이터센터 지역의 하이퍼스케일러 설비 투자(CAPEX)
아마존의 50억 달러 규모 AI 클라우드 투자 공약과 디지털 리얼티(Digital Realty)의 4억 9,900만 달러 규모 자카르타 합작 사업은 향후 수년에 걸친 워크로드 성장에 대한 확신을 강화하고 있습니다. 투자는 그레이터 자카르타나 바탐과 같은 저지연 회랑 주변에 집중되어 있으며, 재생에너지 조달을 통해 ESG 목표와의 조화를 도모하고 있습니다. Google Cloud의 ‘BerdAIa’ 프로그램은 지역적 용량이 산업 특화형 AI 생태계 구축을 어떻게 뒷받침하고 있는지 보여줍니다. 각 하이퍼스케일러 기업들은 10년 단위의 투자 회수 기간을 수용하고 있으며, 이는 인도네시아의 거시경제 안정성과 규제 명확성에 대한 신뢰를 보여줍니다. 현지 코로케이션 제공업체들은 앵커 테넌트 수요를 통해 혜택을 보고 있으며, 이는 2선 도시의 2차 시장 발전을 촉진하고 있습니다.
사이버 보안 침해로 인한 비용 증가
국립 데이터센터에 대한 800만 달러 규모의 랜섬웨어 요구는 기업의 신뢰를 흔들었고, 리스크 회피 성향이 강한 부문으로의 전환을 지연시켰습니다. 새로운 아동 온라인 보호 규정에 따라 보안 계층이 추가되면서 제공업체의 운영 비용이 증가하고 있습니다. 금융 기관들은 막대한 벌금과 평판 하락에 직면해 있으며, 시장은 검증된 제로 트러스트 프레임워크를 갖춘 공급업체로 기울고 있습니다. 감독 강화로 인해, 공급업체가 인증된 복원력 프로그램을 제시할 때까지 도입이 지연되고 있는 기업들을 중심으로 인도네시아 클라우드 시장의 확산이 단기적으로 억제될 가능성이 있습니다.
부문 분석
2025년, 인도네시아 클라우드 시장에서 SaaS(Software as a Service)는 44.62%를 차지했습니다. 이는 기업들이 예측 가능한 운영 비용(OPEX)으로 즉시 가동 가능한 비즈니스 용도를 선택했기 때문입니다. PaaS는 15.42%라는 가장 높은 연평균 성장률(CAGR)로 그 뒤를 이었으며, 이는 마이크로서비스 및 컨테이너 오케스트레이션에 대한 개발자 수요를 반영한 것입니다. IaaS(Infrastructure as a Service)는 이 두 가지를 모두 뒷받침하는 기반이 되어, 중소규모의 SaaS 사업자가 자체적으로 소유하지 않고 임대 형태로 이용할 수 있는 탄력적인 컴퓨팅 리소스를 제공합니다. DRaaS(Disaster Recovery as a Service)의 도입은 주목을 받은 서비스 중단 사고를 계기로 급증했으며, 복원력은 이사회 수준의 위험 의제에 포함되게 되었습니다.
인도네시아의 SaaS 클라우드 시장 규모는 BFSI(은행 및 금융 및 보험) 및 헬스케어 분야에서 규정 준수 대응 솔루션이 보급됨에 따라 확대될 전망입니다. PaaS 벤더들은 Telkom DWS의 멀티미디어 CPaaS 제품군과 같이 분야별 특화 API를 통해 차별화를 꾀하고 있습니다. 현지 제공업체인 Lintasarta는 OpenShift 기반 PaaS에 백업 저장소를 번들로 제공하여 엄격한 현지화 규제를 준수하고 있습니다. 이러한 통합 스택은 하이퍼스케일 사업자의 가격 인하로부터 이익률을 보호하고, 경쟁의 균형을 안정시키고 있습니다.
퍼블릭 클라우드는 즉각적인 확장성과 비용 가시성 덕분에 2025년 인도네시아 클라우드 시장 점유율의 66.05%를 차지했습니다. 그러나 지연에 민감한 워크로드나 규제 대상 워크로드의 경우, 기업들이 On-Premise 및 코로케이션 노드를 조합하여 활용함에 따라 하이브리드 아키텍처는 연평균 성장률(CAGR) 15.21%로 성장을 지속하고, 있습니다. 프라이빗 클라우드는 여전히 틈새 시장으로 남아 있으며, 국방 및 중요 인프라 등 극도로 엄격한 규제가 적용되는 환경으로 제한되어 있습니다.
하이브리드의 성장은 GoTo의 듀얼 프로바이더 전략과 국경을 넘어 용량을 공유하는 Singtel-GMI의 GPU 풀 프로젝트에 기인합니다. Wi-Fi 6E/7의 도입으로 사이트에서 클라우드로의 처리량이 최대 46Gbps까지 향상되어 분산형 아키텍처가 지원됩니다. 규제 당국이 국내 데이터 복제를 의무화하고, 이사회가 멀티클라우드를 통한 내결함성을 요구하는 가운데, 인도네시아의 하이브리드 솔루션 시장 규모는 복합적으로 확대될 것으로 예측됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the Indonesia cloud market size is expected to grow from USD 2.46 billion in 2025 to USD 2.81 billion in 2026 and is forecast to reach USD 5.5 billion by 2031 at 14.32% CAGR over 2026-2031.
This report is Segmented by Service Model (Software As A Service, Platform As A Service, and More), Deployment Model (Public Cloud, Private Cloud, and Hybrid Cloud), Organization Size (Small and Medium Enterprises and Large Enterprises), and End-Use Industry (IT and Telecom, BFSI, Retail and Consumer Goods, and More). The Market Forecasts are Provided in Terms of Value (USD).
Indonesia Cloud Market Trends and Insights
Rapid digital-transformation spend by enterprises
Large corporations modernize core systems to defend market share against digital-native rivals. Microsoft's USD 1.7 billion regional cloud plan and Oracle's USD 6.5 billion Batam campus validate long-term demand. Multi-cloud adoption accelerates as GoTo partners concurrently with Alibaba Cloud and Tencent Cloud to balance pricing and resilience. Telkom Indonesia's alliance with Reka AI shows traditional firms embedding language-aware AI through Platform as a Service to improve customer interactions. Continuous innovation cycles elevate spend beyond one-off migrations, sustaining uptake of higher-margin cloud offerings. This dynamic cements SaaS leadership while igniting demand for DevOps-ready PaaS stacks.
Hyperscaler CAPEX on Indonesian data-center regions
Amazon's USD 5 billion AI-cloud pledge, alongside Digital Realty's USD 499 million Jakarta JV, reinforces confidence in multiyear workload growth. Investment clusters around low-latency corridors in Greater Jakarta and Batam, with renewable power procurement aligning ESG goals. Google Cloud's BerdAIa program illustrates how regional capacity underpins ecosystem building for industry-specific AI. Hyperscalers accept decade-long payback profiles, signaling belief in Indonesia's macro stability and regulatory clarity. Local colocation providers benefit via anchor-tenant demand, catalyzing secondary market development in second-tier cities.
Escalating cybersecurity-breach costs
A USD 8 million ransomware demand on the National Data Center shook enterprise confidence, pushing risk-averse sectors to delay migrations. New child online protection rules add additional security layers, increasing provider overhead. Financial institutions face punitive fines and reputational harm, tilting the market toward vendors with proven zero-trust frameworks. Heightened scrutiny may short-term curb Indonesia's cloud market uptake among late-adopting firms until providers showcase certified resilience programs.
Other drivers and restraints analyzed in the detailed report include:
- Government Digital Indonesia 2025 and e-Gov push
- Surge in e-commerce/fintech cloud workloads
- Complex data-localization and sectoral compliance
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software as a Service accounted for 44.62% of the Indonesian cloud market in 2025 as firms opted for ready-to-run business applications with predictable OPEX. PaaS follows with the fastest 15.42% CAGR, reflecting developer demand for micro-services and container orchestration. Infrastructure as a Service underpins both, supplying elastic compute that smaller SaaS players lease rather than own. Disaster Recovery as a Service uptake spikes after high-profile outages, embedding resiliency into board-level risk agendas.
The Indonesian cloud market size for SaaS will widen as compliance-ready solutions gain traction in BFSI and healthcare. PaaS vendors differentiate on domain-specific APIs, such as Telkom DWS's multimedia CPaaS suite. Local provider Lintasarta bundles OpenShift-based PaaS with backup vaults, meeting stringent localization rules. These integrated stacks protect margins against hyperscale price cuts, stabilizing competitive equilibrium.
Public deployments captured 66.05% Indonesia cloud market share in 2025 due to immediate scalability and cost visibility. Hybrid architectures, however, post a 15.21% CAGR as firms blend on-premise or colocation nodes for latency-sensitive or regulated workloads. Private clouds remain niche, reserved for ultra-regulated setups in defense or critical infrastructure.
Hybrid growth stems from GoTo's dual-provider play and Singtel-GMI's pooled GPU project that share capacity across borders. Rollout of Wi-Fi 6E/7 enables site-to-cloud throughput up to 46 Gbps, supporting distributed architectures. The Indonesian cloud market size for hybrid solutions is forecast to compound as regulators mandate in-country data copies while boards demand multicloud resilience.
Complete Report Scope:
- By Service Model
- Software as a Service (SaaS)
- Platform as a Service (PaaS)
- Infrastructure as a Service (IaaS)
- Disaster-Recovery as a Service (DRaaS)
- By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid Cloud
- By Organisation Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- By End-Use Industry
- IT and Telecom
- BFSI
- Retail and Consumer Goods
- Manufacturing
- Healthcare and Life Sciences
- Government and Public Sector
- Transportation and Logistics
- Energy and Utilities
- Other End-Use Industries
- By Region
- Java
- Sumatra
- Kalimantan
- Sulawesi
- Bali and Nusa Tenggara
- Papua and Maluku
List of Companies Covered in this Report:
- Amazon Web Services, Inc.
- Microsoft Corporation
- Google LLC
- Alibaba Cloud (Alibaba Group Holding Limited)
- IBM Corporation
- Tencent Cloud Computing (Beijing) Co., Ltd.
- Oracle Corporation
- Huawei Technologies Co., Ltd.
- Salesforce, Inc.
- OVH Groupe SAS
- DigitalOcean Holdings, Inc.
- Rackspace Technology, Inc.
- Linode LLC (Akamai Technologies Inc.)
- Vultr Holdings Corporation, LLC
- Hetzner Online GmbH
- PT DCI Indonesia Tbk
- PT Telekomunikasi Indonesia (Persero) Tbk
- PT Indosat Tbk (Indosat Ooredoo Hutchison)
- PT XL Axiata Tbk
- PT Biznet Gio Nusantara
- PT Indonesian Cloud
- Princeton Digital Group Pte. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid digital-transformation spend by enterprises
- 4.2.2 Hyperscaler CAPEX on Indonesian data-centre regions
- 4.2.3 Government "Digital Indonesia 2025" and e-Gov push
- 4.2.4 Surge in e-commerce / fintech cloud workloads
- 4.2.5 National Data Centre (PDN) enabling sovereign cloud
- 4.2.6 Renewable-powered 'green-cloud' demand from ESG-focused firms
- 4.3 Market Restraints
- 4.3.1 Escalating cybersecurity-breach costs
- 4.3.2 Complex data-localisation and sectoral compliance
- 4.3.3 Shortage of cloud-skilled talent and high wage inflation
- 4.3.4 Inter-island power and fibre reliability gaps
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Key Use Cases
- 4.9 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Service Model
- 5.1.1 Software as a Service (SaaS)
- 5.1.2 Platform as a Service (PaaS)
- 5.1.3 Infrastructure as a Service (IaaS)
- 5.1.4 Disaster-Recovery as a Service (DRaaS)
- 5.2 By Deployment Model
- 5.2.1 Public Cloud
- 5.2.2 Private Cloud
- 5.2.3 Hybrid Cloud
- 5.3 By Organisation Size
- 5.3.1 Small and Medium Enterprises (SMEs)
- 5.3.2 Large Enterprises
- 5.4 By End-Use Industry
- 5.4.1 IT and Telecom
- 5.4.2 BFSI
- 5.4.3 Retail and Consumer Goods
- 5.4.4 Manufacturing
- 5.4.5 Healthcare and Life Sciences
- 5.4.6 Government and Public Sector
- 5.4.7 Transportation and Logistics
- 5.4.8 Energy and Utilities
- 5.4.9 Other End-Use Industries
- 5.5 By Region
- 5.5.1 Java
- 5.5.2 Sumatra
- 5.5.3 Kalimantan
- 5.5.4 Sulawesi
- 5.5.5 Bali and Nusa Tenggara
- 5.5.6 Papua and Maluku
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Amazon Web Services, Inc.
- 6.4.2 Microsoft Corporation
- 6.4.3 Google LLC
- 6.4.4 Alibaba Cloud (Alibaba Group Holding Limited)
- 6.4.5 IBM Corporation
- 6.4.6 Tencent Cloud Computing (Beijing) Co., Ltd.
- 6.4.7 Oracle Corporation
- 6.4.8 Huawei Technologies Co., Ltd.
- 6.4.9 Salesforce, Inc.
- 6.4.10 OVH Groupe SAS
- 6.4.11 DigitalOcean Holdings, Inc.
- 6.4.12 Rackspace Technology, Inc.
- 6.4.13 Linode LLC (Akamai Technologies Inc.)
- 6.4.14 Vultr Holdings Corporation, LLC
- 6.4.15 Hetzner Online GmbH
- 6.4.16 PT DCI Indonesia Tbk
- 6.4.17 PT Telekomunikasi Indonesia (Persero) Tbk
- 6.4.18 PT Indosat Tbk (Indosat Ooredoo Hutchison)
- 6.4.19 PT XL Axiata Tbk
- 6.4.20 PT Biznet Gio Nusantara
- 6.4.21 PT Indonesian Cloud
- 6.4.22 Princeton Digital Group Pte. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


