

|
시장보고서
상품코드
2154228
북미의 페인트 및 코팅 첨가제 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)North America Paints and Coatings Additives - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
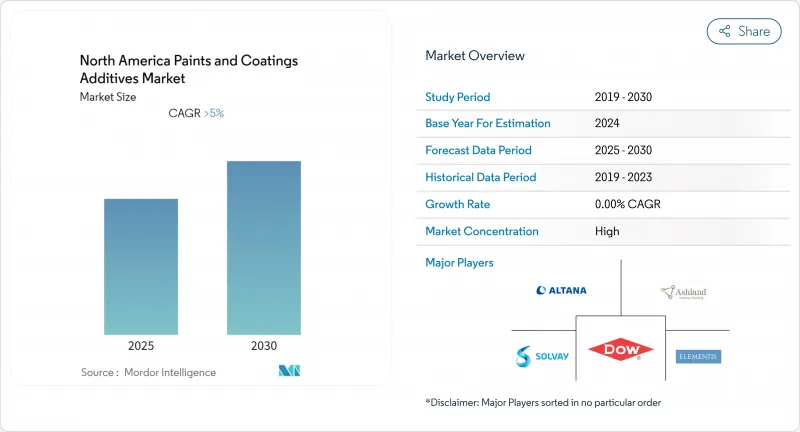
에 따르면 북미의 페인트·코팅 용첨가제 시장 규모는 2025년에 28억 5,000만 달러로 평가되며, 2026년 30억 달러에서 2031년까지 38억 5,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 5.12%에 달할 전망입니다.
북미 도료·코팅용 첨가제 시장의 동향 및 인사이트
수성 및 저VOC 코팅으로의 전환
2025년 1월 개정된 연방규정집(CFR) 제40편 제59부에 기반한 ‘국가 휘발성 유기화합물(VOC) 배출 기준’에서는 관련 소비자용 및 산업용 제품에 대해 제품 중량 기준의 반응성 제한이 도입되었습니다. 이러한 변경으로 인해 중량당 VOC 함량뿐만 아니라 오존 생성 가능성을 줄일 수 있는 코어리스 센트 및 소포제의 중요성이 더욱 높아졌습니다. 수성 시스템에서는 물이 용제처럼 수지계를 용해하지 않기 때문에 분산제 및 안정제가 필요합니다. 제조업체들이 수성 배합으로 전환함에 따라 이러한 요건으로 인해 완제품 도료 1단위당 첨가제 사용량이 증가하고 있습니다. 또한 전문 시공업체들도 저취, 알킬페놀 에톡실레이트 미사용, 그리고 VOC 함량이 거의 제로인 제품을 선호하는 경향이 있으며, 이로 인해 배합 요건이 더욱 엄격해지고 있습니다. 캐나다에서는 ‘특정 제품의 VOC 농도 제한에 관한 규정’이 유사한 지침을 제시하고 있으며, 북미의 도료·코팅용 첨가제 시장에서 지역별 규정 준수에 대한 관심이 더욱 높아지고 있습니다.
인프라 개보수 및 비주거용 건설
연방 정부의 교량 데이터에 따르면 미국의 많은 교량은 여전히 정비가 필요한 것으로 나타나며, 이는 유지 관리 및 재도장 프로그램에 대한 수요를 지원하고 있습니다. 교량, 고속도로, 수자원 관련 자산에 사용되는 보호 시스템에는 성능 사양 및 10-15년의 보증 기간이 요구됩니다. 이러한 요건으로 인해 코팅 제품에서 유변학 조절제, 침강 방지제 및 부식 방지제의 역할이 커지고 있습니다. 따라서 북미의 도료·코팅용 첨가제 시장은 가계 소비 동향이 아닌, 예산 배분 일정에 따라 시행되는 공공 자본 사업으로부터 혜택을 받고 있습니다. 보호 코팅이 정해진 수명 기간 중 도포 일관성, 내식성 및 도막 품질을 유지해야 하는 경우, 고품질의 첨가제 패키지가 중요합니다. 본 조사를 통해 공급업체는 코팅 프로젝트가 계획, 조달 및 유지 관리의 각 주기를 거쳐 진행되는 수년에 걸친 수요에 대한 가시성을 확보할 수 있습니다.
원자재 가격 변동
대부분의 합성 코팅용 첨가제는 석유화학 유래 중간체를 사용하므로 생산자는 원자재의 확보 가능성이나 비용 변동의 영향을 받기 쉬운 상황에 놓여 있습니다. 일부 특수 화학 제품 수입에 대한 미국의 관세 변경은 근본적인 투입재 인플레이션에 더해 공급망에 추가적인 압박을 가하고 있습니다. 이산화티타늄은 여전히 안료 관련 배합에서 주요 비용 지표이며, 일메나이트 공급 부족과 황산 비용 상승이 코팅 밸류체인에 영향을 미치고 있습니다. 제조업체의 경우, 고객이 가격 인상을 수용하기까지 3-6개월의 시차가 발생할 수 있으므로, 이익률에 미치는 영향은 사업 회복에 앞서 나타날 것입니다. ‘유해물질 규제법(TSCA)’에 따른 제조 전 신고 절차는 제조사가 새로운 특수 화학물질에서 원자재 대체를 시도할 때 시간이 소요되는 요인이 될 수 있습니다. 북미의 도료·코팅용 첨가제 시장은 제조사가 신속하게 공급원을 전환하는 데 필요한 규모나 승인된 대체품이 부족하므로 가장 큰 영향을 받을 수 있는 상황에 놓여 있습니다.
부문 분석
2025년에는 소포제 및 탈기제가 수요의 26.56%를 차지했습니다. 건축용 및 산업용 수성 도료에서 기포 제어는 혼합, 도포 및 도막 품질에 영향을 미치기 때문에 이러한 역할을 대체하기는 어렵습니다. 수성계는 고전단 가공 및 도포 과정에서 용제계 시스템보다 더 많은 거품을 발생시킵니다. 따라서 수성 도료 1단위를 추가할 때마다 신뢰할 수 있는 소포 대책이 필요합니다. 에보닉 인더스트리즈 AG의 실록산계 소포제 농축액 ‘TEGO Foamex 8051’은 지속가능한 수성 도료에 대한 적용이 높이 평가되어, 2026년에 링기에 코팅 산업 혁신상을 수상했습니다.
저VOC 도료는 안료의 충전율이 높고 안정적인 분산이 요구되므로, 분산제나 습윤제는 여전히 중요합니다. 루브리졸(Lubrizol)은 2026년 7월, 이산화티타늄 및 무기 안료 시스템을 위한 ‘Solsperse 82510’과 ‘Solsperse 84510’을 출시했습니다. 살균제는 건축용 도료, 특히 습기가 많은 지역에서 용기 내부 및 건조막의 보존을 돕습니다. 유변학 조절제, 안정제, 표면 개질제, 유동 및 레벨링 첨가제는 배합 변화에 따라 점도, 안정성, 외관에 관한 요구 사항을 충족시킵니다. 배합 설계자가 불소계 계면활성제 기반 시스템을 대체하는 경우, PFAS가 포함되지 않은 유동 및 레벨링 첨가제가 주목받고 있습니다.
기타 장점:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 가치 및 공급망 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 유형별
- 용도별
- 지역별
- 미국
- 캐나다
- 멕시코
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- Allnex GMBH
- ALTANA AG
- Arkema
- Ashland
- BASF
- Cabot Corporation
- CLARIANT
- Dow
- Eastman Chemical Company
- Elementis PLC
- Evonik Industries AG
- Lubrizol
- Momentive
- Nouryon
- Solvay
제7장 시장 기회와 향후 전망
KSA 26.10.23According to Mordor Intelligence, the North America paints and coatings additives market size was valued at USD 2.85 billion in 2025 and is estimated to grow from USD 3.00 billion in 2026 to reach USD 3.85 billion by 2031, at a CAGR of 5.12% during the forecast period (2026-2031).
North America Paints and Coatings Additives Market Trends and Insights
Shift Toward Waterborne and Low-VOC Coatings
The January 2025 update to National Volatile Organic Compound Emission Standards under 40 Code of Federal Regulations (CFR) Part 59 introduced product-weighted reactivity limits for relevant consumer and commercial products. The change moved attention beyond VOC content by weight and increased the value of coalescents and defoamers that can support lower ozone-formation potential. Waterborne systems need dispersants and stabilizers because water does not dissolve resin systems in the same way as solvents. That requirement increases additive use per unit of finished paint as manufacturers move toward waterborne formulations. Professional contractors also favor low-odor, alkylphenol ethoxylate-free, and near-zero-VOC products, which adds to formulation requirements. In Canada, VOC Concentration Limits for Certain Products Regulations point in the same direction and reinforce a regional compliance focus for the North America paints and coatings additives market.
Infrastructure Renewal and Non-Residential Construction
Federal bridge data showed that many U.S. bridges still required attention, supporting demand for maintenance and recoating programs. Protective systems used on bridges, highways, and water assets require performance specifications and warranty periods of 10-15 years. Those requirements increase the role of rheology modifiers, anti-settling agents, and corrosion inhibitors in coating packages. The North America paints and coatings additives market, therefore, benefits from public capital programs that follow appropriation schedules rather than household spending patterns. Premium additive packages are relevant where protective coatings must retain application consistency, corrosion resistance, and film quality over the required service period. This work offers suppliers demand visibility across several years where coating projects progress through planning, procurement, and maintenance cycles.
Raw Material Price Volatility
Most synthetic coating additives use petrochemical-derived intermediates, leaving producers exposed to changes in raw-material availability and cost. U.S. tariff changes on some specialty chemical imports add supply-chain pressure to underlying input inflation. Titanium dioxide remains a key cost reference for pigment-related formulations, and tight ilmenite supply and higher sulfuric acid costs have affected the coatings value chain. Producers can face a 3-6-month delay before customers accept price increases, so the margin effect occurs before commercial recovery. The Toxic Substances Control Act (TSCA) premanufacture notification process can add time when producers seek to substitute raw materials in a new specialty chemical. The North America paints and coatings additives market is most exposed, where manufacturers lack the scale or approved alternatives needed to shift supply quickly.
Other drivers and restraints analyzed in the detailed report include:
- Growth in Automotive and Electric Vehicle Coatings
- Demand for High-Performance and Multifunctional Additives
- Regulatory Testing and Product Registration Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Defoamers and deaerators held 26.56% of the demand in 2025. Their role is hard to replace in architectural and industrial waterborne coatings because foam control affects mixing, application, and film quality. Aqueous media generate more foam during high-shear processing and application than solvent-borne systems. Each additional unit of waterborne paint, therefore, needs a reliable foam-control approach. Evonik Industries AG's TEGO Foamex 8051 siloxane-based defoamer concentrate received the Ringier Coating Industry Innovation Award in 2026 for its use in sustainable waterborne coatings.
Dispersants and wetting agents remain important as low-VOC coatings use higher pigment loading and need stable dispersion. Lubrizol introduced Solsperse 82510 and Solsperse 84510 in July 2026 for titanium dioxide and inorganic pigment systems. Biocides support in-can and dry-film preservation in architectural coatings, particularly in humid areas. Rheology modifiers, stabilizers, surface modifiers, and flow and leveling additives address viscosity, stability, and appearance requirements as formulations change. PFAS-free flow and leveling options are receiving attention where formulators replace fluorosurfactant-based systems.
Complete Report Scope:
- By Type
- Defoamers and Deaerators
- Biocides
- Dispersants and Wetting Agents
- Rheology Modifiers
- Surface Modifiers
- Stabilizers
- Flow and Leveling Additives
- Other Types
- By Application
- Architectural
- Wood
- Transportation
- Protective
- Other Applications
- By Geography
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Allnex GMBH
- ALTANA AG
- Arkema
- Ashland
- BASF
- Cabot Corporation
- CLARIANT
- Dow
- Eastman Chemical Company
- Elementis PLC
- Evonik Industries AG
- Lubrizol
- Momentive
- Nouryon
- Solvay
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Shift Toward Waterborne and Low-VOC Coatings
- 4.2.2 Infrastructure Renewal and Non-Residential Construction
- 4.2.3 Growth in Automotive and Electric Vehicle Coatings
- 4.2.4 Demand for High-Performance and Multifunctional Additives
- 4.2.5 Qualification of Bio-Based and PFAS-Free Additives in Formulations
- 4.3 Market Restraints
- 4.3.1 Raw Material Price Volatility
- 4.3.2 Regulatory Testing and Product Registration Costs
- 4.3.3 Long Formulation Qualification Cycles
- 4.4 Value and Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Defoamers and Deaerators
- 5.1.2 Biocides
- 5.1.3 Dispersants and Wetting Agents
- 5.1.4 Rheology Modifiers
- 5.1.5 Surface Modifiers
- 5.1.6 Stabilizers
- 5.1.7 Flow and Leveling Additives
- 5.1.8 Other Types
- 5.2 By Application
- 5.2.1 Architectural
- 5.2.2 Wood
- 5.2.3 Transportation
- 5.2.4 Protective
- 5.2.5 Other Applications
- 5.3 By Geography
- 5.3.1 United States
- 5.3.2 Canada
- 5.3.3 Mexico
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Allnex GMBH
- 6.4.2 ALTANA AG
- 6.4.3 Arkema
- 6.4.4 Ashland
- 6.4.5 BASF
- 6.4.6 Cabot Corporation
- 6.4.7 CLARIANT
- 6.4.8 Dow
- 6.4.9 Eastman Chemical Company
- 6.4.10 Elementis PLC
- 6.4.11 Evonik Industries AG
- 6.4.12 Lubrizol
- 6.4.13 Momentive
- 6.4.14 Nouryon
- 6.4.15 Solvay
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


