

|
시장보고서
상품코드
2154327
배 배양기 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Embryo Incubator - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
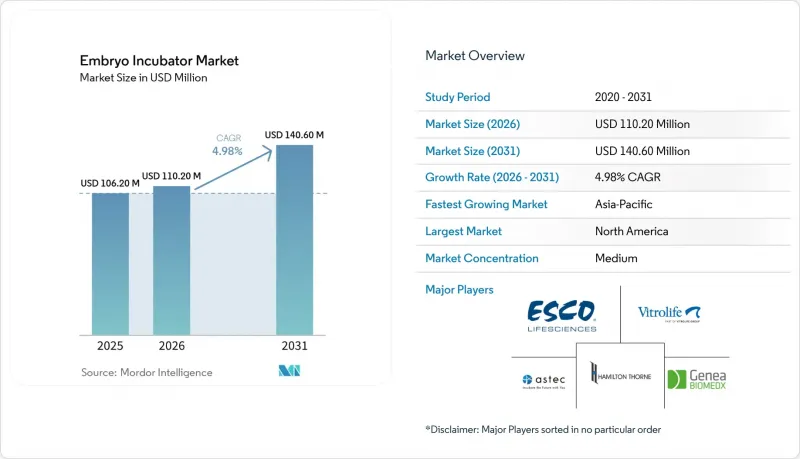
에 따르면 배 인큐베이터 시장 규모는 2025년 1억 620만 달러에서 2026년에는 1억 1,020만 달러로 확대하며, 2031년까지 1억 4,060만 달러에 달할 것으로 예상되고 있으며, 2026-2031년에 CAGR 4.98%로 성장할 것으로 전망되고 있습니다.
전 세계 배아 배양기 시장의 동향 및 인사이트
불임증 증가와 출산 연령의 고령화
출산 연령의 고령화에 따라 체외수정(IVF) 치료에서 배아 배양 및 모니터링의 중요성이 점점 더 커지고 있습니다. 고령에 치료를 시작하는 환자의 경우, 보다 치밀한 임상 평가와 더 안정적인 배양 환경이 필요할 수 있습니다. 이에 따라 온도, 이산화탄소, 산소, 습도를 일관되게 관리하는 시스템에 대한 수요가 증가하고 있습니다. 아시아의 일부 시장에서는 공공 지원 프로그램을 통해 재진 환자뿐만 아니라 신규 환자도 불임 치료를 받게 되었습니다. 이러한 신규 환자층의 증가는 기존 장비의 교체뿐만 아니라 새로운 클리닉 개설 및 실험실 설비의 전면적인 도입으로 이어질 가능성이 있습니다. 그 결과, 환자 수요, 새로운 실험실의 수용 능력, 그리고 더욱 고도화된 장비 요구 사항이 결합되어 예측 기간 중 배아 배양기 시장에 안정적인 기반을 마련해 줄 것입니다.
체외수정(IVF) 및 미세주입(ICSI) 시술 건수의 확대
개발도상국 및 성숙한 의료 시장에서 불임 치료 클리닉 네트워크의 수용 능력이 확대됨에 따라 체외수정(IVF) 및 현미수정이식(ICSI) 시술 건수가 증가하고 있습니다. 2025년 12월 기준, 인도에는 2,616곳의 등록된 IVF 센터가 있으며, 이는 표준화된 실험실 장비가 필요한 클리닉 인프라의 규모를 짐작하게 합니다. ICSI의 경우, 배아가 온도, pH, 가스의 변동에 민감하므로 주입 후 배양 조건을 정밀하게 관리해야 합니다. 트라이가스 방식이나 멀티룸 방식을 채택함으로써, 실험실이 가장 바쁜 시간대에도 가스 회복을 신속하게 하고 배양 환경을 분리하여 관리할 수 있게 됩니다. 따라서 IVF와 ICSI 프로토콜을 병행하는 클리닉의 경우, 독립된 챔버와 신뢰성 높은 환경 제어 기능을 갖춘 시스템에 대한 투자가 더욱 중요해집니다. 이러한 관계는 IVF가 여전히 더 큰 비중을 차지하고 있음에도 불구하고 ICSI가 배아 인큐베이터 시장 전체보다 빠르게 성장하고 있는 이유를 설명하는 한 가지 요인이 되고 있습니다.
높은 초기 투자 비용과 제한된 보험 환급
타임랩스 및 트라이가스 시스템은 기존의 이산화탄소 인큐베이터보다 더 많은 초기 투자가 필요합니다. 주기 수가 적거나 자금력이 제한적인 클리닉의 경우, 그 비용을 정당화하기 어려울 수 있습니다. 타임랩스 모니터링에 대한 보험 급여는 여전히 불균일하므로 일부 클리닉에서는 환자 본인 부담금을 통해 비용을 회수할 수밖에 없습니다. 품질관리, 검증 및 규제 관련 문서 작성은 소규모 의료 기관에 있으며, 추가적인 운영 비용이 될 수 있습니다. 이로 인해 대규모 불임 치료 체인은 많은 주기에 투자를 분산할 수 있는 반면, 독립 클리닉은 기존 시스템을 유지하는 등 양극화된 구매 패턴이 나타나고 있습니다. 그 결과, 배양기 시장에서는 도시 지역, 사례 수가 많은, 자금력이 풍부한 의료 시설에서 프리미엄 시스템의 보급률이 높게 나타나고 있습니다.
부문 분석
2025년, 3가스 배양기는 산소, 이산화탄소, 질소 환경을 제어할 수 있다는 점을 강점으로 삼아 배아 배양기 시장 점유율의 30.32%를 차지했습니다. 이 시스템의 임상적 매력은 생식기 계통에 더 가까운 저산소 상태를 유지할 수 있다는 점에 있습니다. 2026년 3가스 혼합 방법에 관한 연구에서는 루멘 혼합 방식에서 더 높은 임상 임신율이 보고되었습니다.
카메라가 장착된 3가스 인큐베이터는 가장 빠르게 성장하는 제품 카테고리이며, 이 부문의 배아 인큐베이터 시장 규모는 2031년까지 연평균 성장률(CAGR) 8.36%로 확대될 것으로 예측됩니다. 이 형식은 제어된 가스 환경과 연속적인 영상 촬영을 결합하고 있습니다. 이를 통해 안정적인 배양과 발육 관찰 간의 상충 관계를 완화합니다.
2025년 기준, 타임랩스 이미징은 배아 인큐베이터 시장 점유율의 35.46%를 차지했습니다. 이는 설비 투자 비용과 데이터 검토 과정을 감당할 수 있는 클리닉에서 주요 모니터링 수단이 되고 있습니다. 이 기술을 통해 인큐베이터내 배아의 발육이 기록되며, 현미경 관찰을 위한 일상적인 배양접시 꺼내기를 줄일 수 있습니다. 이를 통해 제어된 배양 조건을 유지하면서 일관된 관찰이 가능해집니다. 한편, 표준 배양법은 처리량이 적은 시설이나 연구 중심의 연구소에서 여전히 널리 이용되고 있습니다.
AI를 활용한 배아 평가는 2031년까지 연평균 성장률(CAGR) 8.79%로 성장할 것으로 예측됩니다. 이 분야에서는 이미지 데이터를 활용하여 배아 선별을 지원하고, 수동적인 형태 및 운동학적 평가에 대한 의존도를 낮추고 있습니다. 2025년 및 2026년에 발표된 조사에서는 딥러닝 모델을 사용하여 타임랩스 이미지를 분석하고 배아의 특성을 평가할 가능성이 제시되었습니다.
지역별 분석
2025년, 북미는 전 세계 배아 인큐베이터 시장 점유율의 43.21%를 차지했습니다. 이 지역에는 상업적인 불임 치료 클리닉 네트워크가 밀집해 있으며, 고품질 실험실 장비의 사용자 기반도 탄탄합니다. 미국의 클리닉에서는 규제 및 임상 요건이 충족되는 대로 타임랩스 영상이나 AI를 활용한 툴을 조기에 도입하는 경우가 많습니다. 또한 전문 클리닉이 집중되어 있는 점도 공급업체의 교육, 유지보수 및 유통망 구축을 지원하고 있습니다. 일부 주에서 보험 적용 범위가 변경됨에 따라 여러 차례의 체외수정(IVF) 주기를 희망하는 환자 수가 증가할 가능성이 있습니다. 이로 인해 클리닉의 수용 능력과 장비에 대한 투자 필요성이 더욱 높아질 것입니다. 아울러 배아학 분야의 인력 부족도 관찰의 일관성과 워크플로우 효율을 향상시킬 수 있는 시스템에 대한 관심을 높이고 있습니다.
2025년 기준, 유럽은 지역별 시장 규모에서 2위를 차지했습니다. 스칸디나비아 국가에서는 타임랩스 기술의 활용이 정착된 반면, 독일, 스페인, 영국에는 대규모 불임 치료 클리닉 네트워크가 존재합니다. 유럽 의료기기 규정(MDR)에 따라 소프트웨어 및 하드웨어 공급업체는 정해진 규제 요건을 충족해야 하므로, 조달에 영향을 미치고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 이 지역의 배아 배양기 시장 규모는 2031년까지 연평균 성장률(CAGR) 8.76%로 확대될 것으로 예측됩니다. 클리닉의 확대, 정부 지원 정책, 그리고 충분한 의료 서비스를 받지 못하는 많은 환자층이 이러한 성장을 지원하고 있습니다. 일본에서는 주민 100만 명당 3,630회의 보조생식술 사이클이 기록된 반면, 인도네시아에서는 100만 명당 30회 사이클에 그치고 있으며, 지역 간 의료 접근성에 큰 격차가 있음을 보여주고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 공급망 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 제품 유형별
- 기술별
- 챔버 구성별
- 용량별
- 용도별
- 최종사용자별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽 국가
- 아시아태평양
- 중국
- 인도
- 일본
- 호주
- 한국
- 기타 아시아태평양 국가
- 중동 및 아프리카
- GCC
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 시장 점유율 분석
- 기업 개요
- ASTEC Co., Ltd.
- Binder GmbH
- Cook Medical LLC
- CooperSurgical, Inc.
- Eppendorf SE
- Esco Lifesciences Group
- Fullei Medical
- Genea Biomedx Pty Ltd.
- Hamilton Thorne Ltd.
- Heal Force Bio-Meditech Holdings Ltd.
- Kivex Biotec Ltd.
- LABOTECT GmbH
- Merck KGaA
- PHC Holdings Corporation
- Planer PLC
- Thermo Fisher Scientific Inc.
- Vitrolife AB
- Weigao Group
제7장 시장 기회와 향후 전망
KSA 26.10.23According to Mordor Intelligence, the embryo incubator market size is expected to increase from USD 106.20 million in 2025 to USD 110.20 million in 2026 and reach USD 140.60 million by 2031, growing at a CAGR of 4.98% over 2026-2031.
Global Embryo Incubator Market Trends and Insights
Rising Infertility and Delayed Parenthood
Delayed parenthood increases the need for careful embryo culture and monitoring during IVF treatment. Patients beginning treatment at older ages may require closer clinical assessment and more stable culture conditions. This supports demand for systems that manage temperature, carbon dioxide, oxygen, and humidity consistently. Public support programs in several Asian markets are bringing new patients into fertility care rather than serving only returning patients. New patient cohorts can lead to new clinic openings and complete laboratory installations, not only replacement purchases. The resulting combination of patient demand, new laboratory capacity, and higher equipment requirements provides a stable basis for the embryo incubator market over the forecast period.
Expansion of IVF and ICSI Workloads
IVF and ICSI workloads are increasing as fertility clinic networks add capacity in developing and established care markets. India had 2,616 registered IVF centers in December 2025, showing the scale of clinic infrastructure that now requires standardized laboratory equipment. ICSI requires precise post-injection culture conditions because embryos are sensitive to temperature, pH, and gas variation. Tri-gas and multiroom formats can support faster gas recovery and separate culture environments during busy laboratory schedules. Clinics that combine IVF and ICSI protocols therefore have a stronger reason to invest in systems with independent chambers and reliable environmental control. This relationship helps explain why ICSI is growing faster than the overall embryo incubator market even though IVF remains the larger application.
High Capital Cost and Limited Reimbursement
Time-lapse and tri-gas systems require a larger initial investment than conventional carbon dioxide incubators. Their cost may be difficult to justify in clinics with low cycle volumes or limited financing. Reimbursement for time-lapse monitoring remains uneven, so some clinics must recover the cost through patient fees. Quality management, validation, and regulatory documentation can add further operating expenses for smaller providers. This produces a two-tier purchasing pattern in which large fertility chains can spread investment across many cycles while independent clinics retain conventional systems. The embryo incubator market consequently has stronger premium-system penetration in urban, high-volume, and better-funded care settings.
Other drivers and restraints analyzed in the detailed report include:
- Undisturbed Time-Lapse Culture
- AI-Enabled Morphokinetic Decision Support
- Shortage of Skilled Embryologists and Service Engineers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Tri-gas incubators held 30.32% of embryo incubator market share in 2025, supported by their controlled oxygen, carbon dioxide, and nitrogen environment. Their clinical appeal rests on the ability to maintain lower oxygen conditions that more closely match the reproductive tract. The 2026 study of tri-gas blending methods reported higher clinical pregnancy outcomes for the lumen-blending configuration.
Tri-gas incubators with camera are the fastest-growing product category, with the embryo incubator market size for this segment projected to grow at an 8.36% CAGR through 2031. The format combines controlled gas conditions with continuous image capture. It reduces the tradeoff between stable culture and access to developmental observations.
Time-lapse imaging accounted for 35.46% of embryo incubator market share in 2025. It has become a leading monitoring option in clinics that can support the capital cost and data review process. The technology records embryo development inside the incubator and reduces routine dish removal for microscopy. This supports consistent observation while maintaining controlled culture conditions. Standard incubation remains widely used in lower-volume facilities and research-oriented laboratories.
AI-enabled embryo assessment is projected to grow at an 8.79% CAGR through 2031. The segment uses image data to support embryo selection and reduce reliance on manual morphokinetic review. Research published in 2025 and 2026 has shown the potential of deep-learning models to analyze time-lapse images for embryo characteristics.
Complete Report Scope:
- By Product Type
- Tri-Gas Incubators
- Tri-Gas Incubators with Camera
- Conventional CO2 Incubators
- Portable and Compact Incubators
- Benchtop Embryo Incubators
- Floor-Standing Embryo Incubators
- By Technology
- Time-Lapse Imaging
- Standard Incubation
- Microprocessor-Controlled Incubation
- AI-Enabled Embryo Assessment
- Others (Automated Environmental Monitoring, Remote Monitoring and Data Management)
- By Chamber Configuration
- Single-Chamber Incubators
- Multiroom Incubators
- Individual Embryo Chambers
- By Capacity
- Single-Embryo Incubators
- Multi-Embryo Incubators
- High-Capacity Floor-Standing Incubators
- By Application
- In Vitro Fertilization (IVF)
- Intracytoplasmic Sperm Injection (ICSI)
- Embryo Research
- Embryo Storage Support
- Others (Preimplantation Genetic Testing (PGT) Support, Fertility Preservation Procedures)
- By End User
- Fertility Clinics
- Hospitals and Research Laboratories
- Private Embryology Laboratories
- Cryobanks
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 43.21% of global embryo incubator market share in 2025. The region has a dense network of commercial fertility clinics and a strong base of premium laboratory equipment users. United States clinics often adopt time-lapse imaging and AI-supported tools early when regulatory and clinical requirements are met. The concentration of specialized clinics also supports vendor training, maintenance, and distribution networks. Insurance coverage changes in some states can expand the number of patients seeking multiple IVF cycles. This strengthens the case for clinic capacity and equipment investment. Workforce shortages in embryology also create interest in systems that can improve observation consistency and workflow efficiency.
Europe was the second-largest regional market in 2025. Scandinavia has an established culture of time-lapse use, while Germany, Spain, and the United Kingdom have large fertility clinic networks. The European Medical Device Regulation affects procurement because software and hardware vendors must meet defined regulatory requirements.
Asia-Pacific is the fastest-growing geography, with the embryo incubator market size in the region projected to grow at an 8.76% CAGR through 2031. Clinic expansion, public support measures, and a large group of underserved patients support this growth. Japan recorded 3,630 assisted reproduction cycles per million inhabitants, compared with 30 cycles per million in Indonesia, indicating substantial differences in access across the region.
- ASTEC Co., Ltd.
- Binder
- Cook Group
- The Cooper Companies
- Eppendorf
- Esco Lifesciences
- Fullei Medical
- Genea Biomedx Pty Ltd.
- Hamilton Thorne Ltd.
- Heal Force Bio-Meditech Holdings Ltd.
- Kivex Biotec Ltd.
- LABOTECT GmbH
- Merck
- PHC Holdings
- Planer PLC
- Thermo Fisher Scientific
- Vitrolife
- Weigao Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Infertility and Delayed Parenthood
- 4.2.2 Expansion of IVF and Intracytoplasmic Sperm Injection Workloads
- 4.2.3 Migration From Disturbing Spot Checks to Undisturbed Time-Lapse Culture
- 4.2.4 Fertility Clinic Capacity Expansion in Asia-Pacific and the Middle East
- 4.2.5 AI-Enabled Morphokinetic Decision Support
- 4.2.6 Lower Gas Consumption and Modular Multiroom Designs
- 4.3 Market Restraints
- 4.3.1 High Capital Cost and Limited Reimbursement
- 4.3.2 Shortage of Skilled Embryologists and Service Engineers
- 4.3.3 Validation Burden for Imaging and Embryo-Assessment Software
- 4.3.4 Gas, Sensor, and Replacement-Part Supply Concentration
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Tri-Gas Incubators
- 5.1.2 Tri-Gas Incubators with Camera
- 5.1.3 Conventional CO2 Incubators
- 5.1.4 Portable and Compact Incubators
- 5.1.5 Benchtop Embryo Incubators
- 5.1.6 Floor-Standing Embryo Incubators
- 5.2 By Technology
- 5.2.1 Time-Lapse Imaging
- 5.2.2 Standard Incubation
- 5.2.3 Microprocessor-Controlled Incubation
- 5.2.4 AI-Enabled Embryo Assessment
- 5.2.5 Others (Automated Environmental Monitoring, Remote Monitoring and Data Management)
- 5.3 By Chamber Configuration
- 5.3.1 Single-Chamber Incubators
- 5.3.2 Multiroom Incubators
- 5.3.3 Individual Embryo Chambers
- 5.4 By Capacity
- 5.4.1 Single-Embryo Incubators
- 5.4.2 Multi-Embryo Incubators
- 5.4.3 High-Capacity Floor-Standing Incubators
- 5.5 By Application
- 5.5.1 In Vitro Fertilization (IVF)
- 5.5.2 Intracytoplasmic Sperm Injection (ICSI)
- 5.5.3 Embryo Research
- 5.5.4 Embryo Storage Support
- 5.5.5 Others (Preimplantation Genetic Testing (PGT) Support, Fertility Preservation Procedures)
- 5.6 By End User
- 5.6.1 Fertility Clinics
- 5.6.2 Hospitals and Research Laboratories
- 5.6.3 Private Embryology Laboratories
- 5.6.4 Cryobanks
- 5.6.5 Other End Users
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 India
- 5.7.3.3 Japan
- 5.7.3.4 Australia
- 5.7.3.5 South Korea
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 Middle East and Africa
- 5.7.4.1 GCC
- 5.7.4.2 South Africa
- 5.7.4.3 Rest of Middle East and Africa
- 5.7.5 South America
- 5.7.5.1 Brazil
- 5.7.5.2 Argentina
- 5.7.5.3 Rest of South America
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.3.1 ASTEC Co., Ltd.
- 6.3.2 Binder GmbH
- 6.3.3 Cook Medical LLC
- 6.3.4 CooperSurgical, Inc.
- 6.3.5 Eppendorf SE
- 6.3.6 Esco Lifesciences Group
- 6.3.7 Fullei Medical
- 6.3.8 Genea Biomedx Pty Ltd.
- 6.3.9 Hamilton Thorne Ltd.
- 6.3.10 Heal Force Bio-Meditech Holdings Ltd.
- 6.3.11 Kivex Biotec Ltd.
- 6.3.12 LABOTECT GmbH
- 6.3.13 Merck KGaA
- 6.3.14 PHC Holdings Corporation
- 6.3.15 Planer PLC
- 6.3.16 Thermo Fisher Scientific Inc.
- 6.3.17 Vitrolife AB
- 6.3.18 Weigao Group
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-need assessment


