

|
시장보고서
상품코드
2154331
교정 장비 및 서비스 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Calibration Equipment and Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
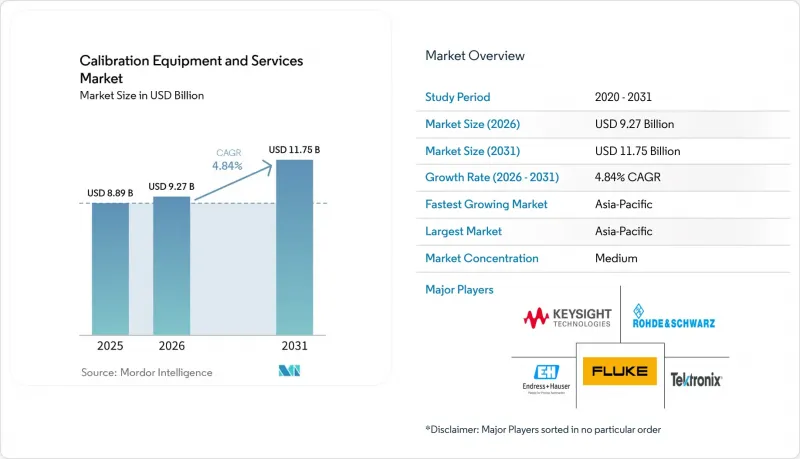
에 따르면 교정 장비 및 서비스 시장 규모는 2025년 88억 9,000만 달러, 2026년 92억 7,000만 달러에서 2031년까지 117억 5,000만 달러로 확대할 것으로 예측되고 있으며, 2026-2031년까지 연평균 성장률(CAGR)은 4.84%에 달할 전망입니다.
전 세계 교정 장비 및 서비스 시장의 동향과 인사이트
규제 준수 및 품질 기준 강화
규제 준수는 교정 장비 및 서비스 시장 수요의 주요 요인입니다. ISO/IEC 17025 인증은 제약, 항공우주 및 의료기기 고객에게 서비스를 제공하는 시험소에게 사실상 시장 진입 요건이 되었습니다. 각국의 인증 기관은 이 프레임워크를 적용하여 시험소의 역량과 추적성을 확인하고 있습니다. 미국 식품의약국(FDA)은 2026년 7월 ‘시험소 인증 프로그램’ 지침을 개정하여, 관련 교정 시험소에 대한 ISO/IEC 17025:2023 인증을 승인했습니다. 21 CFR Part 820 및 EU 의료기기 규정 2017/745에 기반한 의료기기 요건 또한 관리된 기록의 필요성을 높이고 있습니다. 위험 기반 일정 설정을 통해 안정적인 기기의 교정 빈도를 줄일 수 있지만, 동시에 추적 가능성이 보장된 교정 대상 기기의 범위를 확대하게 됩니다. 인증받은 업무와 접근성이 뛰어난 디지털 기록을 결합한 공급자는 감사 요건을 충족하는 데 있으며, 더 유리한 입장에 있습니다.
자동화 및 산업 디지털화의 진전
자동화의 발전에 따라 교정 장비 및 서비스 시장에서 추적 가능한 검증이 필요한 센서, 트랜스미터, 액추에이터의 수가 증가하고 있습니다. 측정 지점이 하나 추가될 때마다 폐쇄 루프 제어에 영향을 미치기 때문에 신뢰성이 높은 기준 표준기가 필요합니다. NIST는 0.01 cm3/min에서 1,000cm3/min의 유량 범위에서 불확실성을 0.056%에서 0.098%로 확대한 반도체 공정 가스용 SLowFlowS 규격을 개발했습니다. 이러한 노력은 첨단 생산 시스템이 지금까지 존재하지 않았던 교정 인프라에 대한 수요를 어떻게 창출하고 있는지를 보여줍니다. 플루크(Fluke)는 2025년, 보다 효율적인 디지털 측정 워크플로우를 목표로 하는 제품으로 교정 포트폴리오를 개편했습니다. 네트워크로 연결된 계측기는 시간 경과에 따른 드리프트 이력을 구축하여 보다 정확한 일정 수립을 지원합니다. 이 기능 덕분에 공급업체 수익의 일부가 일회성 실험실 작업에서 소프트웨어 기반 지원이 포함된 서비스 계약으로 전환되고 있습니다.
고급 교정 장비 및 서비스의 높은 비용
장비 및 서비스의 높은 비용은 교정 장비 및 서비스 시장에서의 도입을 제한하는 요인이 될 수 있습니다. 특히 신흥 시장의 소규모 제조업체나 공급업체의 경우 이러한 경향이 두드러집니다. 다기능 교정기, 고정밀 압력 표준기, 그리고 온도 제어 실험실에는 막대한 설비 투자가 필요합니다. 인증 취득에는 능력 시험, 기준 표준기의 유지 관리 및 환경 제어에 드는 비용이 추가됩니다. 제공된 조사 데이터에 따르면 이러한 요건으로 인해 인증을 받지 않은 대안과 비교하여 운영 비용이 15-25% 증가할 가능성이 있습니다. 소프트웨어 통합 기능을 갖춘 고사양의 문서화 지원 교정기는 매출 기준 5-7%의 성장을 보이고 있는 반면, 보급형 제품은 연간 2-3%의 가격 압박에 직면해 있습니다. 고급 장비의 리드타임이 12-20주 소요된다는 점도 장비 교체를 지연시켜 규정 준수 문제를 야기할 수 있습니다. 이러한 비용 격차로 인해 기본적인 업무는 가격 경쟁에 노출되는 반면, 전문적인 인증 업무에는 프리미엄 가격이 유지되고 있습니다.
부문 분석
2025년 기준, 교정 서비스는 교정 장비 및 서비스 시장 점유율의 58.29%를 차지했습니다. 이러한 상황은 사내에 완벽한 계측 장비 체계를 구축하기 위한 투자보다 검증 업무를 외부에 위탁하는 것을 선호하는 경향을 반영하고 있습니다. 자동화의 진전에 따라 정기적인 점검이 필요한 기기의 수가 증가하고 있습니다. 전문 서비스 제공업체는 많은 고객에게 동일한 기준 표준기를 재사용할 수 있으므로 1회당 비용을 절감할 수 있습니다. 이러한 구조로 인해 다양한 기기를 보유하고 사내 계측 팀이 제한적인 시설의 경우, 외부 위탁이 더 현실적인 선택지가 되고 있습니다. 교정 서비스 시장은 2031년까지 연평균 성장률(CAGR) 5.56%로 확대될 것으로 예측됩니다. 생명과학, 항공우주·방위, 반도체 분야의 고객들이 이러한 성장을 지원하고 있습니다. 이러한 분야에서는 비공식적인 사내 프로그램만으로는 문서화 요건을 충족하기 어렵기 때문입니다. 또한 이러한 사용자들은 품질 기록에 포함시킬 수 있는 신뢰성 높은 일정 관리와 인증서를 필요로 합니다.
서비스 제공업체와 사내 시험소가 신뢰할 수 있는 표준 측정기를 필요로 하므로 측정 기기의 중요성은 여전히 높습니다. 측정 기기 및 서비스 시장의 규모는 자동화 및 소프트웨어 통합형 기기로의 전환에 힘입어 성장하고 있지만, 측정 기기 단독 시장 규모에 대해서는 별도로 제시되지 않았습니다. 각 제조사는 기본적인 산업 용도와 고정밀 실험실용 모두를 위한 제품을 개발하고 있습니다. 플루크(Fluke)는 2025년 8월, 산업 용도를 위한 저가형 ‘5530A 베이직 멀티프로덕트 캘리브레이터’를 출시했습니다. 또한 이 회사는 0.2-0.5 ppm의 정밀도와 자동 측정 데이터 수집 기능을 갖춘 ‘8588A 레퍼런스 멀티미터’용 누르미터 옵션도 도입했습니다. 이러한 접근 방식은 고정밀도를 필요로 하는 일상적인 산업 사용자 및 실험실의 요구를 충족시킵니다. 비용 대비 정밀도 비율의 향상을 통해 추적 가능한 검증이 필요한 계측기의 기반을 확대할 수 있습니다. 또한 장비 공급업체는 자사 제품이 교정 관리 소프트웨어 및 서비스 네트워크와 연동함으로써 더 많은 비즈니스 기회를 얻을 수 있습니다.
2025년 기준, 전기 교정 기기는 기기 부문의 24.56%를 차지했습니다. 이 분야는 전원 장치, 멀티미터, RF 신호 발생기, 오실로스코프 등 폭넓은 도입 기반을 지원하고 있습니다. 이러한 광범위한 적용 범위 덕분에 산업 현장과 실험실에서 전기 관련 작업은 필수 불가결한 요소가 되었습니다. 대만과 한국의 반도체 제조 공장에서는 정교한 공정 제어를 위해 전기적 추적 가능성이 요구되고 있습니다. 또한 압력·온도 측정 기기는 석유 및 가스, 화학, 제약 분야의 주요 업무를 지원하고 있습니다. 유량 교정은 에너지 계측 요건에 따라 수요가 증가하고 있습니다. 치수 교정은 항공우주, 자동차 및 정밀 공구의 공급망을 지원하고 있습니다. 가스 및 습도 표준기를 포함한 기타 제품은 환경 모니터링 및 HVAC 시스템의 특수한 요구 사항을 충족시키고 있습니다.
다기능 공정 교정기는 2031년까지 연평균 성장률(CAGR) 5.81%로 확대될 것으로 예측됩니다. 단일 장비로 현장 작업 중의 압력, 온도, 전기적 매개변수를 관리할 수 있습니다. 이를 통해 기술자의 이동 횟수가 줄어들고, 플랜트 턴어라운드시 필요한 개별 기준 표준기의 수가 감소합니다. 이러한 이점은 연속 공정 시설에서 교정에 할애할 수 있는 시간이 제한적인 경우에 특히 중요합니다. 또한 교정 장비 및 서비스 시장은 고주파 전기 시험의 증가에도 영향을 받고 있습니다. NIST의 CalNet 프로젝트는 까다로운 반도체 및 고주파 애플리케이션에서 더욱 강력한 추적성이 필요함을 시사하고 있습니다. 키사이트의 AI 데이터센터 검증 시스템은 고속 상호 연결에 관한 새로운 시험 요건을 충족합니다. 공급업체는 전문 장비를 활용함으로써 기본적인 제품 가격 압박에 덜 노출되는 고부가가치 업무를 지원할 수 있습니다.
지역별 분석
아시아태평양은 2025년에 교정 장비 및 서비스 시장 점유율의 31.33%를 차지할 것으로 예상되며, 2031년까지 연평균 성장률(CAGR) 5.60%로 확대될 것으로 전망됩니다. 중국의 계측 교정 서비스 시장은 2025년에 126억 위안(17억 4,000만 달러 상당)에 달했습니다. 반도체의 현지 생산, 신에너지차 생산, 그리고 ‘제14차 5개년 계량 개발 계획’이 중국내 추적성 서비스 수요를 지원하고 있습니다. 인도는 전자기기 제조 및 의약품 수출에 대한 규정 준수 요건의 혜택을 받고 있습니다. 싱가포르, 말레이시아, 태국, 베트남은 통합된 전자기기·반도체 회랑을 형성하고 있으며, 교정 수요가 증가하고 있습니다. ILAC에 기반한 상호인정협정 덕분에 지역 공급업체들은 국경을 초월한 고객 지원이 더욱 용이해졌습니다. 현지 인증 기관을 통해 다국적 제조업체는 더 신속한 서비스 경로와 익숙한 문서 작성 관행을 활용할 수 있게 됩니다.
북미는 조사 대상 지역 중 두 번째로 큰 시장입니다. FDA(미국 식품의약국), FAA(연방항공청), NIST(미국 국립표준기술연구소)는 제약, 항공우주, 방위 분야 고객을 대상으로 정교한 일련의 측정 요건을 규정하고 있습니다. 이러한 분야에서는 빈번한 교정과 짧은 납기가 요구됩니다. Transcat사는 2025년에 8,400만 달러에 Essco사를 인수하여 북미 서비스 네트워크를 확장했습니다. 유럽에는 대규모 인증 시험소 기반이 있으며, 독일이 1,200곳 이상의 DAkkS 인증 시설을 보유하며 주도적인 위치를 차지하고 있으며, 이는 유럽연합(EU) 전체의 28%를 차지합니다. 자동차 업계의 IATF 16949 요구 사항과 의료기기의 적합성 규정이 이 지역의 수요를 지원하고 있습니다. 2026년 7월, TUV SUD National Engineering Laboratory는 국가 측정 시스템(NEL)의 유량 프로그램과 관련하여 1,540만 파운드(2,000만 달러 상당) 규모의 계약을 수주했습니다. 이 투자는 1차 유량 계측 및 보다 광범위한 인증 시험소 네트워크를 지원하기 위한 것입니다.
남미, 중동 및 아프리카는 교정 장비 및 서비스 시장에서 아직 발전 단계에 있는 지역입니다. 산업 인프라, 광업 및 수입 규정 준수 요건으로 인해 교정된 장비에 대한 수요가 증가하고 있습니다. 2026년 4월, 트랜스캣이 코스타리카의 SCM 메트롤로지를 인수함으로써 남미의 생명과학 및 정밀 제조 분야 고객을 위한 서비스 플랫폼이 구축되었습니다. 뷰로베리타스는 2025년 3월 칠레의 지오어세이를 인수하여 구리 밸류체인내 광물 시험 사업의 입지를 강화했습니다. 브라질은 석유화학, 농업, 자동차 생산을 통해 광범위한 지역 기반을 제공하고 있습니다. 사우디아라비아와 아랍에미리트(UAE)는 첨단 제조, 제약, 식품, 재생 가능 에너지에 대한 투자를 확대하고 있습니다. 이러한 동향은 새로운 산업 거점 인근에서 업무를 수행할 수 있는 인증 시험소에게 비즈니스 기회를 창출하고 있습니다. 또한 도입 기반이 비교적 소규모이기 때문에 현지 규정 준수 체계가 성숙해짐에 따라 서비스 제공업체는 고객과 장기적인 관계를 구축할 기회를 얻을 수 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 업계 밸류체인 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
- 시장에서의 거시경제 동향 평가
제5장 시장 규모와 성장 예측
- 제공별
- 장비 유형별
- 서비스 유형별
- 인정별
- 최종사용자 산업별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽 국가
- 아시아태평양
- 중국
- 일본
- 인도
- 한국
- ASEAN
- 기타 아시아태평양 국가
- 중동 및 아프리카
- 중동
- 사우디아라비아
- 아랍에미리트
- 튀르키예
- 기타 중동 국가
- 아프리카
- 남아프리카공화국
- 나이지리아
- 기타 아프리카 국가
- 중동
- 북미
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Fluke Corporation
- Keysight Technologies
- Endress+Hauser Group Services AG
- Rohde & Schwarz
- Tektronix, Inc.
- WIKA Instruments Ltd.
- Yokogawa Electric Corporation
- Mitutoyo Europe GmbH
- Mahr GmbH
- Ametek Inc.
- SGS SA
- Bureau Veritas
- Intertek Group plc
- TUV SUD
- DEKRA SE
- Transcat Inc.
- Illinois Tool Works Inc.
- NATIONAL INSTRUMENTS CORP.
- Additel Corporation
- Mettler Toledo
제7장 시장 기회와 향후 전망
KSA 26.10.23According to Mordor Intelligence, the calibration equipment and services market size is projected to expand from USD 8.89 billion in 2025 and USD 9.27 billion in 2026 to USD 11.75 billion by 2031, registering a CAGR of 4.84% between 2026 to 2031.
Global Calibration Equipment and Services Market Trends and Insights
Increasing Regulatory Compliance and Quality Standards
Regulatory compliance is a major source of demand for the calibration equipment and services market. ISO/IEC 17025 accreditation has become a practical market-access requirement for laboratories serving pharmaceutical, aerospace, and medical device customers. National accreditation bodies apply this framework to confirm laboratory competence and traceability. The U.S. Food and Drug Administration updated its Laboratory Accreditation Program guidance in July 2026 to recognize ISO/IEC 17025:2023 accreditation for relevant calibration laboratories. Medical device requirements under 21 CFR Part 820 and EU Medical Device Regulation 2017/745 also increase the need for controlled records. Risk-based scheduling can reduce calibration frequency for stable instruments, but it also extends traceable calibration to a larger instrument population. Providers that combine accredited work with accessible digital records are better placed to meet audit requirements.
Rising Automation and Industrial Digitization
Automation increases the number of sensors, transmitters, and actuators that need traceable verification in the calibration equipment and services market. Each added measurement point affects closed-loop control and, therefore, requires dependable reference standards. NIST developed the SLowFlowS standard for semiconductor process gases with expanded uncertainty from 0.056% to 0.098% across flows from 0.01 cm3/min to 1,000 cm3/min. This work shows how advanced production systems create demand for calibration infrastructure that did not previously exist. Fluke updated its calibration portfolio in 2025 with products aimed at more efficient digital measurement workflows. Connected instruments can build drift histories over time and support more informed scheduling. That capability shifts part of provider revenue from one-off laboratory events toward software-supported service agreements.
High Cost of Advanced Calibration Equipment and Services
High equipment and service costs can limit adoption in the calibration equipment and services market, particularly for smaller manufacturers and providers in emerging markets. Multifunction calibrators, precision pressure references, and temperature-controlled laboratories require significant capital investment. Accreditation adds costs for proficiency testing, reference-standard maintenance, and environmental controls. The supplied research base indicates that these requirements can add 15-25% to operating costs compared with non-accredited alternatives. High-specification documenting calibrators with software integration were growing at 5-7% in revenue terms, while entry-level products faced 2-3% annual price compression. Lead times of 12-20 weeks for advanced tools can also delay replacement and create compliance challenges. This cost divide leaves basic work exposed to price competition while maintaining a premium for specialized accredited work.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Precision Manufacturing and High-Accuracy Applications
- Increasing Outsourcing of Calibration Activities
- Shortage of Skilled Calibration Professionals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Calibration services held 58.29% of the calibration equipment and services market share in 2025. This position reflects the preference for outsourced verification rather than investment in a full internal instrument estate. Automation expands the number of instruments that require routine checks. Specialist providers can use their reference standards across many clients, reducing the cost of each event. That structure makes outsourcing more practical for facilities with varied equipment and limited in-house metrology teams. Calibration services are projected to expand at a CAGR of 5.56% through 2031. Life sciences, aerospace and defense, and semiconductor customers support this growth because their documentation requirements are difficult to meet through informal internal programs. These users also need dependable scheduling and certificates that can enter their quality records.
Equipment remains important because service providers and internal laboratories need reliable reference tools. The calibration equipment and services market size for equipment benefits from a shift toward automated and software-integrated devices, though no separate equipment value is provided. Manufacturers are developing products for both basic industrial work and high-precision laboratories. Fluke launched the 5530A Basic Multi-Product Calibrator in August 2025 for industrial workloads at a lower price point. The company also introduced a Null Meter option for the 8588A Reference Multimeter with 0.2-0.5 ppm accuracy and automated measurement collection. This approach addresses routine industrial users and laboratories that need high accuracy. Better cost-to-accuracy ratios can widen the base of instruments that require traceable verification. Equipment suppliers also gain opportunities when their products work with calibration management software and service networks.
Electrical calibration equipment held 24.56% of the equipment segment in 2025. It supports a broad installed base that includes power supplies, multimeters, RF signal generators, and oscilloscopes. This breadth makes electrical work essential across industrial and laboratory settings. Semiconductor fabrication plants in Taiwan and South Korea require electrical traceability for advanced process control. Pressure and temperature equipment serve major workloads in oil and gas, chemicals, and pharmaceuticals. Flow calibration benefits from energy-metering requirements. Dimensional calibration supports aerospace, automotive, and precision-tooling supply chains. Other products, including gas and humidity standards, meet specialized needs in environmental monitoring and HVAC systems.
Multifunction process calibrators are projected to expand at a CAGR of 5.81% through 2031. A single device can manage pressure, temperature, and electrical parameters during field work. This reduces technician travel and the number of separate reference standards needed during plant turnarounds. The advantage matters when a continuous-process facility has limited time for calibration. The calibration equipment and services market is also influenced by higher-frequency electrical testing. NIST's CalNet work signals a need for stronger traceability in demanding semiconductor and high-frequency applications. Keysight's AI data center validation systems address new testing requirements for high-speed interconnects. Providers can use specialized equipment to support premium work that is less exposed to basic product pricing pressure.
Complete Report Scope:
- By Offering
- Calibration Equipment
- Calibration Services
- By Equipment Type
- Electrical Calibration Equipment
- Pressure Calibration Equipment
- Temperature Calibration Equipment
- Flow Calibration Equipment
- Dimensional Calibration Equipment
- Multifunction Process Calibrators
- Other Equipment Types
- By Service Type
- Laboratory Calibration
- On-Site Calibration
- By Accreditation
- Accredited Calibration
- Non-Accredited Calibration
- By End-user Industry
- Industrial Manufacturing
- Aerospace and Defense
- Automotive
- Oil and Gas
- Pharmaceuticals and Biotechnology
- Medical Devices and Healthcare
- Electronics and Semiconductor
- Power and Utilities
- Food and Beverage
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of the Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific held 31.33% of the calibration equipment and services market share in 2025 and is projected to expand at a CAGR of 5.60% through 2031. China's metrology calibration services market reached CNY 12.6 billion, equivalent to USD 1.74 billion, in 2025. Semiconductor localization, new energy vehicle production, and the 14th Five-Year Metrology Development Plan support the country's demand for traceable services. India benefits from electronics manufacturing and pharmaceutical export compliance requirements. Singapore, Malaysia, Thailand, and Vietnam form an integrated electronics and semiconductor corridor with growing calibration needs. Mutual recognition arrangements under ILAC make it easier for regional providers to support cross-border customers. Local accredited facilities give multinational manufacturers access to shorter service routes and familiar documentation practices.
North America is the second-largest regional market in the supplied research base. The FDA, Federal Aviation Administration, and NIST create a dense set of measurement requirements for pharmaceutical, aerospace, and defense customers. These sectors need high-frequency calibration and short turnaround times. Transcat expanded its North American service network through the USD 84 million Essco acquisition in 2025. Europe has a large accredited laboratory base, led by Germany with more than 1,200 DAkkS-accredited facilities, representing 28% of the European Union total. Automotive IATF 16949 requirements and medical device conformity rules support demand in the region. In July 2026, TUV SUD National Engineering Laboratory received a GBP 15.4 million contract, equivalent to USD 20 million, for the National Measurement System NEL Flow Programme. This investment supports primary flow metrology and the broader accredited laboratory network.
South America and the Middle East and Africa are earlier-stage areas for the calibration equipment and services market. Industrial infrastructure, mining, and import compliance requirements are increasing the need for calibrated equipment. Transcat's April 2026 acquisition of SCM Metrology in Costa Rica created a service platform for life sciences and precision manufacturing customers in South America. Bureau Veritas acquired GeoAssay in Chile in March 2025 to deepen its minerals testing presence in the copper value chain. Brazil provides a large regional base through petrochemicals, agriculture, and automotive production. Saudi Arabia and the UAE are increasing investment in advanced manufacturing, pharmaceuticals, food, and renewable energy. These developments create room for accredited laboratories that can work near new industrial sites. The smaller installed base also gives providers an opportunity to establish long-term customer relationships as local compliance systems mature.
- Fluke Corporation
- Keysight Technologies
- Endress+Hauser Group Services AG
- Rohde & Schwarz
- Tektronix, Inc.
- WIKA Instruments Ltd.
- Yokogawa Electric Corporation
- Mitutoyo Europe GmbH
- Mahr GmbH
- Ametek Inc.
- SGS SA
- Bureau Veritas
- Intertek Group plc
- TUV SUD
- DEKRA SE
- Transcat Inc.
- Illinois Tool Works Inc.
- NATIONAL INSTRUMENTS CORP.
- Additel Corporation
- Mettler Toledo
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Regulatory Compliance and Quality Standards
- 4.2.2 Rising Automation and Industrial Digitization
- 4.2.3 Growth of Precision Manufacturing and High-Accuracy Applications
- 4.2.4 Increasing Outsourcing of Calibration Activities
- 4.2.5 Expansion of Safety-Critical Industries
- 4.2.6 Growing Adoption of Digital Calibration Management Solutions
- 4.3 Market Restraints
- 4.3.1 High Cost of Advanced Calibration Equipment and Services
- 4.3.2 Shortage of Skilled Calibration Professionals
- 4.3.3 Availability of Low-Cost Alternatives and In-House Calibration
- 4.3.4 Long Equipment Replacement Cycles and Limited Calibration Frequency
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Macroeconomic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Offering
- 5.1.1 Calibration Equipment
- 5.1.2 Calibration Services
- 5.2 By Equipment Type
- 5.2.1 Electrical Calibration Equipment
- 5.2.2 Pressure Calibration Equipment
- 5.2.3 Temperature Calibration Equipment
- 5.2.4 Flow Calibration Equipment
- 5.2.5 Dimensional Calibration Equipment
- 5.2.6 Multifunction Process Calibrators
- 5.2.7 Other Equipment Types
- 5.3 By Service Type
- 5.3.1 Laboratory Calibration
- 5.3.2 On-Site Calibration
- 5.4 By Accreditation
- 5.4.1 Accredited Calibration
- 5.4.2 Non-Accredited Calibration
- 5.5 By End-user Industry
- 5.5.1 Industrial Manufacturing
- 5.5.2 Aerospace and Defense
- 5.5.3 Automotive
- 5.5.4 Oil and Gas
- 5.5.5 Pharmaceuticals and Biotechnology
- 5.5.6 Medical Devices and Healthcare
- 5.5.7 Electronics and Semiconductor
- 5.5.8 Power and Utilities
- 5.5.9 Food and Beverage
- 5.5.10 Other End-User Industries
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 ASEAN
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of the Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Fluke Corporation
- 6.4.2 Keysight Technologies
- 6.4.3 Endress+Hauser Group Services AG
- 6.4.4 Rohde & Schwarz
- 6.4.5 Tektronix, Inc.
- 6.4.6 WIKA Instruments Ltd.
- 6.4.7 Yokogawa Electric Corporation
- 6.4.8 Mitutoyo Europe GmbH
- 6.4.9 Mahr GmbH
- 6.4.10 Ametek Inc.
- 6.4.11 SGS SA
- 6.4.12 Bureau Veritas
- 6.4.13 Intertek Group plc
- 6.4.14 TUV SUD
- 6.4.15 DEKRA SE
- 6.4.16 Transcat Inc.
- 6.4.17 Illinois Tool Works Inc.
- 6.4.18 NATIONAL INSTRUMENTS CORP.
- 6.4.19 Additel Corporation
- 6.4.20 Mettler Toledo
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


