

|
시장보고서
상품코드
2154369
두개골 교정 기구 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Cranial Orthoses - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
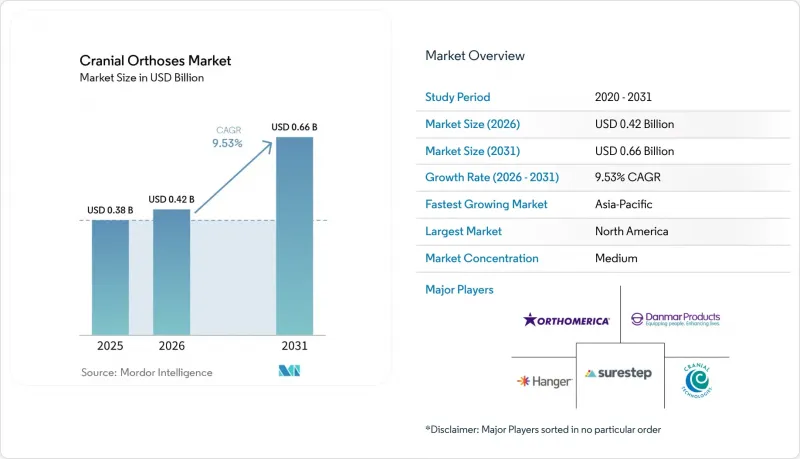
에 따르면 두개 보조기 시장 규모는 2025년 3억 8,000만 달러, 2026년 4억 2,000만 달러에서 2031년까지 6억 6,000만 달러로 확대할 것으로 예측되고 있으며, 2026-2031년까지 연평균 성장률(CAGR)은 9.53%에 달할 전망입니다.
전 세계 두개골 교정 기구 시장의 동향 및 인사이트
체위성 사두증 진단 건수의 증가
편두증 및 단두증의 진단 건수 증가는 진단을 계기로 임상 모니터링, 전문의 의뢰, 교정기 착용 및 경과 관찰이 이루어지기 때문에 두개골 교정기 시장의 주요 성장 동인으로 계속 작용하고 있습니다. 2024년에 실시된 인구 기반 연구에 따르면 만삭아의 발생률은 5.8%, 조산아의 발생률은 11.8%로 보고되어, 조산이 중요한 위험 요인임이 부각되었습니다. 2026년 베이징에서 2,165명의 조산아를 대상으로 실시된 연구에서는 생후 0-2개월 영아의 81.2%에서 자세성 두개 이상이 확인되었으며, 이는 조사 대상 연령대 중 가장 높은 비율이었습니다. 이러한 연구 결과는 권장되는 3-8개월의 치료 기간 중 두부 형태의 조기 모니터링, 보존적 체위 교정, 임상 관찰 및 적시 의뢰의 필요성을 강조하고 있습니다. 효과적인 선별 검사, 보호자에 대한 의식의 향상, 의료진의 인식 향상, 그리고 적절한 의뢰 체계 구축을 통해 치료 지연을 줄이고 시장의 수요에 부응할 수 있습니다.
소아 환자의 전원율 및 조기 개입율 증가
체계화된 의뢰 경로를 통해 진단 후 치료 접근성이 개선되고 있습니다. 특히 평가와 보조기 착용이 동일한 임상 시스템 내에서 통합된 경우 그 효과가 두드러집니다. 슈라이너스 칠드런스 뉴잉글랜드는 2025년 5월, 3D 스캔을 보조기 제작 워크플로우에 통합한 두개골 성형 프로그램을 시작하여, 가족들이 한 번의 내원만으로 스캔과 피팅을 완료할 수 있도록 했습니다. 이 모델을 통해 소아과 의사, 전문의, 보조기사, 가족, 보험사 간의 연계 및 인계 과정이 줄어들어, 이로 인해 발생하기 쉬운 치료 지연을 방지할 수 있습니다. 또한 병원에 본사를 둔 서비스에서는 동일한 시설 내에서 보조기사나 소아 전문의가 대응할 수 있으므로, 의뢰 절차도 간소화됩니다. 조기 치료의 중요성이 널리 인식됨에 따라 적시적인 개입이 촉진되고, 두개골 보조기 시장의 수요도 증가하고 있습니다.
중등도 증례에서 점진적 효과를 둘러싼 임상적 논의
중등도 두개 변형증 치료에 관한 임상적 의견 차이는 특히 임상의나 보험자가 보존적 치료를 우선시하는 경우, 두개 교정 장치 시장에서의 의뢰 지연으로 이어질 가능성이 있습니다. 2015년 1월부터 2025년 1월까지의 기간을 대상으로 한 체계적 문헌인사이트에 따르면 헬멧 치료를 받은 영아의 월별 교정률은 0.66, 보존적 치료를 받은 영아는 0.64였습니다. 헬멧 치료를 받은 사례의 25%가 중증도 1단계에 도달한 반면, 보존적 치료를 받은 사례에서는 11%에 그쳤으나, 이용 가능한 전체 시험 데이터에서 볼 때 이 차이는 통계적으로 유의미하지 않았습니다. 피부 자극, 영아의 치료 순응도, 보호자의 부담에 대한 우려로 인해 중등도로 진단된 사례에서 치료법 전환이 더욱 감소하고 있으며, 이는 시장의 잠재적 규모를 제한하고 있습니다.
부문 분석
2025년, 액티브 헬멧은 두개골 교정 장치 시장의 56.45% 점유율을 차지했습니다. 이는 확립된 승인 실적, 장기간의 임상 사용, 그리고 치료 네트워크에 통합된 독자적인 디지털 스캔 시스템에 힘입은 결과입니다. Cranial Technologies사의 ‘DOC Band’는 디지털 표면 이미징(Digital Surface Imaging) 기술을 사용하여 1초도 채 걸리지 않는 시간에 완전한 3D 두부 모델을 캡처하고, 개량형 폴리에틸렌 폼으로 만들어진 내부 구조 내에서 성장 여지를 고려한 배치를 안내합니다. 이러한 워크플로우를 통해 능동적인 교정 접근 방식을 유지하면서 일관된 피팅과 경과 관찰이 가능해집니다. 치료를 받은 영아 27,990명을 대상으로 한 10년간의 추적 조사에서 두개 돔 비대칭 지수의 평균 감소폭은 3.42퍼센트 포인트였으며, 환자의 87.6%가 적어도 1단계의 중증도 범주에서 개선을 보였습니다.
비용에 민감한 지역이나 신흥 시장의 의료 서비스 제공자들이 스캔에 대한 투자를 최소화하고, 보다 단순한 생산 인프라로 충분한 열가소성 수지 재질의 디자인을 채택함에 따라 패시브형 헬멧 시장은 2031년까지 연평균 성장률(CAGR) 12.87%로 확대될 것으로 예측됩니다. 능동형 및 수동형 디자인은 각각 서로 다른 임상 워크플로우와 의료 서비스 제공자의 투자 수준에 부응합니다. 두개골 봉합 조기 유합증 수술 후 등 개별적인 형태가 요구되는 상황에서는 맞춤형으로 성형된 장치가 여전히 중요한 역할을 하고 있습니다. 기성형 보호 제품은 치료적 두개골 재형성 서비스가 제한된 지역을 대상으로 하며, 이를 통해 시장은 첨단 디지털 클리닉과 자원이 제한된 환경 모두에 대응할 수 있게 됩니다.
2025년, 두개 교정 보조기 시장 규모의 54.34%를 사두증이 차지하고 있으며, 이는 ‘백 투 슬립(Back to Sleep)’ 캠페인 이후에도 사두증이 가장 일반적인 치료 적응증이며, 진단 유병률이 지속되고 있음을 반영합니다. 생후 2개월 및 4개월 영유아 건강검진시 선별 검사를 통해 진단된 영아의 상당수가, 연령에 따른 교정 가능성이 떨어지기 전에 편두증에 특화된 치료 경로로 안내되고 있습니다. 의뢰 시기와 질은 의료제도에 따라 다르지만, 조기 발견을 통해 예측 가능한 환자 수를 확보할 수 있습니다. 따라서 편평두증은 계속해서 두개 교정 장치 시장을 지탱하는 주요 적응증이 되고 있습니다.
단두증은 정기 검진에서의 인식도 제고를 배경으로, 2031년까지 연평균 성장률(CAGR) 11.56%로 성장할 것으로 예측됩니다. 2026년 베이징에서 실시된 연구에 따르면 단두증의 검출률은 생후 3-4개월 코호트에서 9.0%였던 반면, 생후 5-6개월 코호트에서는 19.8%로 증가한 것으로 나타났습니다. 주상두증은 시상 봉합선의 조기 유합 후 전문적인 수술 후 피팅이 필요하지만, 2025년 행거 연구소의 조사를 통해 환자 평가를 위한 표준화된 두개골 측정 지표가 제시되었습니다. 수술 후 두개골 변형은 사례 수가 적음에도 불구하고 헬멧 사용이 외과적 치료의 일환으로 포함되어 있으며 일반적으로 보험 적용을 받기 때문에 시장 가치가 높습니다.
지역별 분석
북미는 2025년 매출의 39.56%를 차지했으며, 성숙한 소아 의료 시스템, 광범위한 보조기사 기반, 그리고 병원에 통합된 3D 스캔 서비스에 힘입었습니다. 미국에서는 확립된 전문의 네트워크와 점차 확대되는 보험 환급 접근성을 통해 지역적 수요를 견인했습니다. 텍사스주는 2025년 6월 HB 426을 제정하여, 2025년 9월부터 사두증을 앓는 영아에 대한 두개형성 보조기에 대해 메디케이드 및 CHIP을 통한 보험 적용을 의무화했습니다. 한편, 노스캐롤라이나주 메디케이드는 2024년 9월에 임상 보험 적용 지침 5B를 개정했습니다. 미국 카운티의 40% 이상에서는 반경 100마일 이내에 미국 구개열·두개안면협회(ACPA) 인증 팀을 이용할 수 없어, 이로 인해 이동형 스캔 및 원격 후속 관리 서비스에 대한 수요가 증가하고 있습니다. 캐나다에서는 대부분의 주에서 보험 적용이 이루어지고 있지만, 멕시코는 의료비 지출이 낮고 전문의 인프라도 제한적이어서 여전히 소규모 시장에 머물러 있습니다.
아시아태평양은 임상적 수요와 의료 기관의 역량 확대에 힘입어 2031년까지 연평균 성장률(CAGR) 12.98%로 성장할 것으로 예측되며, 이는 세계 평균보다 3퍼센트 포인트 이상 높은 수치입니다. 일본의 연구에 따르면 생후 2-23개월 영아의 57.4%에서 체위성 사두증이 확인되었으며, 2026년 베이징에서 실시된 2,165명의 조산아를 대상으로 한 연구에서는 생후 0-2개월 영아의 81.2%에서 자세성 두개골 이상이 확인되었습니다. 싱가포르의 KKH는 2025년 6월, 해당 지역 최초의 두개골 성형 전문 시설인 ‘PlagioCentre’를 개설하고, 경쟁 입찰을 거쳐 재팬 메디컬 컴퍼니(Japan Medical Company)사의 헬멧 ‘Qurum Fit’을 채택했습니다.
유럽에서는 확립된 소아 의료 시스템에 더해, 두개골 교정 기기에 대한 임상적 근거 및 기록 관리 요건을 강화하는 EU MDR(의료기기 규정)의 문서화 체계가 마련되어 있습니다. 독일, 영국, 프랑스는 해당 지역 최대 국내 시장이며, 명확한 의료 필요성 기준에 기반한 보험 급여 제도의 지원을 받고 있습니다. 이러한 상황은 강력한 문서화 역량을 갖춘 공급자에게 유리하게 작용하며, 저비용 수입품이 가격만으로 경쟁하는 것을 더욱 어렵게 만들고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류·공급망 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 제품 유형별
- 용도별
- 소재별
- 환자 연령별
- 최종사용자별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽 국가
- 아시아태평양
- 중국
- 인도
- 일본
- 호주
- 한국
- 기타 아시아태평양 국가
- 중동 및 아프리카
- GCC
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 시장 점유율 분석
- 기업 개요
- Boston Orthotics & Prosthetics
- Cranial Center of Utah
- Cranial Kids
- Cranial Remolding Orthosis, LLC
- Cranial Technologies, Inc.
- Danmar Products, Inc.
- Hanger, Inc.
- Invent Medical Group
- Ktwo Healthcare Pvt. Ltd.
- Level 4 Prosthetics and Orthotics
- Orthomerica Products, Inc.
- Orthotic & Prosthetic Lab, Inc.
- Orthotic Care Services, LLP
- Ottobock SE & Co. KGaA
- SHINING 3D
- SPS Co.
- STAR Cranial Center
- Stryker Corporation
- Surestep, LLC
- Yakima Orthotics & Prosthetics
제7장 시장 기회와 향후 전망
KSA 26.10.23According to Mordor Intelligence, the cranial orthoses market size is projected to expand from USD 0.38 billion in 2025 and USD 0.42 billion in 2026 to USD 0.66 billion by 2031, registering a CAGR of 9.53% between 2026 to 2031.
Global Cranial Orthoses Market Trends and Insights
Rising Diagnosis of Positional Plagiocephaly
Rising diagnoses of plagiocephaly and brachycephaly remain a key driver of the cranial orthoses market, as diagnosis initiates clinical monitoring, referral, fitting, and follow-up. A 2024 population-based study reported incidence rates of 5.8% in term infants and 11.8% in preterm infants, highlighting preterm birth as a significant risk factor. A 2026 study of 2,165 preterm infants in Beijing found postural cranial abnormalities in 81.2% of infants aged 0-2 months, the highest rate among the reviewed age groups. These findings emphasize the need for early head-shape monitoring, conservative repositioning, clinical observation, and timely referral during the preferred 3-8-month treatment window. Effective screening, parent education, clinician awareness, and referral pathways can reduce treatment delays and support market demand.
Growing Pediatric Referral and Early-Intervention Rates
Organized referral pathways are improving treatment access after diagnosis, particularly when assessment and fitting are integrated within the same clinical system. Shriners Children's New England launched a cranial remolding program in May 2025 that integrated 3D scanning into its orthotics workflow and enabled families to complete scanning and fitting in a single visit. This model reduces handoffs among pediatricians, specialists, orthotists, families, and payers, which can otherwise delay care. Hospital-based services also simplify referrals by providing orthotists and pediatric specialists within the same setting. Greater awareness of early treatment windows supports timely intervention and demand in the cranial orthoses market.
Clinical Debate Over Incremental Benefit in Moderate Cases
Clinical disagreement over moderate plagiocephaly treatment can delay referrals in the cranial orthoses market, particularly when clinicians and payers prioritize conservative management. A systematic review covering January 2015 to January 2025 reported monthly correction rates of 0.66 for helmet-treated infants and 0.64 for conservatively managed infants. While 25% of helmet-treated cases reached severity level 1, compared with 11% of conservatively managed cases, the difference was not statistically significant across the available trial pool. Concerns regarding skin irritation, infant compliance, and caregiver burden further reduce treatment conversion among diagnosed moderate cases, limiting the market's addressable volume.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of 3D Scanning and Digital Customization
- Improving Reimbursement and Prior-Authorization Pathways
- Inconsistent Payer Coverage and Documentation Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Active helmets held 56.45% of the cranial orthoses market share in 2025, supported by established clearance histories, long-term clinical use, and proprietary digital scanning systems embedded in treatment networks. Cranial Technologies' DOC Band uses Digital Surface Imaging to capture a complete 3D head model in less than 1 second and guide growth-room placement within its modified polyethylene foam interior. This workflow supports consistent fitting and follow-up while maintaining the active correction approach. A 10-year review of 27,990 treated infants reported a mean cranial vault asymmetry index reduction of 3.42 percentage points, with 87.6% of patients improving by at least one severity category.
Passive helmets are forecast to grow at a CAGR of 12.87% through 2031 as providers in cost-sensitive and emerging settings adopt thermoplastic designs requiring lower scanning investment and simpler production infrastructure. Active and passive designs address different clinical workflows and provider investment levels. Custom-molded orthoses retain a specialized role after craniosynostosis surgery, where individualized geometry is required. Pre-fabricated protective variants serve areas with limited therapeutic cranial remolding services, enabling the market to address both advanced digital clinics and resource-constrained settings.
Plagiocephaly accounted for 54.34% of the cranial orthoses market size in 2025, reflecting its position as the most common treatment indication and sustained diagnostic prevalence after the Back to Sleep campaign. Screening at 2-month and 4-month well-child visits directs a significant share of diagnosed infants into plagiocephaly-specific treatment pathways before age reduces correction potential. Although referral timing and quality vary across healthcare systems, early identification supports predictable patient volumes. Plagiocephaly therefore remains the primary application supporting the cranial orthoses market.
Brachycephaly is forecast to grow at a CAGR of 11.56% through 2031, driven by increased recognition during routine assessments. The 2026 Beijing study found that brachycephaly detection increased from 9.0% in the 3-4 months cohort to 19.8% in the 5-6 months cohort. Scaphocephaly requires specialized postsurgical fitting after premature sagittal suture fusion, and 2025 Hanger Institute research provided standardized craniometric indices for patient assessment. Postsurgical cranial deformity remains lower in volume but higher in value because helmet use is integrated into the surgical care episode and generally receives coverage.
Complete Report Scope:
- By Product Type
- Active Helmets
- Passive Helmets
- Custom-Molded Orthoses
- Other Product Types
- By Application
- Plagiocephaly
- Brachycephaly
- Scaphocephaly
- Postsurgical Cranial Deformity
- By Material
- Thermoplastic Outer Shells
- Polyethylene Foam Interfaces
- Polyurethane Foam Interfaces
- Copolymer Materials
- Silicone and Soft-Interface Materials
- By Patient Age
- Below 3 Months
- 3-6 Months
- Above 7-12 Months
- Above 13-18 Months
- Above 18 Months
- By End User
- Hospitals
- Pediatric and Craniofacial Centers
- Orthotic and Prosthetic Clinics
- Neurosurgery and Craniofacial Surgery Clinics
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 39.56% of revenue in 2025, supported by a mature pediatric care system, a broad orthotist base, and hospital-embedded 3D scanning services. The United States drove regional demand through established specialist networks and gradually expanding reimbursement access. Texas enacted HB 426 in June 2025, requiring Medicaid and CHIP coverage for cranial remolding orthoses for infants with plagiocephaly from September 2025, while North Carolina Medicaid revised Clinical Coverage Policy 5B in September 2024. More than 40% of US counties lacked access to an American Cleft Palate and Craniofacial Association-approved team within 100 miles, supporting demand for mobile scanning and remote follow-up services. Canada provides coverage in most provinces, while Mexico remains a smaller market due to lower healthcare spending and limited specialist infrastructure.
Asia-Pacific is forecast to grow at a CAGR of 12.98% through 2031, more than 3 percentage points above the global rate, driven by clinical demand and expanding institutional capacity. A Japanese study found positional plagiocephaly in 57.4% of infants aged 2-23 months, while a 2026 Beijing study of 2,165 preterm infants found postural cranial abnormalities in 81.2% of infants aged 0-2 months. KKH Singapore launched the region's first dedicated PlagioCentre in June 2025 and selected Japan Medical Company's Qurum Fit helmet through a competitive process.
Europe benefits from established pediatric healthcare systems and an EU MDR documentation framework that increases clinical evidence and recordkeeping requirements for cranial remolding devices. Germany, the United Kingdom, and France are the region's largest national markets, supported by reimbursement systems with defined medical-necessity criteria. These conditions favor providers with strong documentation capabilities and make it more difficult for low-cost imports to compete solely on price.
- Boston Orthotics & Prosthetics
- Cranial Center of Utah
- Cranial Kids
- Cranial Remolding Orthosis, LLC
- Cranial Technologies, Inc.
- Danmar Products, Inc.
- Hanger, Inc.
- Invent Medical Group
- Ktwo Healthcare Pvt. Ltd.
- Level 4 Prosthetics and Orthotics
- Orthomerica Products, Inc.
- Orthotic & Prosthetic Lab, Inc.
- Orthotic Care Services, LLP
- Ottobock
- SHINING 3D
- SPS Co.
- STAR Cranial Center
- Stryker
- Surestep, LLC
- Yakima Orthotics & Prosthetics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Diagnosis of Positional Plagiocephaly
- 4.2.2 Growing Pediatric Referral and Early-Intervention Rates
- 4.2.3 Expansion of 3D Scanning and Digital Customization
- 4.2.4 Improving Reimbursement and Prior-Authorization Pathways
- 4.2.5 Greater Use of Mobile Scanning and Distributed Fabrication
- 4.2.6 Increasing Parent and Clinician Awareness of Early Treatment Windows
- 4.3 Market Restraints
- 4.3.1 Clinical Debate Over Incremental Benefit in Moderate Cases
- 4.3.2 Inconsistent Payer Coverage and Documentation Requirements
- 4.3.3 Limited Availability of Pediatric Orthotists Outside Major Centers
- 4.3.4 Infant Compliance, Skin Irritation, and Caregiver Burden
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers Analysis
- 4.7.2 Bargaining Power of Buyers Analysis
- 4.7.3 Threat of New Entrants Analysis
- 4.7.4 Threat of Substitutes Analysis
- 4.7.5 Competitive Rivalry Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Product Type
- 5.1.1 Active Helmets
- 5.1.2 Passive Helmets
- 5.1.3 Custom-Molded Orthoses
- 5.1.4 Other Product Types
- 5.2 By Application
- 5.2.1 Plagiocephaly
- 5.2.2 Brachycephaly
- 5.2.3 Scaphocephaly
- 5.2.4 Postsurgical Cranial Deformity
- 5.3 By Material
- 5.3.1 Thermoplastic Outer Shells
- 5.3.2 Polyethylene Foam Interfaces
- 5.3.3 Polyurethane Foam Interfaces
- 5.3.4 Copolymer Materials
- 5.3.5 Silicone and Soft-Interface Materials
- 5.4 By Patient Age
- 5.4.1 Below 3 Months
- 5.4.2 3-6 Months
- 5.4.3 Above 7-12 Months
- 5.4.4 Above 13-18 Months
- 5.4.5 Above 18 Months
- 5.5 By End User
- 5.5.1 Hospitals
- 5.5.2 Pediatric and Craniofacial Centers
- 5.5.3 Orthotic and Prosthetic Clinics
- 5.5.4 Neurosurgery and Craniofacial Surgery Clinics
- 5.5.5 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Boston Orthotics & Prosthetics
- 6.3.2 Cranial Center of Utah
- 6.3.3 Cranial Kids
- 6.3.4 Cranial Remolding Orthosis, LLC
- 6.3.5 Cranial Technologies, Inc.
- 6.3.6 Danmar Products, Inc.
- 6.3.7 Hanger, Inc.
- 6.3.8 Invent Medical Group
- 6.3.9 Ktwo Healthcare Pvt. Ltd.
- 6.3.10 Level 4 Prosthetics and Orthotics
- 6.3.11 Orthomerica Products, Inc.
- 6.3.12 Orthotic & Prosthetic Lab, Inc.
- 6.3.13 Orthotic Care Services, LLP
- 6.3.14 Ottobock SE & Co. KGaA
- 6.3.15 SHINING 3D
- 6.3.16 SPS Co.
- 6.3.17 STAR Cranial Center
- 6.3.18 Stryker Corporation
- 6.3.19 Surestep, LLC
- 6.3.20 Yakima Orthotics & Prosthetics
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


