

|
시장보고서
상품코드
2154850
무릎 부종 치료 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Swollen Knee Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
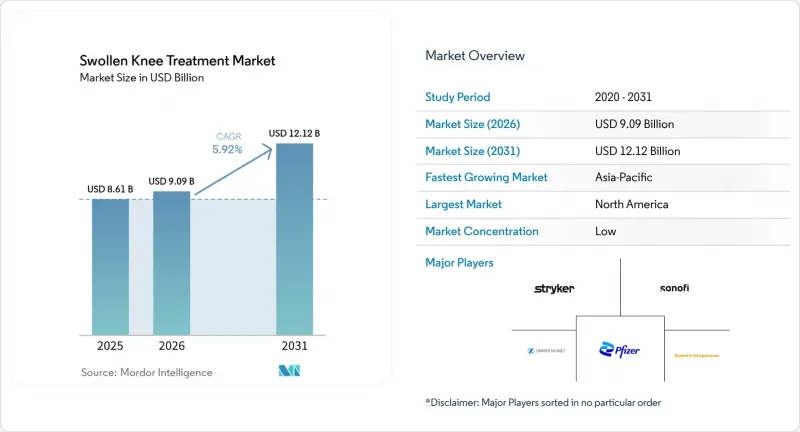
에 따르면 무릎 부종 치료 시장 규모는 2025년에 86억 1,000만 달러, 2026년에 90억 9,000만 달러에 달하며, 2031년까지 121억 2,000만 달러에 달할 것으로 예측되고 있으며, 2026-2031년에 CAGR 5.92%로 성장할 것으로 전망되고 있습니다.
전 세계 무릎 부종 치료 시장의 동향 및 인사이트
노화에 따른 퇴행성 무릎 관절염의 증가
2025년 기준으로 65세 이상 미국 성인의 33.6%가 무릎 관절염을 앓고 있으며, 같은 연령대의 여성에서는 그 비율이 42.1%에 달했습니다. 증상을 보이는 비율은 45세 때 7%에서 60세 때 12%로 상승하고 있으며, 이로 인해 수요는 최고령 환자층을 넘어 확대되고 있습니다. SDI(사회개발지수)가 높은 국가에서는 연령 조정 유병률이 10만 명당 4,656.7명이었으나, SDI가 중간 수준인 국가에서는 진단 및 치료의 여지가 훨씬 더 크다고 할 수 있습니다. 발병률은 50세에서 64세 사이에 정점에 달하며, 더 많은 생산 연령층의 환자들이 무릎 부종 치료 시장으로 유입되고 있습니다. 이 환자층은 이동성을 유지하고 휴직 기간을 단축할 수 있는 치료법을 선호합니다. 또한 말기 단계의 치료를 지연시킬 수 있는 치료법이나 회복 프로토콜에 대한 수요도 시장을 촉진하고 있습니다.
비만과 관련된 무릎 질환의 증가
비만 및 고지혈증은 퇴행성 무릎 관절염 환자에서 더 심각한 활막염 및 인공 무릎 관절 전치환술 후 기능적 예후의 악화와 관련이 있었습니다. 또한 비만도가 높을수록 의료 서비스 이용 및 퇴행성 무릎 관절염 치료제 소비량도 증가하는 경향이 나타났습니다. 일라이 릴리(Eli Lilly)사는 비만 및 퇴행성 무릎 관절염 환자를 대상으로 한 연구에서 레타톨티드가 WOMAC 통증 점수를 최대 75.8% 감소시켰으며, 68주 시점에 평균 28.7%의 체중 감소를 가져왔다고 보고했습니다. 이 결과에 따라 두 질환을 동반한 환자 집단에서 체중 관리가 정형외과적 치료와 더불어 중요한 위치를 차지하게 되었습니다. 보다 적절한 체중 관리를 통해 외과적 치료가 필요해지기 전에 관절 기능 개선을 도모할 수 있습니다. 이러한 연관성은 무릎 부종을 동반하는 질환의 치료 시장이 목표로 하는 치료 경로를 확대하는 것입니다.
장기 진통제의 안전성 위험 및 사용 제한
NSAID의 장기 사용에는 심혈관계, 소화기계, 신장계의 위험이 수반되므로, 임상 지침에서는 최단 기간 중 최소 유효 용량을 투여할 것을 권장하고 있습니다. 홍콩 정형외과학회는 퇴행성 무릎 관절염의 1차 치료법으로 외용 NSAID를, 2차 치료법으로 경구약을 권장하고 있습니다. 2025년 5월에 발표된 독일 DGOU 가이드라인도 NSAID의 투여 제한을 강조하며, 글루코사민을 권장 리스트에서 제외했습니다. 메타분석에 따르면 트라마돌을 제외한 오피오이드 제제의 유효성은 제한적이었으며, 투여 중단률은 22%였던 반면, 대조군에서는 15%였습니다. 이러한 제한으로 인해 브랜드 경구 진통제 및 오피오이드 함유 제품은 어려운 상황에 처해 있습니다. 그 결과, 무릎 부종 치료 시장에서 제약 기업의 성장이 억제되고 있습니다.
부문 분석
2025년, 의약품은 NSAID, 코르티코스테로이드, 히알루론산 점탄성 보충제에 힘입어 무릎 부종 치료 시장에서 44.28%의 점유율을 차지했습니다. 이러한 제품들은 무릎 부종에 대한 일반적인 1차 및 2차 치료법으로 계속해서 사용되고 있습니다. 의약품 분야에서는 1회 주사 요법에서 가교형 및 초고분자량 히알루론산 제품으로의 가치 전환이 진행되고 있습니다. 이러한 제품들이 수술 시기를 늦출 수 있다는 증거는 외과적 개입 전 사용을 지원하고 있습니다. 퇴행성 무릎 관절염의 병태 수정제 부문에서는 그동안 임상 시험에서 실패가 반복되어 왔습니다. 바이오스플라이스(BioSplice)사는 2026년 1월, 로레시비빈트의 신약허가신청서(NDA)를 FDA에 제출했습니다. 이 신청은 이 분야에서 약 28년 만에 이루어진 큰 진전이 될 가능성이 있습니다. 또한 무릎 부종 치료 업계에서 약물 치료의 위상을 바꿀 가능성도 있습니다.
보조기 시장은 2031년까지 연평균 성장률(CAGR) 7.80%로 성장할 것으로 예측되며, 가장 빠르게 성장하는 치료 분야가 될 전망입니다. 이러한 성장을 주도하고 있는 것은 스마트 기능과 센서를 탑재한 서포터입니다. 또한 웨어러블 기기를 활용한 원격 재활은 기존의 물리치료보다 뛰어난 신경근 적응 효과를 가져왔습니다. 퇴행성 관절염의 경우, 하중 경감용 보조기나 기능성 보조기가 여전히 널리 사용되고 있습니다. 또한 인공 무릎 관절 전치환술이 외래 진료로 전환됨에 따라 수술 후용 및 재활용 보조기 시장도 확대되고 있습니다. 외과적 치료는 인공관절 치환술이나 관절경 수술을 통해 그 규모를 유지하고 있습니다. 로봇 수술의 도입은 의료기기에 대한 투자를 증가시키고, 임플란트의 표준화를 촉진할 가능성이 있습니다. 이러한 요인들이 복합적으로 작용하여, 무릎 부종을 동반하는 질환의 치료 시장에서 보조기구의 역할은 더욱 중요해지고 있습니다.
2025년, 퇴행성 관절염은 적응증별 매출의 44.03%를 차지했습니다. 이 질환의 전 세계 환자 수는 3억 7,470만 명으로, 예측 기간 내내 그 위치를 유지했습니다. 미국에서 환자 1인당 연간 직접 비용은 3,719달러에서 4,518달러 사이였습니다. 이 적응증 분야에서는 의약품, 치료법, 보조기 및 외과적 치료가 사용되고 있습니다. 일본과 독일에서는 관절 보존술의 보험 적용 범위가 확대되어, 인공관절 전치환술에 이르기까지의 치료 기간을 연장할 수 있습니다. 류마티스 관절염은 두 번째로 큰 적응증이었습니다. 이는 코르티코스테로이드 및 생물제제의 처방에 의해 지원되고 있습니다. 또한 미국과 유럽의 확립된 보험 환급 체계의 혜택도 받고 있습니다. 이러한 추세로 인해 퇴행성 무릎 관절염은 무릎 부종 치료 시장에서 계속해서 중심적인 위치를 차지하고 있습니다.
스포츠나 외상으로 인한 손상은 2031년까지 연평균 성장률(CAGR) 7.82%로 성장할 것으로 예측됩니다. 조직적인 스포츠 참여와 급성 무릎 관절액 저류 관리에 대한 의식의 향상가 이러한 성장률을 지원하고 있습니다. 천자, 관절 천자, 물리 치료, 그리고 반월판 및 인대 재건술은 이러한 수요의 혜택을 받고 있습니다. 스마트 서포트는 활동적인 환자의 회복 상황을 모니터링할 수도 있습니다. FDA는 2024년 8월, 최대 4cm²의 연골 결손이 있는 성인을 대상으로 관절경 하 투여용으로 MACI Arthro를 승인했습니다. 이러한 적응증 확대로 인해 연간 2만 명의 추가 환자가 대상이 되었으며, Vericel사의 목표 외과 의사 수는 5,000명에서 7,000명으로 증가했습니다. 통풍, 결정성 관절증, 활액낭염, 힘줄 장애, 감염증, 화농성 관절염은 규모는 작지만 명확한 수요원으로 남아 있습니다. 이러한 질환에는 주로 천자, 코르티코스테로이드 주사 또는 항균제 치료가 필요합니다. 이러한 다양성으로 인해 무릎 부종을 치료하는 업계의 활동 범위가 확대되고 있습니다.
지역별 분석
2025년, 북미는 무릎 부종 치료 시장 점유율의 41.85%를 차지했습니다. 수술 및 주사에 대한 확립된 보험 환급 제도, 높은 시술 빈도, 그리고 고령화가 진행되는 인구 구성이 이 지역의 시장을 지원하고 있습니다. 미국에서 65세 이상 성인의 무릎 퇴행성 관절염 유병률은 33.6%에 달했습니다. 외래 수술 센터로의 전환으로 인해 병원에서의 선택적 수술 건수는 감소하는 반면, 외래 센터 및 클리닉의 기여도는 높아지고 있습니다.
2025년, 유럽은 지역별 시장 규모에서 2위를 차지했습니다. 이 지역에서는 독일, 영국, 프랑스가 무릎 퇴행성 관절염 환자 수의 절대 수에서 가장 많은 비중을 차지했습니다. 독일 정형외과학회(DGOU)는 2025년 5월, 근거 기반 무릎 퇴행성 관절염 지침을 발표하며, 권장 항목에서 글루코사민 및 전기 요법을 삭제했습니다. 이 방침에 따라 치료는 운동 요법을 주축으로 하며, 필요에 따라 약물 요법이나 외과적 치료가 선택되도록 유도되고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 7.88%로 성장할 것으로 예측되며, 이는 각 지역 중 가장 높은 성장률입니다. 일본과 한국에서는 정책 및 제품의 변화에 힘입어 연령 조정 무릎 퇴행성 관절염 유병률이 높아지고 있습니다. 일본에서는 2024년, 대퇴골 원위부 절골술 및 관절경 하 반월판 고정술이 국민건강보험 적용 대상에 추가되었습니다. 한국에서는 GC 웰빙의 ‘Healroad Once Inj.’가 2024년에 승인되면서, 1회 주사형 히알루론산 치료제 시장의 경쟁이 격화되었습니다. 중국에서는 의료 인프라 확충에 힘입어 무릎 부종 치료 시장의 절대적 규모 확대를 주도하고 있습니다. 인도와 호주, 그리고 규모는 작지만 중동 및 아프리카 및 남미 시장에서도 투자, 제조 인센티브, 보험 환급, 그리고 인구 고령화로 인해 무릎 부종 치료 시장의 기회가 확대되고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 공급망 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 치료별
- 적응증별
- 투여 경로별
- 최종사용자별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽 국가
- 아시아태평양
- 중국
- 일본
- 인도
- 호주
- 한국
- 기타 아시아태평양 국가
- 중동 및 아프리카
- GCC
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 시장 점유율 분석
- 기업 개요
- Anika Therapeutics, Inc.
- Arthrex, Inc.
- Bauerfeind AG
- Bayer AG
- Bioventus Inc.
- Breg, Inc.
- Eli Lilly and Company
- Enovis Corporation
- Exactech, Inc.
- Ferring Pharmaceuticals
- Fidia Farmaceutici S.p.A.
- Genascence Corporation
- Johnson & Johnson MedTech
- Kolon TissueGene, Inc.
- LG Chem Ltd.
- Medtronic plc
- Merck & Co., Inc.
- Novartis AG
- OrthogenRx, Inc.
- Ossur hf.
- Pacira BioSciences, Inc.
- Pfizer Inc.
- Sanofi S.A.
- SEIKAGAKU CORPORATION
- Smith & Nephew plc
- Stryker Corporation
- Teva Pharmaceutical Industries Ltd.
- Vericel Corporation
- Zimmer Biomet Holdings, Inc.
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the swollen knee treatment market size is projected to be USD 8.61 billion in 2025, USD 9.09 billion in 2026, and reach USD 12.12 billion by 2031, growing at a CAGR of 5.92% from 2026 to 2031.
Global Swollen Knee Treatment Market Trends and Insights
Aging-Related Growth in Knee Osteoarthritis
Knee osteoarthritis affected 33.6% of U.S. adults aged 65 years and older in 2025, and the rate reached 42.1% among women in this age group. Symptomatic rates rose from 7% at age 45 to 12% at age 60, which extends demand beyond the oldest patient groups. High-SDI countries carried an age-standardized prevalence of 4,656.7 per 100,000 people, but middle-SDI countries have greater room for diagnosis and care. Incidence peaked at ages 50 to 64, bringing more working-age patients into the swollen knee treatment market. This patient group favors treatment in the swollen knee treatment market that can preserve mobility and reduce time away from work. It also supports demand for therapies and recovery protocols that can delay late-stage care.
Rising Obesity-Associated Knee Disease
Obesity and hyperlipidemia were associated with more severe synovitis and poorer functional outcomes after total knee arthroplasty in patients with knee osteoarthritis. Higher obesity classes were also associated with greater health care use and knee osteoarthritis medication consumption. Eli Lilly reported that retatrutide reduced WOMAC pain scores by up to 75.8% and produced average weight loss of 28.7% at 68 weeks in people with obesity and knee osteoarthritis. The results place weight management alongside orthopedic treatment for an overlapping patient population. Better weight control can improve joint mechanics before surgical care is needed. This link broadens the treatment pathway addressed by the swollen knee treatment market.
Safety Risks and Restricted Use of Long-Term Analgesics
Chronic NSAID use carries cardiovascular, gastrointestinal, and renal risks, leading clinical guidance to favor the lowest effective dose for the shortest period. The Hong Kong College of Orthopedic Surgeons recommends topical NSAIDs as first-line management for knee osteoarthritis and oral products as second-line treatment. Germany's DGOU guideline in May 2025 also emphasized limited NSAID dosing and removed glucosamine from its recommendations. Meta-analyses reported limited benefit for non-tramadol opioids and discontinuation rates of 22%, compared with 15% for controls. These restrictions place pressure on branded oral analgesics and opioid-containing products. The result limits pharmaceutical growth in the swollen knee treatment market.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Minimally Invasive and Outpatient Care
- Longer-Acting and Single-Injection Therapies
- Reimbursement Uncertainty for Viscosupplementation and Biologics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Pharmaceuticals held 44.28% of the swollen knee treatment market share in 2025, supported by NSAIDs, corticosteroids, and hyaluronic acid viscosupplements. These products remained common first- and second-line options for knee swelling. Within pharmaceuticals, single-injection regimens are shifting value toward cross-linked and ultra-high-molecular-weight hyaluronic acid products. Evidence that these products may delay surgery supports their use before surgical intervention. The disease-modifying osteoarthritis drug category had seen repeated clinical failures. Biosplice submitted its lorecivivint NDA to the FDA in January 2026. The submission could mark the first major advance in this category in nearly 28 years. It could also change how pharmaceutical treatment is positioned in the swollen knee treatment industry.
Accessories are projected to grow at a 7.80% CAGR through 2031, making them the fastest-growing treatment category. Smart and sensor-enabled supports lead to this expansion. Wearable-based telerehabilitation also produced greater neuromuscular adaptation than conventional physiotherapy. Unloader and functional braces retain substantial use in osteoarthritis. Post-operative and rehabilitative braces are also expanding as total knee arthroplasty moves to ambulatory settings. Surgical treatment retains volume through replacement and arthroscopy. Robotic approaches can increase capital-equipment spending and support implant standardization. This mix gives accessories a larger role in the swollen knee treatment market.
Osteoarthritis accounted for 44.03% of indication revenues in 2025. The condition had a global patient population of 374.7 million, sustaining its position throughout the forecast period. The United States direct annual costs per patient ranged from USD 3,719 to USD 4,518. The indication uses pharmaceuticals, therapy, accessories, and surgical treatment. Broader coverage of joint-preserving procedures in Japan and Germany can extend intervention before total replacement. Rheumatoid arthritis was the second-largest indication. It is supported by corticosteroid and biologic prescribing. It also benefits from established reimbursement pathways in the United States and Europe. These patterns keep osteoarthritis at the center of the swollen knee treatment market.
Sports and traumatic injuries are forecast to grow at a 7.82% CAGR through 2031. Organized sports participation and greater awareness of acute knee effusion management support this rate. Aspiration, arthrocentesis, physical therapy, and meniscal or ligament reconstruction benefit from this demand. Smart support can also monitor recovery for active patients. The FDA approved MACI Arthro in August 2024 for arthroscopic delivery in adults with cartilage defects up to 4 cm2. The expanded label addressed 20,000 additional patients annually and increased Vericel's target surgeon base from 5,000 to 7,000. Gout, crystal arthropathies, bursitis, tendinopathy, infection, and septic arthritis remained smaller but distinct sources of demand. They mainly require aspiration, corticosteroid injections, or antimicrobial pharmaceutical care. This diversity broadens activity in the swollen knee treatment industry.
Complete Report Scope:
- By Treatment
- Pharmaceuticals
- Non-Steroidal Anti-Inflammatory Drugs
- Non-NSAID Analgesics
- Corticosteroids
- Hyaluronic Acid and Viscosupplementation
- Disease-Modifying Osteoarthritis Drugs
- Opioid Analgesics
- Other Pharmaceuticals
- Therapy
- Physical Therapy and Rehabilitation
- Intra-Articular Injection Therapy
- Bone Marrow Aspirate Concentrate Therapy
- Adipose-Derived and Cell-Based Therapies
- Aspiration and Arthrocentesis
- Nerve Blocks and Patient-Controlled Analgesia Pumps
- Accessories
- Assistive Devices and Bracing
- Compression Sleeves and Wraps
- Unloader and Functional Braces
- Post-Operative and Rehabilitative Braces
- Smart and Sensor-Enabled Supports
- Other Accessories
- Surgical Treatment
- Arthroscopy
- Meniscal and Ligament Reconstruction
- Cartilage Repair and Resurfacing
- Osteotomy
- Partial Knee Replacement
- Total Knee Replacement
- Other Surgical Treatments
- Pharmaceuticals
- By Indication
- Osteoarthritis
- Rheumatoid Arthritis
- Sports and Traumatic Injuries
- Gout and Crystal Arthropathies
- Bursitis and Tendinopathy
- Infection and Septic Arthritis
- Other Indications
- By Route of Administration
- Oral
- Intravenous and Intramuscular
- Procedural and Surgical
- Other Route of Administrations
- By End User
- Hospitals
- Orthopedic Clinics
- Rheumatology Clinics
- Ambulatory Surgical Centers
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 41.85% of the swollen knee treatment market share in 2025. High procedural intensity, established reimbursement for surgery and injections, and an aging population support the region. The United States's knee osteoarthritis prevalence reached 33.6% among adults aged 65 years and older. The shift toward ambulatory surgical centers lowers hospital elective volume while raising contributions from ambulatory centers and clinics.
Europe was the second-largest regional market in 2025. Germany, the United Kingdom, and France carried the highest absolute osteoarthritis patient volumes in the region. DGOU issued an evidence-based gonarthrosis guideline in May 2025 that removed glucosamine and electrotherapy from recommendations. The policy directs care toward exercise-based treatment, followed by pharmacological or surgical options where needed.
Asia-Pacific is projected to grow at a 7.88% CAGR through 2031, the fastest rate among regions. Japan and South Korea have high age-standardized knee osteoarthritis prevalence, supported by policy and product changes. Japan added femoral distal osteotomy and arthroscopic meniscal stabilization to national insurance coverage in 2024. South Korea saw GC Wellbeing's 2024 approval for Healroad Once Inj., adding competition in single-injection hyaluronic acid treatment. China drives absolute volume growth in the swollen knee treatment market through health care infrastructure development. India and Australia, along with the smaller Middle East and Africa and South American markets, extend the swollen knee treatment market opportunity through investment, manufacturing incentives, reimbursement, and population aging.
- Anika Therapeutics
- Arthrex
- Bauerfeind
- Bayer
- Bioventus Inc.
- Breg
- Eli Lilly and Company
- Enovis Corporation
- Exactech
- Ferring Pharmaceuticals
- Fidia Farmaceutici
- Genascence Corporation
- Johnson & Johnson MedTech
- Kolon TissueGene, Inc.
- LG Chem
- Medtronic
- Merck
- Novartis
- OrthogenRx, Inc.
- Ossur hf.
- Pacira BioSciences
- Pfizer
- Sanofi
- Seikagaku
- Smiths Group
- Stryker
- Teva Pharmaceutical Industries
- Vericel
- Zimmer Biomet
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging-Related Growth in Knee Osteoarthritis
- 4.2.2 Rising Obesity-Associated Knee Disease
- 4.2.3 Expansion of Minimally Invasive and Outpatient Care
- 4.2.4 Longer-Acting and Single-Injection Therapies
- 4.2.5 Sensor-Enabled Bracing and Digitized Rehabilitation
- 4.2.6 Earlier Intervention Driven by Obesity and Musculoskeletal Care Integration
- 4.3 Market Restraints
- 4.3.1 Safety Risks and Restricted Use of Long-Term Analgesics
- 4.3.2 Reimbursement Uncertainty for Viscosupplementation and Biologics
- 4.3.3 Difficulty Demonstrating Disease Modification in Heterogeneous Knee Disease
- 4.3.4 Fragmented Clinical Protocols for PRP, Stem-Cell and Regenerative Therapies
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Treatment
- 5.1.1 Pharmaceuticals
- 5.1.1.1 Non-Steroidal Anti-Inflammatory Drugs
- 5.1.1.2 Non-NSAID Analgesics
- 5.1.1.3 Corticosteroids
- 5.1.1.4 Hyaluronic Acid and Viscosupplementation
- 5.1.1.5 Disease-Modifying Osteoarthritis Drugs
- 5.1.1.6 Opioid Analgesics
- 5.1.1.7 Other Pharmaceuticals
- 5.1.2 Therapy
- 5.1.2.1 Physical Therapy and Rehabilitation
- 5.1.2.2 Intra-Articular Injection Therapy
- 5.1.2.3 Bone Marrow Aspirate Concentrate Therapy
- 5.1.2.4 Adipose-Derived and Cell-Based Therapies
- 5.1.2.5 Aspiration and Arthrocentesis
- 5.1.2.6 Nerve Blocks and Patient-Controlled Analgesia Pumps
- 5.1.3 Accessories
- 5.1.3.1 Assistive Devices and Bracing
- 5.1.3.2 Compression Sleeves and Wraps
- 5.1.3.3 Unloader and Functional Braces
- 5.1.3.4 Post-Operative and Rehabilitative Braces
- 5.1.3.5 Smart and Sensor-Enabled Supports
- 5.1.3.6 Other Accessories
- 5.1.4 Surgical Treatment
- 5.1.4.1 Arthroscopy
- 5.1.4.2 Meniscal and Ligament Reconstruction
- 5.1.4.3 Cartilage Repair and Resurfacing
- 5.1.4.4 Osteotomy
- 5.1.4.5 Partial Knee Replacement
- 5.1.4.6 Total Knee Replacement
- 5.1.4.7 Other Surgical Treatments
- 5.1.1 Pharmaceuticals
- 5.2 By Indication
- 5.2.1 Osteoarthritis
- 5.2.2 Rheumatoid Arthritis
- 5.2.3 Sports and Traumatic Injuries
- 5.2.4 Gout and Crystal Arthropathies
- 5.2.5 Bursitis and Tendinopathy
- 5.2.6 Infection and Septic Arthritis
- 5.2.7 Other Indications
- 5.3 By Route of Administration
- 5.3.1 Oral
- 5.3.2 Intravenous and Intramuscular
- 5.3.3 Procedural and Surgical
- 5.3.4 Other Route of Administrations
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Orthopedic Clinics
- 5.4.3 Rheumatology Clinics
- 5.4.4 Ambulatory Surgical Centers
- 5.4.5 Other End Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.3.1 Anika Therapeutics, Inc.
- 6.3.2 Arthrex, Inc.
- 6.3.3 Bauerfeind AG
- 6.3.4 Bayer AG
- 6.3.5 Bioventus Inc.
- 6.3.6 Breg, Inc.
- 6.3.7 Eli Lilly and Company
- 6.3.8 Enovis Corporation
- 6.3.9 Exactech, Inc.
- 6.3.10 Ferring Pharmaceuticals
- 6.3.11 Fidia Farmaceutici S.p.A.
- 6.3.12 Genascence Corporation
- 6.3.13 Johnson & Johnson MedTech
- 6.3.14 Kolon TissueGene, Inc.
- 6.3.15 LG Chem Ltd.
- 6.3.16 Medtronic plc
- 6.3.17 Merck & Co., Inc.
- 6.3.18 Novartis AG
- 6.3.19 OrthogenRx, Inc.
- 6.3.20 Ossur hf.
- 6.3.21 Pacira BioSciences, Inc.
- 6.3.22 Pfizer Inc.
- 6.3.23 Sanofi S.A.
- 6.3.24 SEIKAGAKU CORPORATION
- 6.3.25 Smith & Nephew plc
- 6.3.26 Stryker Corporation
- 6.3.27 Teva Pharmaceutical Industries Ltd.
- 6.3.28 Vericel Corporation
- 6.3.29 Zimmer Biomet Holdings, Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-need assessment


