

|
시장보고서
상품코드
2154895
남미의 화상회의 하드웨어 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)South America Video Conferencing Hardware - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
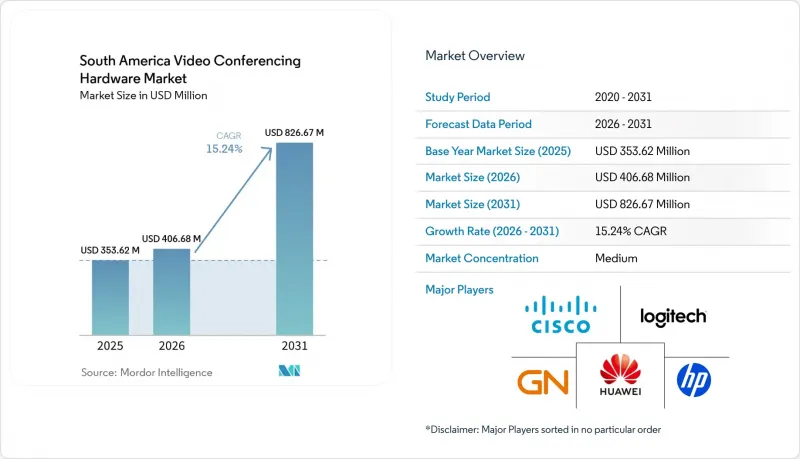
에 따르면 남미의 화상회의용 하드웨어 시장 규모는 2025년 3억 5,362만 달러에서 2026년에는 4억 668만 달러로 확대하며, 2031년까지 8억 2,667만 달러에 달할 것으로 예상되고 있으며, 2026-2031년에 CAGR 15.24%로 확대할 전망입니다.
남미 화상회의용 하드웨어 시장의 동향 및 인사이트
하이브리드 근무 및 분산형 팀의 확대
하이브리드 근무의 확산으로 인해 남미 전역에서 회의실용 하드웨어에 대한 요구 사항이 변화하고 있습니다. 기업은 사무실 근무와 원격 근무를 병행하고 있으며, 이러한 수요는 예정된 회의 시간대에 집중되고 있습니다. 이러한 추세로 인해 프로 AV 지원 없이도 이용할 수 있는 회의실에 대한 수요가 증가하고 있습니다. 이에 따라 기업은 자동 프레임 조정 기능과 여러 개의 마이크를 갖춘 클라우드 관리형 엔드포인트를 표준화하고 있습니다. 기업이 임시방편으로 사용하던 노트북 기반 설정에서 인증된 회의실용 시스템으로 전환함에 따라 남미의 화상회의 하드웨어 시장이 혜택을 보고 있습니다. 또한 페루에서 새롭게 의무화된 재택근무 정책은 분산형 팀에게 안전하고 신뢰할 수 있는 시스템의 중요성을 더욱 높이고 있습니다.
의료 및 교육 분야의 디지털 전환
의료 분야의 수요는 긴급 구매라기보다는 정기적인 원격의료 서비스 조달과 점점 더 밀접하게 연결되고 있습니다. 브라질의 SUS(국민보건시스템)는 최근 수천 개의 지자체에서 수백만 건의 원격 진료를 제공했습니다. 연방 정부는 향후 몇년에 ICU(중환자실)가 상호 연결된 스마트 병원 구축을 위해 막대한 자금을 배정했습니다. 교육 분야에서는 교육부가 ‘Politica de Inovacao Educacao Conectada’를 통해 2026년 5월까지 10만 개의 공립학교를 네트워크로 연결할 계획입니다. 의료 및 교육 분야의 구매 담당자들은 반복되는 회의나 다양한 형태의 회의실에서도 안정적으로 작동하는 장비를 필요로 합니다. 이러한 프로그램들은 남미의 화상 회의 하드웨어 시장에서 신뢰할 수 있는 카메라, 디스플레이, 회의실용 오디오 시스템에 대한 기관들의 수요를 지원하고 있습니다.
높은 하드웨어, 설치 및 유지보수 비용
고급 기업용 엔드포인트는 많은 중견 기업 및 공공 부문 구매자에게 여전히 예산 범위를 벗어납니다. 주요 공급업체가 제공하는 인증된 협업 바는 설치, 통합, 플랫폼 라이선싱에 앞서 고액의 비용이 발생합니다. 브라질의 수입세 및 공업제품세로 인해 수입된 화상 통신 장비의 총 소유 비용이 상승하고 있습니다. 이러한 비용 구조는 여러 거점에 걸쳐 인증된 회의실을 표준화할 수 있는 대기업에 유리하게 작용합니다. 반면, 소규모 조직에서는 대신 소프트웨어 클라이언트나 소비자용 주변기기를 사용하는 경우가 많습니다. 남미의 화상 회의 하드웨어 시장에서는 여전히 더 저렴한 가격의 인증된 회의실 시스템에 대한 미충족 수요가 존재하고 있습니다.
부문 분석
2025년, 협업 바(collaboration bar)는 남미 화상 회의 하드웨어 시장 규모의 34.56%를 차지했습니다. 카메라, 마이크, 스피커 및 플랫폼 인증이 하나의 장치에 통합되어 있으며, 도입이 간소화됩니다. 이는 주요 도시 이외의 지역에서 사내 AV 기술이 제한적인 경우에 유용합니다. 마이크로소프트의 인증된 디바이스 생태계는 기업 입찰 과정에서 인증된 올인원 시스템의 채택을 촉진하고 있습니다. USB 기반 통합형 바는 2031년까지 연평균 성장률(CAGR) 15.73%로 확대될 것으로 예측됩니다. 그 매력은 콜롬비아, 칠레, 아르헨티나에서 가장 두드러지는데, 이들 국가에서는 다양한 노트북이 도입되어 있으며, 간편한 BYOD 지원 회의실에 대한 수요가 증가하고 있습니다.
로지텍의 ‘Rally AI Camera Pro’는 더 높은 부가가치를 지닌 협업 바 카테고리로의 전환을 보여주는 좋은 사례입니다. 이 제품은 듀얼 카메라를 통한 AI 프레임링 기능과 임원 회의실을 위한 벽면 이식형 설치 옵션을 결합하고 있습니다. 통합형 바의 시야 범위를 초과하는 넓은 회의실에서는 PTZ 카메라가 여전히 중요한 역할을 하고 있습니다. 또한 보안 통제가 요구되는 정부 기관이나 규제 대상 도입 환경에서는 코덱 시스템의 중요성이 변함없습니다. 기업용 헤드셋, 스피커폰, 마이크 어레이는 개인의 오디오 환경과 넓은 회의실의 음향에 대응하고 있습니다. MCU는 멀티사이트 회의를 지원하며, 번들 키트는 중소기업을 위한 턴키 도입에 도움이 됩니다. 남미의 화상 회의 하드웨어 업계는 마이크로소프트 및 Zoom의 인증 프레임워크에 의존하고 있습니다. 이러한 프레임워크가 조달 후보 리스트이나 가격 책정에 영향을 미치기 때문입니다.
2025년에는 상업 시설이 최종사용자 수요의 62.27%를 차지했습니다. 상파울루, 부에노스아이레스, 보고타, 산티아고의 금융 서비스, 기술, 전문 서비스 기업은 표준화된 업무 환경 시스템 도입을 우선시하고 있습니다. 이러한 노력에서는 사무실 간 일관된 사용자 경험을 제공하는 인증 제품이 일반적으로 핵심을 이루고 있습니다. 의료 시설은 2031년까지 연평균 성장률(CAGR) 15.62%로 확대될 것으로 예측됩니다. 의료 시스템은 신뢰할 수 있는 회의실용 기기와 지원 서비스가 필요한, 재현 가능한 원격의료 워크플로로 전환되고 있습니다. 그 결과 발생하는 시설 수준의 수요는 팬데믹 기간 중의 긴급 구매보다 지속성이 더 높습니다.
브라질의 스마트 병원 프로그램은 임상용 비디오 단말기의 표준화된 조달을 지원하고 있습니다. 대학, 정부 기관 및 공공 기관은 공식 입찰 절차를 통해 이러한 솔루션을 조달하고 있습니다. 이러한 구매자들은 규정 준수 실적과 지역별 유통망을 중요하게 여깁니다. 데이터 상주 요건 또한 규제 대상 부문의 도입 결정에 영향을 미치고 있습니다. 국경을 초월한 협력을 통해 현지 규제를 준수하면서도 더 광범위한 상호 운용성을 실현하는 시스템의 가치가 높아지고 있습니다. 따라서 남미의 화상 회의 하드웨어 업계는 다양한 고객 요구 사항을 충족하기 위해 클라우드 기반, 하이브리드 및 온프레미스 아키텍처를 모두 지원해야 합니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 업계 밸류체인 분석
- 거시경제 요인이 시장에 미치는 영향
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 하드웨어 유형별
- 최종사용자별
- 용도별
- 배포 모드별
- 지역별
- 브라질
- 아르헨티나
- 콜롬비아
- 칠레
- 페루
- 기타 남미 국가
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Logitech International S.A.
- Cisco Systems, Inc.
- HP Inc.
- GN Audio A/S
- Huawei Technologies Co., Ltd.
- EPOS Group A/S
- Barco NV
- AVer Information Inc.
- Panasonic Corporation
- Dahua Technology Co., Ltd.
- Yealink Network Technology Co., Ltd.
- ClearOne, Inc.
- Crestron Electronics, Inc.
- Shure Incorporated
- Huddly AS
- Neatframe Ltd.
- Lifesize, Inc.
- Owl Labs Inc.
- DTEN Inc.
- Konftel AB
- MAXHUB, a brand of Returnstar Interactive Technology Group Co., Ltd.
- Lumens Digital Optics Inc.
- ZTE Corporation
- AudioCodes Ltd.
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the South America video conferencing hardware market size is expected to increase from USD 353.62 million in 2025 to USD 406.68 million in 2026 and reach USD 826.67 million by 2031, expanding at a CAGR of 15.24% over 2026-2031.
South America Video Conferencing Hardware Market Trends and Insights
Hybrid Work and Distributed Team Expansion
Hybrid work has changed room hardware requirements across South America. Firms are using a mix of office and remote work that concentrates demand into scheduled meeting periods. This pattern increases the need for rooms that can be used without specialist AV support. Enterprises are therefore standardizing cloud-managed endpoints with automatic framing and multiple microphones. The South America video conferencing hardware market benefits when firms replace ad hoc laptop setups with certified room deployments. New telework obligations in Peru also reinforce the importance of secure and dependable systems for distributed teams.
Digital Transformation in Healthcare and Education
Healthcare demand is increasingly tied to recurring telehealth procurement rather than emergency purchasing. Brazil's SUS delivered millions of teleconsultations across thousands of municipalities over the recent period. The federal government allocated substantial funding for smart hospitals with interconnected ICUs over the coming years. In education, the Ministry of Education connected 100,000 public schools through Politica de Inovacao Educacao Conectada by May 2026. Health and education buyers need equipment that works reliably across repeated sessions and varied room formats. These programs support institutional demand for reliable cameras, displays, and room audio systems in the South America video conferencing hardware market.
High Hardware, Installation, and Maintenance Costs
Premium enterprise endpoints remain beyond the budget of many mid-market and public-sector buyers. Certified collaboration bars from leading suppliers carry high costs before installation, integration, and platform licensing. Brazilian import and industrial product taxes raise the landed cost of imported video communication equipment. The cost structure favors large enterprises that can standardize certified rooms across multiple sites. Smaller organizations often use software clients and consumer-grade peripherals instead. The South America video conferencing hardware market still has unmet demand for more affordable complete certified room systems.
Other drivers and restraints analyzed in the detailed report include:
- Fiber, 4G, 5G, and Broadband Infrastructure Improvements
- AI-Enabled Endpoint Upgrade Cycles
- Connectivity Limitations and Power Reliability Issues
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Collaboration Bars held 34.56% of the South America video conferencing hardware market size in 2025. They simplify deployment because the camera, microphone, speaker, and platform certification are integrated in one unit. This is valuable where in-house AV skills are limited outside major cities. Microsoft's approved device ecosystem reinforces the use of certified all-in-one systems in enterprise tenders. USB-Based Integrated Bars are projected to expand at a 15.73% CAGR through 2031. Their appeal is strongest in Colombia, Chile, and Argentina, where diverse laptop fleets increase demand for straightforward BYOD rooms.
Logitech's Rally AI Camera Pro illustrates the shift toward a higher-value collaboration bar category. The product combines dual-camera AI framing with an in-wall mounting option for boardrooms. PTZ cameras remain important where rooms exceed the field of view of an integrated bar. Codec systems remain relevant for government and regulated deployments that require security controls. Enterprise headsets, speakerphones, and microphone arrays address personal audio and larger-room acoustics. MCUs support multi-site conferencing, while bundled kits serve turnkey small and medium enterprise deployments. The South America video conferencing hardware industry relies on Microsoft and Zoom certification frameworks because these frameworks shape procurement shortlists and pricing.
Commercial Spaces held 62.27% of end-user demand in 2025. Financial services, technology, and professional services firms in Sao Paulo, Buenos Aires, Bogota, and Santiago have prioritized standardized workplace systems. Their programs commonly center on certified products that provide a consistent user experience across offices. Healthcare Facilities are projected to expand at a 15.62% CAGR through 2031. Health systems are moving toward repeatable telehealth workflows that require dependable room devices and support services. The resulting facility-level demand is more durable than emergency purchasing during the pandemic period.
Brazil's smart hospital program supports the standardized procurement of clinical video endpoints. Universities, government agencies, and public bodies procure these solutions through formal tender processes. These buyers prioritize compliance records and regional distribution coverage. Data residency requirements also influence deployment decisions in regulated sectors. Cross-border collaboration increases the value of systems that support local controls while enabling broader interoperability. Therefore, the South America video conferencing hardware industry must support cloud-based, hybrid, and on-premises architectures to meet diverse customer requirements.
Complete Report Scope:
- By Type of Hardware
- Multi-Control Units (MCU)
- Collaboration Bars
- Codec Systems
- USB Cameras
- USB-Based Integrated Bars
- Other Bundled Kits
- Enterprise Headsets
- PTZ Cameras
- Speakerphones and Microphone Arrays
- By End User
- Institutions
- Commercial Spaces
- Healthcare Facilities
- By Application
- Huddle Rooms
- Small Meeting Rooms
- Large Conference Rooms
- Boardrooms and Auditoriums
- By Deployment Mode
- On-Premises
- Cloud-Connected and Hybrid
- By Geography
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
List of Companies Covered in this Report:
- Logitech International S.A.
- Cisco Systems, Inc.
- HP Inc.
- GN Audio A/S
- Huawei Technologies Co., Ltd.
- EPOS Group A/S
- Barco NV
- AVer Information Inc.
- Panasonic Corporation
- Dahua Technology Co., Ltd.
- Yealink Network Technology Co., Ltd.
- ClearOne, Inc.
- Crestron Electronics, Inc.
- Shure Incorporated
- Huddly AS
- Neatframe Ltd.
- Lifesize, Inc.
- Owl Labs Inc.
- DTEN Inc.
- Konftel AB
- MAXHUB, a brand of Returnstar Interactive Technology Group Co., Ltd.
- Lumens Digital Optics Inc.
- ZTE Corporation
- AudioCodes Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Hybrid Work and Distributed-Team Expansion
- 4.2.2 Digital Transformation in Healthcare and Education
- 4.2.3 Fiber, 4G, 5G, and Broadband Infrastructure Improvements
- 4.2.4 AI-Enabled Endpoint Upgrade Cycles
- 4.2.5 Brazil-Led Scale and Geographic Dispersion
- 4.2.6 Interoperability and Platform-Certification Requirements
- 4.3 Market Restraints
- 4.3.1 High Hardware, Installation, and Maintenance Costs
- 4.3.2 Connectivity Limitations and Power Reliability Issues
- 4.3.3 Data Sovereignty and Regulatory Fragmentation
- 4.3.4 Import Duties, Currency Volatility, and Channel Inventory Risk
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type of Hardware
- 5.1.1 Multi-Control Units (MCU)
- 5.1.2 Collaboration Bars
- 5.1.3 Codec Systems
- 5.1.4 USB Cameras
- 5.1.5 USB-Based Integrated Bars
- 5.1.6 Other Bundled Kits
- 5.1.7 Enterprise Headsets
- 5.1.8 PTZ Cameras
- 5.1.9 Speakerphones and Microphone Arrays
- 5.2 By End User
- 5.2.1 Institutions
- 5.2.2 Commercial Spaces
- 5.2.3 Healthcare Facilities
- 5.3 By Application
- 5.3.1 Huddle Rooms
- 5.3.2 Small Meeting Rooms
- 5.3.3 Large Conference Rooms
- 5.3.4 Boardrooms and Auditoriums
- 5.4 By Deployment Mode
- 5.4.1 On-Premises
- 5.4.2 Cloud-Connected and Hybrid
- 5.5 By Geography
- 5.5.1 Brazil
- 5.5.2 Argentina
- 5.5.3 Colombia
- 5.5.4 Chile
- 5.5.5 Peru
- 5.5.6 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Logitech International S.A.
- 6.4.2 Cisco Systems, Inc.
- 6.4.3 HP Inc.
- 6.4.4 GN Audio A/S
- 6.4.5 Huawei Technologies Co., Ltd.
- 6.4.6 EPOS Group A/S
- 6.4.7 Barco NV
- 6.4.8 AVer Information Inc.
- 6.4.9 Panasonic Corporation
- 6.4.10 Dahua Technology Co., Ltd.
- 6.4.11 Yealink Network Technology Co., Ltd.
- 6.4.12 ClearOne, Inc.
- 6.4.13 Crestron Electronics, Inc.
- 6.4.14 Shure Incorporated
- 6.4.15 Huddly AS
- 6.4.16 Neatframe Ltd.
- 6.4.17 Lifesize, Inc.
- 6.4.18 Owl Labs Inc.
- 6.4.19 DTEN Inc.
- 6.4.20 Konftel AB
- 6.4.21 MAXHUB, a brand of Returnstar Interactive Technology Group Co., Ltd.
- 6.4.22 Lumens Digital Optics Inc.
- 6.4.23 ZTE Corporation
- 6.4.24 AudioCodes Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Future Outlook, 2026-2031


