

|
시장보고서
상품코드
2154950
성기 사마귀 치료 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Genital Warts Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
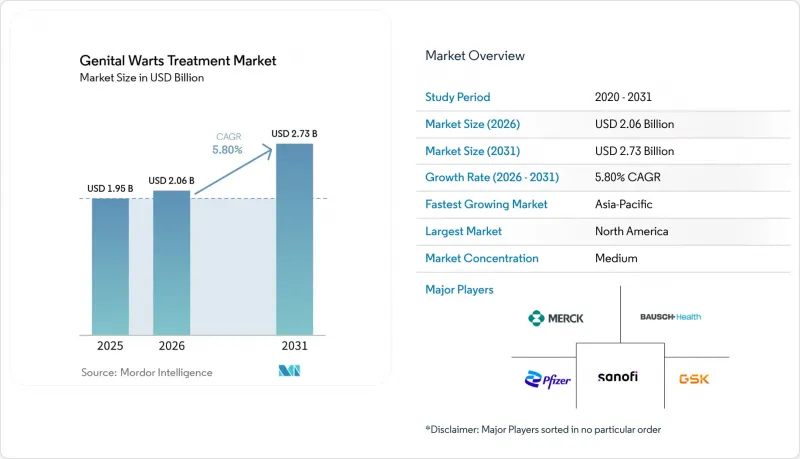
에 따르면 생식기 사마귀 치료 시장 규모는 2025년에 19억 5,000만 달러로 평가되며, 2026년 20억 6,000만 달러에서 2031년까지 27억 3,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 5.80%에 달할 전망입니다.
전 세계 생식기 사마귀 치료 시장의 동향 및 인사이트
저위험형 HPV 감염의 지속적인 발생
저위험형 HPV 감염은 수년에 걸친 백신 접종 프로그램에도 불구하고 생식기 사마귀 치료 시장의 수요를 지속적으로 지원하고 있습니다. 미국 질병통제예방센터(CDC)의 추정에 따르면 미국에서는 4,200만 명 이상이 활동성 HPV 감염을 앓고 있으며, 연간 1,300만 건의 신규 감염이 발생하고 있습니다. 신규 감염의 거의 절반은 15-24세의 젊은 층에서 발생하고 있습니다. 네덜란드의 1차 진료 기록에 따르면 2011-2024년에 생식기 사마귀 발생률은 주민 1,000명당 2.0건에서 2.8건으로 증가했으며, 남성의 발생률은 주민 1,000명당 2.0건에서 3.5건으로 상승했습니다. 추격 접종 프로그램의 대상에서 제외된 25-45세 성인은 여전히 주요 치료 대상 집단이며, 예측 기간 중 처방량을 지탱하는 요인으로 작용하고 있습니다.
환자 스스로 치료법을 선택하는 경향이 높아짐
적격한 원격 진료를 통해 편리한 처방이 가능해짐에 따라 생식기 사마귀 치료 시장에서 환자 스스로의 치료 중요성이 높아지고 있습니다. CDC(미국 질병통제예방센터)는 외음부 및 항문부 사마귀에 대해 이미키모드 5% 크림, 포도필록스 0.5% 용액, 시네카테킨 15% 연고를 권장하고 있습니다. 원격 진단 및 원격 처방이 적절한 경우, 이러한 선택지는 진료소 재방문 횟수를 줄여줄 뿐만 아니라, 진찰부터 처방전 조제까지의 시간을 단축시킵니다. 또한 원격 진료는 사회적 편견을 이유로 환자가 대면 진료를 주저하는 문제도 해결합니다. 외래 진료 접근성이 개선됨에 따라 진료소에서의 치료 일정에 비해 치료 시작 및 환자 지속률이 향상됩니다.
눈에 보이는 사마귀가 사라진 후에도 재발률이 높음
눈에 보이는 병변이 사라졌다고 해서 바이러스가 완전히 근절된 것은 아니기 때문에 재발은 여전히 생식기 사마귀 치료 시장에서 주요한 임상적 과제로 남아 있습니다. 네덜란드의 1차 진료에 관한 분석에 따르면 치료 후 재발률은 20%-30%로 추정되며, 면역 결핍 환자의 경우 더 높은 재발률이 보고되고 있습니다. 2024년 BASHH 가이드라인에서는 모든 치료법에 재발 위험이 있으며, 현재 이용 가능한 치료법 중 HPV의 근절을 보장할 수 있는 것은 없다고 명시하고 있습니다. 이로 인해 환자의 신뢰도가 떨어지고, 처방전 재발급 및 후속 관리가 증가할 가능성이 있습니다. 프랑스의 2024년 가이드라인에서는 단일 요법만으로는 불충분한 경우, 지속적인 제거 효과를 높이기 위해 냉동 요법과 이미키모드 또는 포도필로톡신 외용제를 병용하는 1차 선택 요법으로 방침이 전환되었습니다.
부문 분석
이미키모드는 가이드라인에서의 권고와 5% 및 3.75% 환자 자가 도포용 크림 제제의 이용 가능성에 힘입어, 2025년에는 생식기 사마귀 치료 시장에서 42.35%의 점유율을 차지했습니다. 이 약제는 Toll-유사 수용체 7/8(TLR7/8)의 활성을 통해 국소 자연 면역 반응을 활성화하며, 외성기 및 항문 주위에 사마귀가 있는 적격 환자에게 사용됩니다. 특허 만료에 따라 글렌마크, 테바, 타로, 페리고, 파다기스 등 각사의 제네릭 의약품 경쟁이 격화되었습니다. 제네릭 의약품의 등장으로 환자의 본인 부담금은 경감된 반면, 제조사의 이익률에는 압박이 가해졌습니다. 포도필린 및 포도필록스는 여전히 중요한 세포독성 치료제로 자리매김하고 있으며, 네덜란드의 조사 대상 의료기관에서 외용제 처방 건수의 80.6%를 포도필로톡신이 차지하고 있습니다.
시네카테킨은 2031년까지 연평균 성장률(CAGR) 6.56%를 기록하며 가장 빠르게 성장하는 의약품 카테고리가 될 것으로 예측됩니다. 이러한 성장은 ANI 파마슈티컬스가 외음부 및 항문 주위 사마귀 치료용으로 공급하는 시네카테킨 연고 ‘베레겐’에 의해 지원되고 있습니다. 녹차 유래 카테킨 화합물은 독자적인 작용 기전을 가지고 있으며, 이미키모드와 관련된 피부 반응을 견디지 못하는 환자에게 유익할 가능성이 있습니다. 트리클로로아세트산은 의료 자원이 제한된 환경이나 환자 스스로 치료하기에 부적합한 병변에 대해 의사가 도포하는 치료 옵션으로 여전히 사용되고 있습니다. 그 밖의 약물 유형으로는 인터페론 제제, 난치성 사례에 대한 이소트레티노인, 그리고 개발중인 치료법 등이 있습니다.
지역별 분석
2025년, 북미는 생식기 사마귀 치료 시장 점유율의 40.67%를 차지했습니다. 이는 브랜드 의약품 및 제네릭 의약품의 접근성, 보험 적용 처방, 그리고 광범위한 원격의료 인프라에 힘입은 결과입니다. 미국은 광범위한 처방 채널과 의료 전문가 주도 치료에 대한 폭넓은 접근성 덕분에 지역 수요의 대부분을 차지했습니다. 주요 치료 옵션으로는 이미키모드 제제, 시네카테킨, 포도필록스 등이 있습니다. 제네릭 의약품과의 경쟁으로 인해 브랜드 차별화보다 제품의 접근성 및 보험 적용 리스트 등재가 더욱 중요시되고 있습니다. 캐나다와 멕시코의 기여도는 비교적 낮았으나, 2031년까지의 수요는 면역결핍 환자의 요구와 원격의료 이용 확대에 힘입어 유지될 전망입니다.
유럽은 계속해서 2위 지역 시장으로, 독일, 영국, 프랑스, 이탈리아, 스페인이 치료 수요의 상당 부분을 차지했습니다. 백신 접종을 마친 젊은 층의 발병률은 감소했으나, 지역 전체의 진단 건수는 여전히 많으며, 연간 진단 건수는 60만-80만 명으로 추정됩니다. 프랑스는 2024년에 항문·생식기 콘딜로마 진료 지침을 개정하여, 국소 이미키모드 또는 포도필로톡신과 냉동 요법의 병용을 1차 치료법으로 지정했습니다. 이러한 접근 방식에 따라 한 번의 치료 기간 중 시행되는 치료 횟수가 증가할 가능성이 있습니다. 2025년에 발표된 이탈리아의 감시 데이터에 따르면 진단시 고령 환자의 비율이 증가하고 있는 것으로 나타났으며, 이는 공공 및 민간 의료 시스템 전반에 걸쳐 수요가 안정적임을 지원해 주었습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 6.88%로 성장할 것으로 예측되며, 가장 두드러진 성장을 보일 것으로 전망됩니다. 중국, 인도, 일본, 한국, 호주에서는 진단 접근성 개선 및 의약품 가용성 향상으로 성장이 지원되고 있지만, 현지 치료 관행과 국내 제조사가 시장 규모에 영향을 미치고 있습니다. 중국에서는 국내 이미키모드 제네릭 시장이 집중되어 있으며, 4개 제조사가 이 시장의 98%를 장악하고 있습니다. 인도의 ‘CERVAVAC’은 6형, 11형, 16형, 18형을 포괄하는 4가 HPV 백신입니다. 인도의 ‘보편적 예방접종 프로그램’을 통한 도입과 2026-2027년에 계획된 수출은 장기적인 예방에는 기여하겠지만, 이미 확립된 감염의 치료에는 도움이 되지 않습니다. 중동 및 아프리카는 여전히 초기 단계의 시장이지만, GCC 국가들은 예방 및성 건강 서비스에 투자하고 있으며, 남미에서는 브라질이 수요를 주도하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류·공급망 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 약제 유형별
- 투여 경로별
- 유통 채널별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽 국가
- 아시아태평양
- 중국
- 인도
- 일본
- 호주
- 한국
- 기타 아시아태평양 국가
- 중동 및 아프리카
- GCC
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 시장 점유율 분석
- 기업 개요
- AbbVie Inc.
- ANI Pharmaceuticals, Inc.
- Astellas Pharma Inc.
- Bausch Health Companies Inc.
- Bayer AG
- CryoConcepts, LP
- Glenmark Pharmaceuticals Limited
- GSK plc
- Medtronic plc
- Merck & Co., Inc.
- Novan, Inc.
- Orgenesis Inc.
- Padagis US LLC
- Perrigo Company plc
- Pfizer Inc.
- Sanofi S.A.
- Serum Institute of India Private Limited
- Taro Pharmaceutical Industries Ltd.
- Teva Pharmaceutical Industries Limited
- Verrica Pharmaceuticals Inc.
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the genital warts treatment market size was valued at USD 1.95 billion in 2025 and is estimated to grow from USD 2.06 billion in 2026 to reach USD 2.73 billion by 2031, at a CAGR of 5.80% during the forecast period (2026-2031).
Global Genital Warts Treatment Market Trends and Insights
Persistent Incidence of Low-Risk HPV Infection
Low-risk HPV infections continue to support demand in the genital warts treatment market despite long-standing vaccination programs. The CDC estimates that more than 42 million people in the United States have active HPV infection, with 13 million new infections occurring annually. Nearly half of new infections occur among individuals aged 15-24 years. Dutch primary care records showed that genital warts incidence increased from 2.0 to 2.8 cases per 1,000 residents between 2011 and 2024, while male incidence rose from 2.0 to 3.5 cases per 1,000 residents. Adults aged 25-45 years who were outside catch-up programs remain a key treatment population, supporting prescription volumes over the forecast period.
Rising Preference for Patient-Applied Treatment
Patient-applied therapies are gaining importance in the genital warts treatment market as eligible virtual consultations enable convenient prescribing. The CDC recommends imiquimod 5% cream, podofilox 0.5% solution, and sinecatechins 15% ointment for external anogenital warts. These options reduce repeat clinic visits when remote diagnosis and prescribing are appropriate, while shortening the time from consultation to prescription fulfillment. Virtual care also addresses patient reluctance to seek in-person care due to stigma. Improved outpatient access supports treatment initiation and patient retention compared with clinic-based treatment schedules.
High Recurrence After Visible Wart Clearance
Recurrence remains a key clinical limitation in the genital warts treatment market, as visible lesion clearance does not ensure viral eradication. A Dutch primary care analysis estimated post-treatment recurrence rates at 20%-30%, with higher rates among immunocompromised patients. The 2024 BASHH guideline stated that all treatment modalities carry a recurrence risk and that no available treatment guarantees HPV eradication. This may reduce patient confidence and increase repeat prescriptions and follow-up care. France's 2024 guidance shifted toward first-line combination treatment with cryotherapy and topical imiquimod or podophyllotoxin to improve durable clearance where monotherapy is insufficient.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Treatment Demand in Immunocompromised Patients
- Commercialization of Novel Topical and Lesion-Destructive Therapies
- Stigma-Driven Diagnosis and Treatment Delays
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Imiquimod held 42.35% of the genital warts treatment market share in 2025, supported by guideline recommendations and the availability of 5% and 3.75% patient-applied cream formulations. It activates local innate immune responses through toll-like receptor 7/8 activity and is used for eligible patients with external genital and perianal warts. Patent expiry increased generic competition from Glenmark, Teva, Taro, Perrigo, and Padagis. Generic availability reduced patient out-of-pocket costs while placing pressure on manufacturer margins. Podophyllin and podofilox remained relevant cytotoxic options, with podophyllotoxin accounting for 80.6% of topical prescriptions in participating Netherlands practices.
Sinecatechins is forecast to be the fastest-growing drug category at a CAGR of 6.56% through 2031. Growth is supported by Veregen, a sinecatechins ointment supplied by ANI Pharmaceuticals for external genital and perianal warts. Its green tea-derived catechin compounds offer a differentiated mechanism and may benefit patients who do not tolerate imiquimod-related skin reactions. Trichloroacetic acid remains a physician-applied option for resource-limited settings and lesions unsuitable for patient-applied therapies. Other drug types include interferon products, isotretinoin for recalcitrant cases, and pipeline therapies.
Complete Report Scope:
- By Drug Type
- Imiquimod
- Podophyllin and Podofilox
- Trichloroacetic Acid
- Sinecatechins
- Other Drug Types
- By Route of Administration
- Topical
- Parenteral
- Others
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Specialty Pharmacies
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 40.67% of the genital warts treatment market share in 2025, supported by the availability of branded and generic medicines, reimbursed prescriptions, and widespread telehealth infrastructure. The United States represented the majority of regional demand due to its extensive prescription channels and broad access to clinician-directed care. Key treatment options included imiquimod formulations, sinecatechins, and podofilox. Generic competition increased the importance of product access and formulary placement over brand differentiation. Canada and Mexico made smaller contributions, while demand through 2031 is supported by immunocompromised patient needs and expanding telehealth use.
Europe remained the second-largest regional market, with Germany, the United Kingdom, France, Italy, and Spain accounting for a substantial share of treatment demand. The regional diagnosis burden remained significant despite lower incidence among vaccinated younger populations, with annual diagnoses estimated at 600,000-800,000 individuals. France updated its anogenital condyloma guidance in 2024, placing combined cryotherapy with topical imiquimod or podophyllotoxin in first-line care. This approach can increase the number of treatments used during an episode of care. Italian surveillance published in 2025 showed a growing share of older patients at diagnosis, supporting stable demand across public and private healthcare systems.
Asia-Pacific is forecast to grow at a CAGR of 6.88% through 2031, making it the fastest-growing region. China, India, Japan, South Korea, and Australia support growth through improved diagnostic access and pharmaceutical availability, while local treatment practices and domestic manufacturers influence market size. China has a concentrated domestic generic imiquimod segment, with 4 manufacturers controlling 98% of the segment. India's CERVAVAC is a quadrivalent HPV vaccine covering types 6, 11, 16, and 18; its rollout through India's Universal Immunization Program and planned exports in 2026-2027 can support long-term prevention but do not treat established infection. The Middle East and Africa remain earlier-stage markets, while GCC countries are investing in preventive and sexual health services, and Brazil leads South American demand.
- Abbvie
- ANI Pharmaceuticals
- Astellas Pharma
- Bausch Health
- Bayer
- CryoConcepts, LP
- Glenmark Pharmaceuticals
- GlaxoSmithKline
- Medtronic
- Merck
- Novan, Inc.
- Orgenesis Inc.
- Padagis US LLC
- Perrigo Company
- Pfizer
- Sanofi
- Serum Institute of India Private Limited
- Taro Pharmaceutical Industries Ltd.
- Teva Pharmaceutical Industries
- Verrica Pharmaceuticals Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Persistent Incidence of Low-Risk HPV Infection
- 4.2.2 Increasing Diagnosis of Anogenital Lesions
- 4.2.3 Rising Preference for Patient-Applied Treatment
- 4.2.4 Expansion of Outpatient and Ambulatory Care
- 4.2.5 Increasing Treatment Demand in Immunocompromised Patients
- 4.2.6 Commercialization of Novel Topical and Lesion-Destructive Therapies
- 4.3 Market Restraints
- 4.3.1 High Recurrence After Visible Wart Clearance
- 4.3.2 Treatment-Related Pain and Local Skin Reactions
- 4.3.3 Stigma-Driven Diagnosis and Treatment Delays
- 4.3.4 Limited Evidence for Durable HPV Eradication
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Drug Type
- 5.1.1 Imiquimod
- 5.1.2 Podophyllin and Podofilox
- 5.1.3 Trichloroacetic Acid
- 5.1.4 Sinecatechins
- 5.1.5 Other Drug Types
- 5.2 By Route of Administration
- 5.2.1 Topical
- 5.2.2 Parenteral
- 5.2.3 Others
- 5.3 By Distribution Channel
- 5.3.1 Hospital Pharmacies
- 5.3.2 Retail Pharmacies
- 5.3.3 Online Pharmacies
- 5.3.4 Specialty Pharmacies
- 5.3.5 Others
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 AbbVie Inc.
- 6.3.2 ANI Pharmaceuticals, Inc.
- 6.3.3 Astellas Pharma Inc.
- 6.3.4 Bausch Health Companies Inc.
- 6.3.5 Bayer AG
- 6.3.6 CryoConcepts, LP
- 6.3.7 Glenmark Pharmaceuticals Limited
- 6.3.8 GSK plc
- 6.3.9 Medtronic plc
- 6.3.10 Merck & Co., Inc.
- 6.3.11 Novan, Inc.
- 6.3.12 Orgenesis Inc.
- 6.3.13 Padagis US LLC
- 6.3.14 Perrigo Company plc
- 6.3.15 Pfizer Inc.
- 6.3.16 Sanofi S.A.
- 6.3.17 Serum Institute of India Private Limited
- 6.3.18 Taro Pharmaceutical Industries Ltd.
- 6.3.19 Teva Pharmaceutical Industries Limited
- 6.3.20 Verrica Pharmaceuticals Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


