

|
시장보고서
상품코드
2154971
남미의 영상 감시 스토리지 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)South America Video Surveillance Storage - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
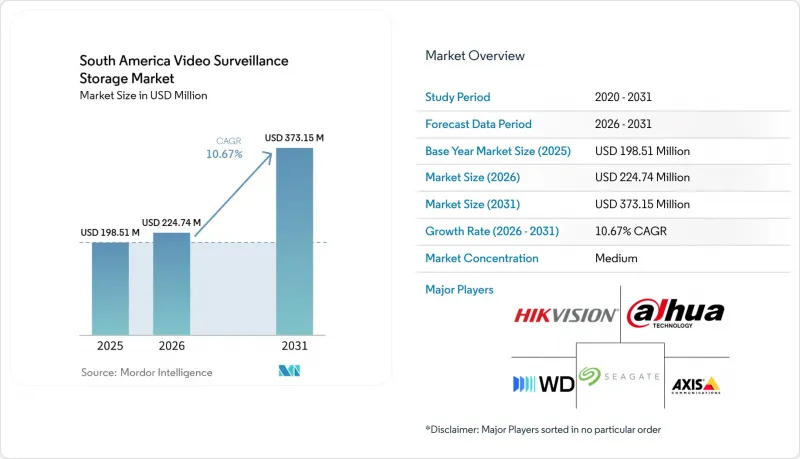
에 따르면 남미의 비디오 감시용 스토리지 시장 규모는 2025년에 1억 9,851만 달러로 평가되며, 2026년 2억 2,474만 달러에서 확대하며, 2031년까지 3억 7,315만 달러에 달할 것으로 예측됩니다.
2026-2031년까지의 예측 기간 중 연평균 성장률(CAGR)은 10.67%에 달할 것으로 전망됩니다.
남미 영상 감시 스토리지 시장의 동향 및 인사이트
스마트 시티 및 공공안전을 위한 영상 네트워크의 확대
공공안전 프로그램으로 인해 남미 영상 감시 스토리지 시장 전반에 걸쳐 통합된 녹화 및 검색 가능한 아카이브에 대한 지속적인 수요가 발생하고 있습니다. 리우데자네이루의 CIVITAS 센터는 2026년에 연간 운영 예산을 1,600만 레알에서 1억 8,000만 레알로 증액하고, 1만 대 이상의 감시 장치를 관리했습니다. 이 도시는 2024년 6월 운영 개시 당시 5,300대였던시 소유의 슈퍼 카메라를 2026년 말까지 6,000대로 증설할 계획입니다. 이러한 설치를 위해서는 관제실 운영을 중단하지 않고도 연속 녹화, 신속한 검색 및 시스템 확장에 대응할 수 있는 스토리지가 필요합니다. 메데인시가 계획 중인 C5i 지휘 센터는 카메라, 자동 번호판 인식 장치, IoT 센서를 통합된 지휘 플랫폼 아래 하나로 통합하는 것입니다. 이러한 프로젝트가 시범 운영 단계에서 영구적인 도시 인프라로 전환됨에 따라 남미의 영상 감시용 스토리지 시장은 그 혜택을 누리게 될 것입니다.
아날로그 녹화에서 IP 및 AI 기반 감시로의 전환
아날로그 DVR 시스템에서 IP 기반 녹화 시스템으로의 전환은 스토리지 수요의 규모와 성격 모두를 변화시킵니다. H.265 인코딩을 채택한 4K IP 카메라는 연속 녹화시 매월 2TB의 원본 영상 데이터를 생성하는 한편, AI 기능을 통해 이벤트 영상 및 검색 가능한 기록이 추가됩니다. 구형 장비를 교체할 때는 각 거점별로 저장 정책, 네트워크 용량 및 녹화 플랫폼 설계를 재검토해야 합니다. 시게이트는 2026년 1월, 주석이 달린 영상을 저장하는 AI 지원 NVR 시스템을 위해 32TB 용량의 ‘SkyHawk AI’ 드라이브를 발표했습니다. 이 드라이브는 10,000시간 이상의 AI 주석이 달린 영상을 지원하며, 표준 감시용 드라이브보다 3배 높은 워크로드 정격을 갖추고 있습니다. 고해상도 카메라에는 호환 가능한 녹화 및 아카이브 용량이 필요하므로 이러한 업데이트 주기는 남미 영상 감시 스토리지 시장의 수요를 지원하고 있습니다.
장기적인 영상 저장에 따른 높은 인프라 및 수명 주기 비용
보관 기간이 길어지면 해상도 및 메타데이터 사용에 따라 스토리지 요구 사항이 증가하므로, 감시 시스템의 총비용이 상승합니다. 감시 시스템 업그레이드가 다른 공공 서비스와 경쟁할 경우, 지자체 구매 담당자가 하드웨어 비용을 마련하기 어려울 수 있습니다. 완전한 교체를 위해서는 주 또는 연방 정부의 공동 자금 지원이 필요하므로 많은 지방 자치 단체에서는 여전히 하이브리드 DVR이나 아날로그 시스템을 계속 사용하고 있습니다. 하이퍼컨버지드 플랫폼은 관리의 복잡성을 줄일 수 있지만, 표준 NVR 교체에 비해 초기 투자 비용이 더 많이 듭니다. 이러한 비용 차이로 인해 자본 예산이 제한된 공공 부문 구매자의 도입이 지연될 가능성이 있습니다. 따라서 남미의 영상 감시 스토리지 시장은 자금 조달 구조나 조달 시기의 영향을 받기 쉬운 상황이 지속되고 있습니다.
부문 분석
2025년 현재, NVR은 스토리지 시스템 부문의 27.52%를 차지하고 있으며, 상업 시설 및 정부 시설에서 확립된 녹화 아키텍처로 자리 잡았습니다. 이러한 도입 실적은 IP 카메라와의 원활한 통합과 지역 공급업체를 통한 폭넓은 접근성을 반영합니다. 지방 자치 단체는 내부 IT 자원을 과도하게 사용하지 않고도 현지 파트너가 시스템 설정 및 지원을 수행할 수 있으므로 NVR을 선호하는 경향이 있습니다. NAS 및 DAS 시스템은 캠퍼스나 분산된 거점을 운영하는 기업 사용자를 대상으로 제공됩니다. DVR은 자금적 제약으로 인해 완전한 IP 전환이 지연되고 있는 공공 시설에서 제한적인 역할을 유지하고 있습니다.
하이퍼컨버지드 인프라(HCI) 기반의 감시용 스토리지는 2026-2031년까지 연평균 성장률(CAGR) 11.25%로 확대될 것으로 예측됩니다. 도시 규모의 관제실에서는 실시간 분석 및 지속적인 영상 기록을 위해 처리 능력과 스토리지 용량을 결합한 솔루션이 필요합니다. 노드 간에 리소스를 통합함으로써 단일 어플라이언스의 고장으로 인한 위험을 줄일 수 있습니다. Axis Communications는 2025년 6월, 28개의 동시 스트림 라이선스와 12TB의 로컬 스토리지를 갖춘 ‘AXIS S1228 AI-Optimized Server’를 출시했습니다. 이 제품은 남미의 영상 감시 스토리지 시장에서 연산 기능과 녹화 기능이 점점 더 긴밀하게 연계되고 있음을 보여줍니다.
2025년 제품 부문에서 하드웨어가 64.83%를 차지했습니다. 이는 초기 프로젝트에서 드라이브, NVR, 서버, 스토리지 인클로저가 필요하기 때문입니다. 구형 DVR 시스템이 IP 기반 장비로 대체됨에 따라 하드웨어는 여전히 중요한 위치를 유지하고 있습니다. 또한 정부 및 기업의 구매 담당자에게는 지속적인 연결에 의존할 수 없는 거점에서도 물리적 용량이 필요합니다. 전문 서비스는 대규모 도입시 통합, 시운전 및 용량 계획을 지원합니다. 이러한 요구 사항으로 인해 사업자가 클라우드 툴을 도입하는 경우에도 장비에 대한 지출은 여전히 중심적인 위치를 차지하고 있습니다.
소프트웨어 및 솔루션 시장은 2026-2031년까지 연평균 성장률(CAGR) 11.40%로 확대될 것으로 예측됩니다. 영상 관리 플랫폼에는 AI 기반 검색, 클라우드 동기화, 자동 저장 제어 등이 표준 기능으로 점점 더 많이 통합되고 있습니다. 관리형 서비스는 전담 보안 IT 팀을 보유하지 않은 금융 서비스 및 소매 기업에 중요합니다. 오픈 플랫폼은 여러 세대에 걸친 장비와 서로 다른 공급업체의 장비를 포함한 카메라 군을 지원할 수 있습니다. 이러한 유연성 덕분에 고객 관계의 일부가 구독, 업데이트, 아카이브 관리로 전환되면서 남미의 영상 감시 스토리지 시장에 변화를 가져오고 있습니다.
2025년에는 데이터 관리 요구 사항과 로컬 녹화 시스템의 도입 기반이 광범위함에 따라 온프레미스형 도입이 시장의 61.36%를 차지했습니다. 정부 기관에서는 로컬 스토리지가 단순한 선호가 아닌, 실용적인 요구 사항이 되는 네트워크를 운영하는 사례가 많이 보입니다. 일부 지자체에서는 통신 환경이 불안정하므로 지속적인 녹화를 위해서는 로컬 녹화가 필수적입니다. 생체인식 이미지를 취급하는 조직은 기밀성이 높은 개인 데이터를 규제하는 규칙을 고려해야 합니다. 이러한 요인들로 인해 남미 영상 감시 스토리지 시장에서 로컬 장비는 여전히 중요한 역할을 계속하고 있습니다.
클라우드 및 비디오 감시 서비스(VaaS)는 2026-2031년까지 연평균 성장률(CAGR) 11.19%로 확대될 것으로 예측됩니다. 여러 거점을 보유한 소매업체, 금융기관 및 운송 사업자는 초기 하드웨어 구입 비용을 대폭 절감하면서도 일원화된 관리를 실현할 수 있다는 점을 중요하게 여기고 있습니다. 반면, 연결이 불안정한 차량 군, 광산, 농업 현장에서는 엣지 스토리지나 기기내 스토리지가 여전히 중요한 역할을 하고 있습니다. 하이브리드 시스템은 로컬 NVR 캐시와 플래그가 지정된 이벤트 또는 장기 보관 기간을 위한 클라우드 업로드를 결합하고 있습니다. 이 모델을 통해 사용자는 운영상의 통제권을 유지하면서 물리적 거점 밖으로도 접근 범위를 넓힐 수 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 거시경제 요인이 시장에 미치는 영향
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 업계 밸류체인 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 스토리지 시스템별
- 제공별
- 배포 모드별
- 기억 매체별
- 스토리지 용량별
- 조직 규모별
- 최종사용자 업계별
- 용도별
- 지역별
- 브라질
- 아르헨티나
- 콜롬비아
- 기타 남미 국가
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Western Digital Corporation
- Seagate Technology Holdings plc
- Toshiba Electronic Devices and Storage Corporation
- Hangzhou Hikvision Digital Technology Co., Ltd.
- Dahua Technology Co., Ltd.
- Axis Communications AB
- Hanwha Vision Co., Ltd.
- Synology Inc.
- QNAP Systems, Inc.
- VIVOTEK Inc.
- MOBOTIX AG
- i-PRO Co., Ltd.
- Milestone Systems A/S
- Genetec Inc.
- Verkada Inc.
- Avigilon Corporation
- Arecont Vision Costar, LLC
- March Networks Corporation
- GeoVision Inc.
- Uniview Technologies Co., Ltd.
- Tiandy Technologies Co., Ltd.
- Intelbras S.A. Industria de Telecomunicacao Eletronica Brasileira
- Infinova International, Inc.
- Pelco, Inc.
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the South America video surveillance storage market size was valued at USD 198.51 million in 2025 and estimated to expand from USD 224.74 million in 2026 to reach USD 373.15 million by 2031, at a CAGR of 10.67% during the forecast period 2026-2031.
South America Video Surveillance Storage Market Trends and Insights
Expansion of Smart-City and Public-Safety Video Networks
Public safety programs are creating a sustained requirement for centralized recording and searchable archives across the South America video surveillance storage market. Rio de Janeiro's CIVITAS center raised its annual operating budget from BRL 16 million to BRL 180 million in 2026 and managed more than 10,000 monitoring devices. The city planned 6,000 city-owned super-cameras by the end of 2026, compared with 5,300 cameras at the June 2024 launch. These installations need storage that can support continuous recording, rapid retrieval, and system expansion without interrupting control-room operations. Medellin's planned C5i command center will combine cameras, automatic number-plate recognition readers, and IoT sensors under a unified dispatch platform. The South America video surveillance storage market benefits when such projects move from trial systems to permanent city infrastructure.
Migration From Analog Recording to IP and AI-Enabled Surveillance
The move from analog DVR systems to IP-based recording changes both the scale and character of storage demand. A 4K IP camera using H.265 encoding can generate 2 TB of raw video monthly during continuous recording, while AI functions add event images and searchable records. Replacing older equipment also requires sites to reconsider retention policies, network capacity, and the design of their recording platform. Seagate introduced its 32 TB SkyHawk AI drive in January 2026 for AI-enabled NVR systems that retain annotated footage. The drive supports more than 10,000 hours of AI-annotated video and has a workload rating 3 times that of standard surveillance drives. This replacement cycle supports demand in the South America video surveillance storage market because higher-resolution cameras require compatible recording and archive capacity.
High Infrastructure and Lifecycle Costs for Long-Term Video Retention
Long retention periods increase the total cost of surveillance systems because storage requirements rise with resolution and metadata use. Hardware costs can be difficult for municipal buyers to fund when surveillance upgrades compete with other public services. Many local governments continue to use hybrid DVR and analog systems because full replacement needs state or federal co-financing. Hyperconverged platforms can reduce management complexity, but they require a larger initial investment than a standard NVR refresh. This cost gap can delay adoption by public buyers with limited capital budgets. The South America video surveillance storage market therefore remains sensitive to financing structures and procurement timing.
Other drivers and restraints analyzed in the detailed report include:
- Rising Demand for High-Resolution and Continuous Video Retention
- Growth of Cloud and Hybrid Video Storage Among Multi-Site Organizations
- Bandwidth, Power Reliability, and Connectivity Gaps
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
NVRs held 27.52% of the storage system segment in 2025, making them the established recording architecture for commercial and government sites. Their installed base reflects straightforward integration with IP cameras and broad availability through regional suppliers. Municipal agencies often favor NVRs because local partners can configure and support systems without extensive internal IT resources. NAS and DAS systems serve enterprise users that operate campuses or distributed locations. DVRs retain a limited role at public sites where capital constraints delay a complete IP transition.
Hyperconverged infrastructure-based surveillance storage is projected to expand at an 11.25% CAGR from 2026 to 2031. City-scale control rooms need combined processing and storage capacity for real-time analytics and continuous video recording. Pooling resources across nodes reduces the risk associated with a single appliance failure. Axis Communications introduced the AXIS S1228 AI-Optimized Server in June 2025 with 28 simultaneous stream licenses and 12 TB of local storage. The product illustrates how compute and recording functions are moving closer together in the South America video surveillance storage market.
Hardware accounted for 64.83% of the offering segment in 2025 because initial projects require drives, NVRs, servers, and storage enclosures. Hardware retained a substantial position as older DVR systems were replaced with IP-focused equipment. Government and enterprise buyers also need physical capacity at sites that cannot rely on continuous connectivity. Professional services support integration, commissioning, and capacity planning for larger deployments. These requirements keep equipment spending central even when operators introduce cloud tools.
Software and solutions is projected to expand at an 11.40% CAGR from 2026 to 2031. Video management platforms increasingly include AI-based search, cloud synchronization, and automated retention controls as standard functions. Managed services are relevant to financial services and retail organizations that lack dedicated security IT teams. Open platforms can support camera fleets that include equipment from several generations and different suppliers. This flexibility changes the South America video surveillance storage market by moving part of the customer relationship toward subscriptions, updates, and archive management.
On-premises deployment accounted for 61.36% of the market in 2025, supported by data control requirements and a large installed base of local recording systems. Government agencies frequently operate networks where local storage is a practical requirement rather than a preference. Unreliable connectivity in some municipalities also makes local recording essential for continuous capture. Organizations handling biometric imagery must consider rules governing sensitive personal data. These factors preserve a major role for local equipment in the South America video surveillance storage market.
Cloud and video surveillance as a service is projected to expand at an 11.19% CAGR from 2026 to 2031. Multi-site retailers, financial institutions, and transportation operators value centralized management without a large initial hardware purchase. Edge and on-device storage remain relevant for fleets, mines, and agricultural sites with intermittent connectivity. Hybrid systems pair local NVR caches with cloud upload for flagged events and longer archive periods. This model lets users retain operational control while extending access beyond the physical site.
Complete Report Scope:
- By Storage System
- Network Attached Storage
- Storage Area Network
- Direct Attached Storage
- Network Video Recorders
- Digital Video Recorders
- Hyperconverged Infrastructure-Based Surveillance Storage
- Other Storage Systems
- By Offering
- Hardware
- Software and Solutions
- Managed Services
- Professional Services
- By Deployment Mode
- On-Premises
- Cloud and Video Surveillance as a Service
- Edge and On-Device Storage
- Hybrid Storage
- By Storage Media
- Hard Disk Drives
- Solid-State Drives
- Hybrid Media Architectures
- By Storage Capacity
- Up to 1 Terabyte
- Above 1 Terabyte to 2 Terabytes
- Above 2 Terabytes to 4 Terabytes
- Above 4 Terabytes
- By Organization Size
- Small and Medium-Sized Enterprises
- Large Enterprises
- By End-User Vertical
- Government and Public Safety
- Banking, Financial Services, and Insurance
- Retail and Consumer Goods
- Transportation and Logistics
- Manufacturing and Industrial
- Healthcare and Life Sciences
- Energy and Utilities
- Education
- Residential and Multi-Unit Housing
- Mining and Remote Sites
- Media and Entertainment
- By Application
- Public Safety and Law Enforcement
- Traffic Monitoring and Automatic Number-Plate Recognition
- Retail Loss Prevention
- Perimeter and Intrusion Protection
- Industrial Safety and Process Monitoring
- Remote-Site and Mining Surveillance
- Residential Monitoring
- By Geography
- Brazil
- Argentina
- Colombia
- Rest of South America
List of Companies Covered in this Report:
- Western Digital Corporation
- Seagate Technology Holdings plc
- Toshiba Electronic Devices and Storage Corporation
- Hangzhou Hikvision Digital Technology Co., Ltd.
- Dahua Technology Co., Ltd.
- Axis Communications AB
- Hanwha Vision Co., Ltd.
- Synology Inc.
- QNAP Systems, Inc.
- VIVOTEK Inc.
- MOBOTIX AG
- i-PRO Co., Ltd.
- Milestone Systems A/S
- Genetec Inc.
- Verkada Inc.
- Avigilon Corporation
- Arecont Vision Costar, LLC
- March Networks Corporation
- GeoVision Inc.
- Uniview Technologies Co., Ltd.
- Tiandy Technologies Co., Ltd.
- Intelbras S.A. Industria de Telecomunicacao Eletronica Brasileira
- Infinova International, Inc.
- Pelco, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Market Drivers
- 4.3.1 Expansion of Smart-City and Public-Safety Video Networks
- 4.3.2 Migration From Analog Recording to IP and AI-Enabled Surveillance
- 4.3.3 Rising Demand for High-Resolution and Continuous Video Retention
- 4.3.4 Growth of Cloud and Hybrid Video Storage Among Multi-Site Organizations
- 4.3.5 Local Data Processing for Connectivity-Constrained Surveillance Sites
- 4.3.6 Regional Data-Center Expansion Enabling Lower-Latency Video Storage
- 4.4 Market Restraints
- 4.4.1 High Infrastructure and Lifecycle Costs for Long-Term Video Retention
- 4.4.2 Bandwidth, Power Reliability, and Connectivity Gaps
- 4.4.3 Fragmented Privacy and Facial-Recognition Governance
- 4.4.4 Import Duties, Currency Volatility, and Replacement-Part Lead Times
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Storage System
- 5.1.1 Network Attached Storage
- 5.1.2 Storage Area Network
- 5.1.3 Direct Attached Storage
- 5.1.4 Network Video Recorders
- 5.1.5 Digital Video Recorders
- 5.1.6 Hyperconverged Infrastructure-Based Surveillance Storage
- 5.1.7 Other Storage Systems
- 5.2 By Offering
- 5.2.1 Hardware
- 5.2.2 Software and Solutions
- 5.2.3 Managed Services
- 5.2.4 Professional Services
- 5.3 By Deployment Mode
- 5.3.1 On-Premises
- 5.3.2 Cloud and Video Surveillance as a Service
- 5.3.3 Edge and On-Device Storage
- 5.3.4 Hybrid Storage
- 5.4 By Storage Media
- 5.4.1 Hard Disk Drives
- 5.4.2 Solid-State Drives
- 5.4.3 Hybrid Media Architectures
- 5.5 By Storage Capacity
- 5.5.1 Up to 1 Terabyte
- 5.5.2 Above 1 Terabyte to 2 Terabytes
- 5.5.3 Above 2 Terabytes to 4 Terabytes
- 5.5.4 Above 4 Terabytes
- 5.6 By Organization Size
- 5.6.1 Small and Medium-Sized Enterprises
- 5.6.2 Large Enterprises
- 5.7 By End-User Vertical
- 5.7.1 Government and Public Safety
- 5.7.2 Banking, Financial Services, and Insurance
- 5.7.3 Retail and Consumer Goods
- 5.7.4 Transportation and Logistics
- 5.7.5 Manufacturing and Industrial
- 5.7.6 Healthcare and Life Sciences
- 5.7.7 Energy and Utilities
- 5.7.8 Education
- 5.7.9 Residential and Multi-Unit Housing
- 5.7.10 Mining and Remote Sites
- 5.7.11 Media and Entertainment
- 5.8 By Application
- 5.8.1 Public Safety and Law Enforcement
- 5.8.2 Traffic Monitoring and Automatic Number-Plate Recognition
- 5.8.3 Retail Loss Prevention
- 5.8.4 Perimeter and Intrusion Protection
- 5.8.5 Industrial Safety and Process Monitoring
- 5.8.6 Remote-Site and Mining Surveillance
- 5.8.7 Residential Monitoring
- 5.9 By Geography
- 5.9.1 Brazil
- 5.9.2 Argentina
- 5.9.3 Colombia
- 5.9.4 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Western Digital Corporation
- 6.4.2 Seagate Technology Holdings plc
- 6.4.3 Toshiba Electronic Devices and Storage Corporation
- 6.4.4 Hangzhou Hikvision Digital Technology Co., Ltd.
- 6.4.5 Dahua Technology Co., Ltd.
- 6.4.6 Axis Communications AB
- 6.4.7 Hanwha Vision Co., Ltd.
- 6.4.8 Synology Inc.
- 6.4.9 QNAP Systems, Inc.
- 6.4.10 VIVOTEK Inc.
- 6.4.11 MOBOTIX AG
- 6.4.12 i-PRO Co., Ltd.
- 6.4.13 Milestone Systems A/S
- 6.4.14 Genetec Inc.
- 6.4.15 Verkada Inc.
- 6.4.16 Avigilon Corporation
- 6.4.17 Arecont Vision Costar, LLC
- 6.4.18 March Networks Corporation
- 6.4.19 GeoVision Inc.
- 6.4.20 Uniview Technologies Co., Ltd.
- 6.4.21 Tiandy Technologies Co., Ltd.
- 6.4.22 Intelbras S.A. Industria de Telecomunicacao Eletronica Brasileira
- 6.4.23 Infinova International, Inc.
- 6.4.24 Pelco, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


